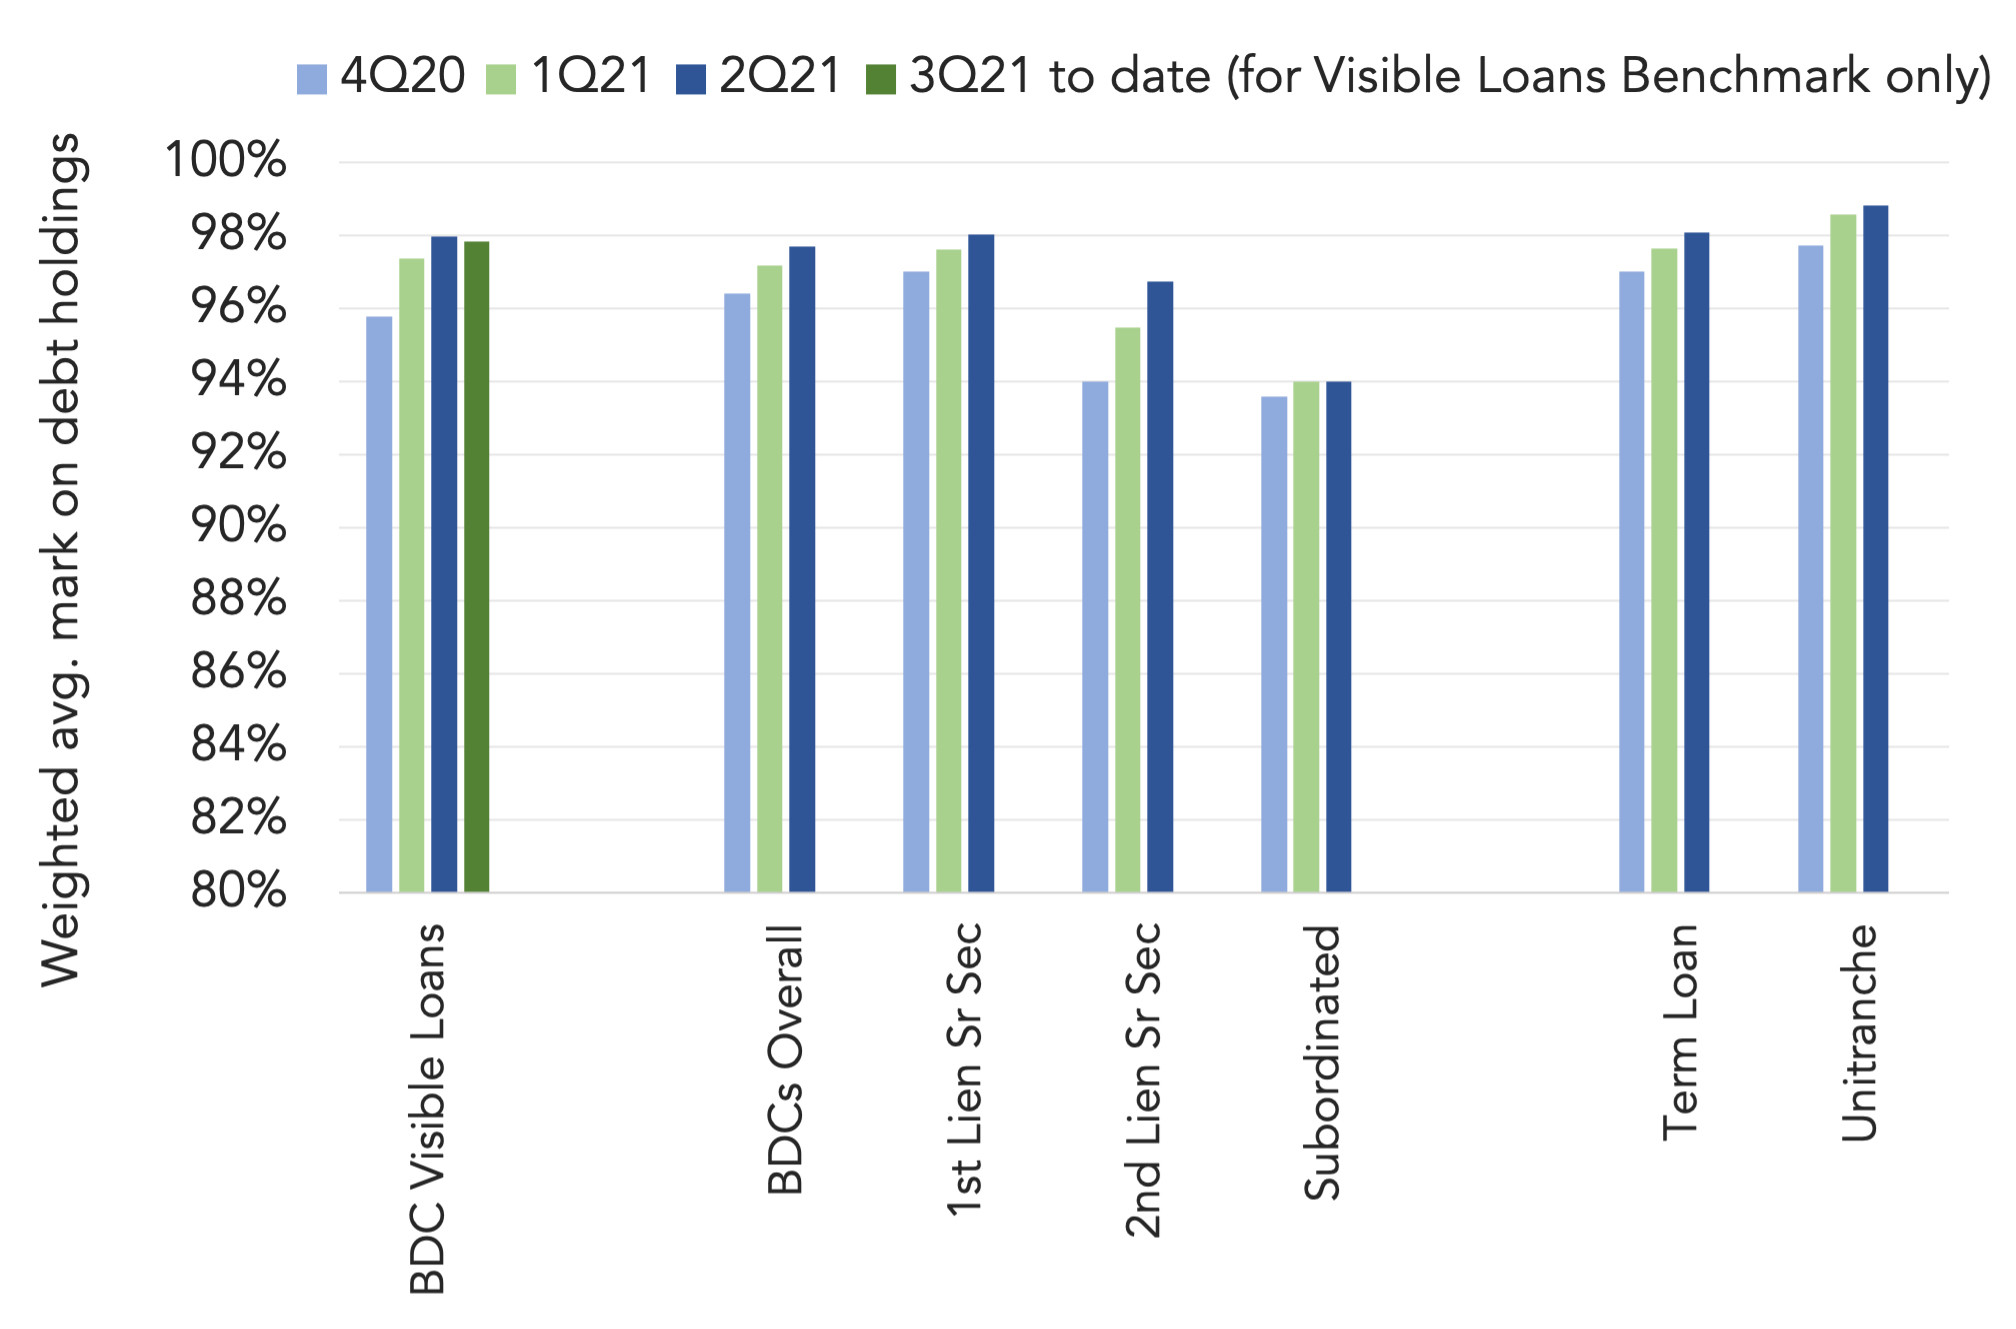
BDC’s have benefited from rising asset valuations in recent months, with both loan and equity holdings posting gains. During 2Q21 (the most recent quarter for which data is available), the weighted average mark on BDC debt holdings climbed to 97.71% from 97.18% in the prior quarter and is up from 96.41% at the start of the year.
Rising valuations have been posted across the risk spectrum this year, with second-lien loans in BDC’s outperforming first-liens amid strong lender demand for yield, a robust economic backdrop and sustained earnings growth. Digging deeper into the first-lien loan category, the fair value of both term loans and unitranches have climbed, with unitranches increasing to 98.82% as of June 30, from 97.72% at the start of the year. The higher valuations trend is reinforced by results from the LPC BDC Visible Loans Benchmark (which tracks loans in BDC’s with active mark-to-market pricing).
This cohort is bid at an average of 97.85% as of September 7, up from 95.79% at the end of last year. BDC performance has also been buoyed by equity gains in recent months. The appreciation in valuations across all BDC asset types during the last twelve months through June 30 has pushed the aggregate net change in unrealized gains to over US$9bn in this time period, with further gains booked in 3Q21 to date.
(Past performance is no guarantee of future results.)



Latest news

US Leveraged Loan Issuance Rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.