


Markit Recap – 1/8/2018

Italian bank CDS amid senior non-preferred issuance
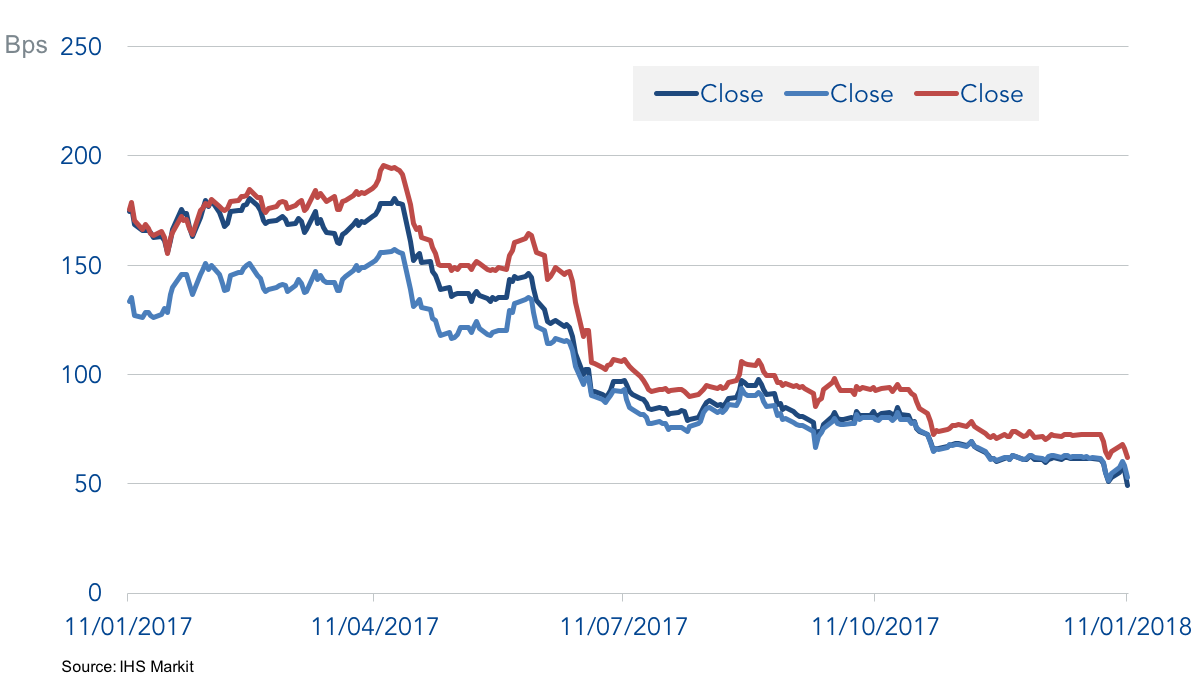
In our last article of 2017 we noted that it was widely billed as the year of political risk. Perhaps those in the fixed income world will call 2018 the year of TLAC (Total Loss Absorbing Capacity). It doesn’t have quite the same resonance, but there is little doubt that bank credit in both cash and CDS will fundamentally change over the next 12 months.
Banks are expected to comply with the TLAC standard by 1 January 2019. Institutions have been busy issuing debt that will qualify for TLAC eligibility, either in the form of regular senior unsecured debt issued by holding companies (mainly in the UK and Switzerland) or senior non-preferred (SNP) debt. The latter is a new tier of debt introduced by the European Commission specifically to help banks meet TLAC capital requirements. French and Spanish G-SIBs (TLAC only applies to global systemically important banks) sold considerable amounts of SNP paper last year and will issue more as the 2019 deadline looms.
Though the EC introduced the new tier, legislation is required at the national level before banks can sell SNP debt. France was the forerunner, followed sometime after by Spain and Belgium. The need for national legislation acted as a roadblock for TLAC compliance, particularly for banks domiciled in jurisdictions where parliaments move slowly.
Italy is a prime example. Early indications were that it was going to take a statutory route to TLAC, i.e. subordinate senior unsecured debt to deposits. This is similar – though not identical – to the route taken by Germany in 2016. But just before year-end we received news that the Italian 2018 budget law was approved by parliament, including provisions for banks to issue SNP bonds.
Unicredit – the only Italian G-SIB – swiftly took advantage of the new law. On January 11 it sold its first SNP bonds, and we can expect further issuance in the coming months as the bank has plenty of catching up to do on its peers elsewhere in Europe.
Unicredit’s 5-year CDS rallied 7bps to 49bps after the oversubscribed bond sale. But it should be noted that the senior CDS tier isn’t applicable for SNP debt. A new CDS tier – SNRLAC – was introduced to allow for SNP deliverability and aligns SNP debt with TLAC eligible bonds subordinated structurally (issued out of HoldCos) and through statute (Germany). This raises many interesting legal and pricing questions that will be addressed in future columns.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…