


Markit Recap – 11/14/2016

We noted last month that realised volatility in the European investment grade CDS market, as measured by the Markit VolX index, was at its lowest for two years. By the end of October, volatility had dipped to 18%, which was the lowest level since the heady days of June 2007. A number of future events were mooted that had the potential to trigger market uncertainty, including next month’s Italian referendum.
But a victory for Donald Trump in the US presidential election was viewed by most as a highly unlikely occurrence. Spreads rallied in the run up to the vote, with the Markit CDX.NA.IG tightening from 81bps to 75bps and the Markit iTraxx Europe moving from 76bps to 73bps in the two days prior to the election on November 8.
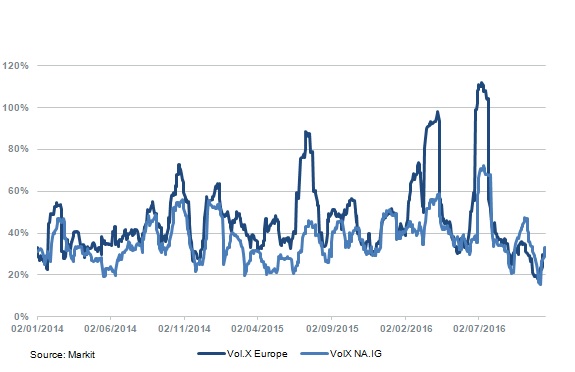
So the shock win for Trump, widely viewed as a maverick compared to the establishment figure of Hilary Clinton, might have been expected to produce volatility on a Brexit-like scale. And the initial reaction in the credit markets was indeed negative, with the Markit iTraxx Europe widening by 8bps on the morning of November 9th. But the US markets took the news in their stride, and by the end of the session both European and US CDS indices were slightly tighter compared to the previous day’s close. The VolX Europe rose to 30% this week, a modest move in comparison with Brexit, when the VolX Europe ballooned to over 100% in the wake of the referendum.
Perhaps the markets have confidence in Trump’s ability to deliver on his promises of economic growth and jobs. An expansionary fiscal policy could achieve this goal, though it won’t be easy to implement in a country with over 100% debt-to-GDP ratio. Trump’s gaffes may have not cost him the election, but serious missteps as president could reignite credit volatility.
Political risk is the order of the day, with Trump as president-elect and the Italian referendum due next month. But CDS users also need to be aware of micro event risk, such as orphaning. We saw an example this week with the merger of Nordic credit management services firms Intrum Justitia and Lindorff. The latter’s debt was issued from Lock Lower Holdings, but its debt will be paid back as part of the merger. This leaves the CDS referencing an entity that will have no obligations. Lock Lower’s 5-year spreads dropped from 600bps to 136bps after the announcement. This will have been particularly painful for buyers of protection that gained from recent credit deterioration.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
Private Credit Defaults 101: Beyond the Noise
Like any good school year, this series went by fast. But unlike the end of the year, we’re not out for the summer.