


Markit Recap – 6/5/2017

Banco Popular Senior and Sub move in opposite directions
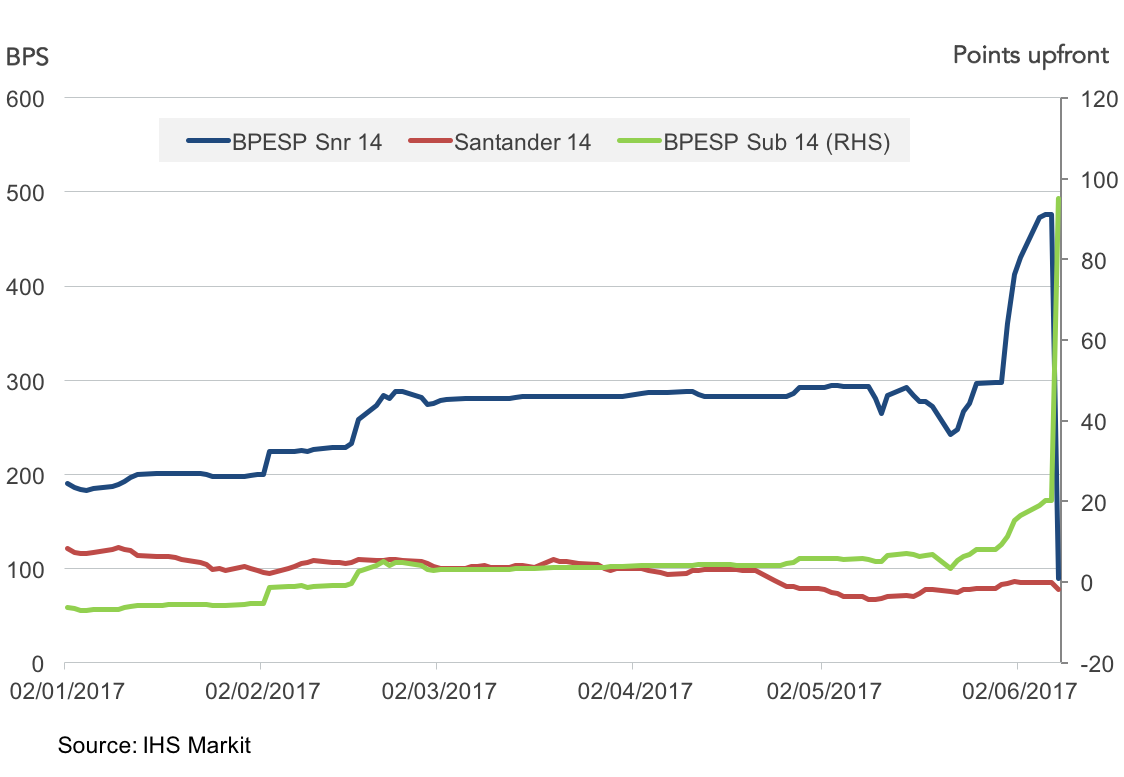
The CoCo market received all the plaudits following Banco Popular’s enforced “rescue” by Santander yesterday.
But another, more established financial instrument will also be tested by the Spanish bank’s resolution. A question was put to the ISDA Determinations Committee yesterday, asking if a restructuring/governmental intervention has occurred. On the face of it, this case looks tailor made for the ISDA 2014 definitions. The ECB’s Single Resolution Board, in conjunction with the Spanish FROB, declared the bank no longer viable, leading to the write down of AT1 and tier 2 subordinated debt. This includes the SRO for subordinated CDS.
Under the 2014 definitions this appears to be a likely governmental intervention credit event (though we will have to wait until the ISDA DC make their decision). The market is certainly treating it as such – the sub 14 5Y CDS jumped from 20 points upfront to 95 points upfront. The probable recovery rate is zero, accurately reflecting the loss of bondholders. Senior CDS would succeed to Santander – remember 2014 definitions split out senior and sub – and the market is again pricing in this outcome, with BPESP senior 14 CDS rallying from nearly 500bps to 90bps (converging on Santander’s 78bps). If such a scenario emerges, it would show the CDS instrument functioning as it should do, comparing favourably with the debacles we saw with SNS bank and Banco Espirito Santo.
But we also need to remember that there are many existing trades on 2003 definitions – indeed there continues to be liquidity – and we know from painful experience that this framework struggles to cope with state intervention in banks. If a restructuring credit event is declared by the ISDA DC, it would trigger both sub and senior CDS on 2003 trades. Without asset package delivery, the recovery would be determined by the remaining senior bonds, which would have been boosted considerably by the Santander takeover. So a scenario where the recovery is again unrepresentative of the cash market – as we saw with SNS – could result.
The CDS market has made great strides in recent years, and its legal structure is built to cope with the new resolution regime in Europe. But market participants, vendors and clearing houses still need to be aware of its history and use their expertise to meet the challenges posed by cases such as Banco Popular.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.