


Markit Recap – 7/16/2018

The news wires are full of headlines around Trump, trade wars and Brexit. A mercantilist USA and a UK government clinging on by its fingertips are not conducive to positive market sentiment. Yet spreads appear unaffected by the political chaos; spreads have tightened, rather than widened. The Markit iTraxx Europe is trading at 65bps, a 10bps rally over July. UK sovereign CDS – an infrequently traded contract – is quoted at 23bps, 8 bps wider from its February level but hardly indicating distress.
The markets clearly have a sanguine view of how things will turn out. Perhaps political risk is being underpriced – it wouldn’t be the first time – or maybe their other factors underpinning current valuations.
One such theme is expectations of a strong US earning season. Several firms have beat consensus estimates, boding well for the firms still to report. Alcoa used to be synonymous with opening the season, though this is no longer the case. The company is now known as Arconic (not to be confused with Alcoa Corp, which was the result of a spin-off) and is due to report later this month. But it hit the headlines recently after it was linked to a development reminiscent of pre-GFC credit markets – leveraged buyouts.
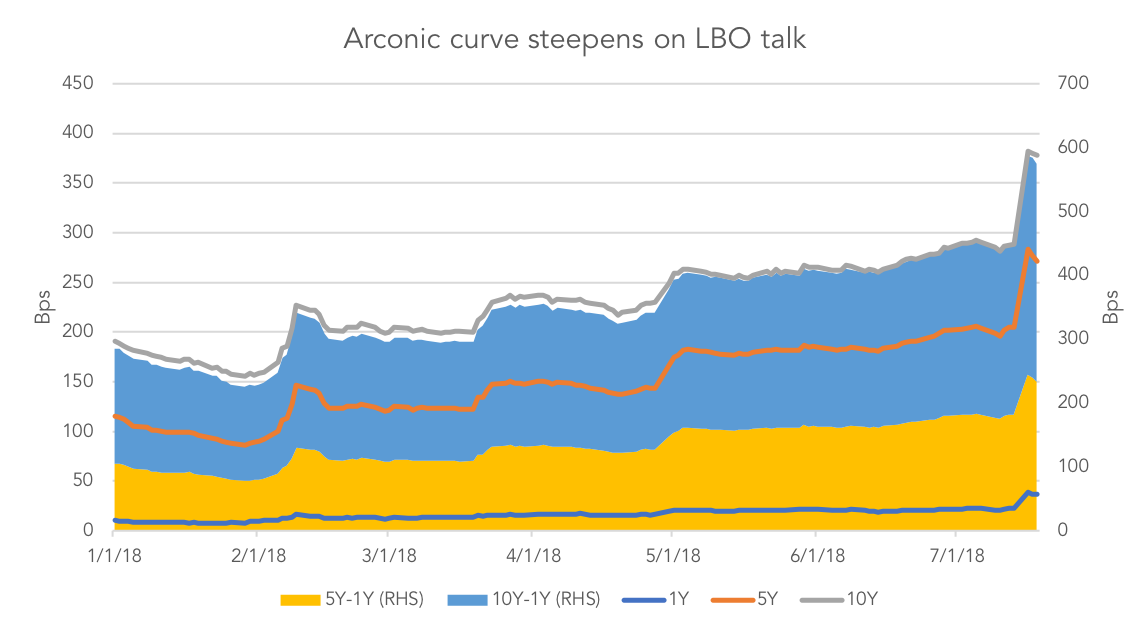
A newspaper report suggested that the company is a target for a number of private equity firms. Those with long memories will recall that a LBO is an event which is shareholder-friendly but negative for bondholders – in other words, the stock price goes but spreads widen. This is exactly what occurred in the case of Arconic. The firm’s share price went up 10% while the five-year CDS widened from 205bps to 283bps, its widest level since the corporate restructuring in November 2016. IHS Markit liquidity data shows that the number of quotes jumped to 1,121 on the day of the news (typically there are about 150 to 350 quotes)
Given that the move was prompted by one report, the jump in spreads may be surprising to some. But the prospect of Arconic ending up with LBO debt on its balance sheet and a significant deterioration in credit quality is usually enough to elevate spreads.
Another common side effect of LBOs – either speculation or real – is a steepening in the credit curve. The debt maturity profile of names taken private often points towards medium-term refinancing risks, particularly as bank loans often play a part in the funding of the acquisition. Again, this is what has occurred with Arconic – the difference between the 1-year and 5-year spread 244bps from 182bps, while the 1-year 10-year basis rose to 343bps from 265bps.
Arconic was already under pressure prior to the LBO talk, mainly due to its exposure to aluminium prices and the pervading talk of a trade war. The logic of a buyout is apparent, but it is not the only option for the firm. Those with experience of the credit markets will know that LBO speculation doesn’t always come to fruition.
An interesting footnote occurred this week when a succession event on Arconic was declared by the ISDA DC. The event was prompted by a domicile change from Pennsylvania to Delaware via a re-incorporation merger. CDS market participants should ensure that they have the necessary reference data to protect them from operational risk.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com




Latest news
The Recovery Shot
Trouble off the tee doesn’t always translate to trouble on the scorecard.

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Private Credit Defaults 101: Scrambling for Par
Seve Ballesteros won four majors in the 1980s despite being, by his own admission, one of the wildest drivers of the golf ball on tour.