


Markit Recap – 9/11/2017

CDS orphaning risk
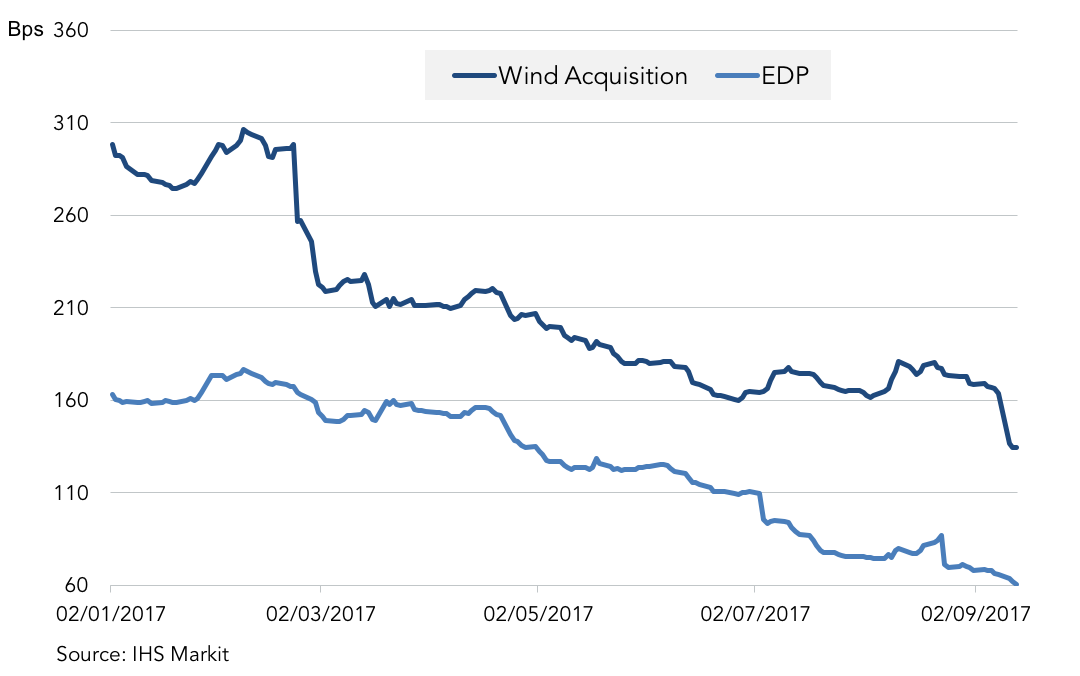
Wind Acquisition Finance and Energias de Portugal (EDP) are two credits that appear to have little in common. One is a financing vehicle for an Italian telecoms group, while the other is a Portuguese electricity operator. There is a tenuous link – EDP is one of the world’s largest wind power producers.
But over recent weeks the entities’ spreads have rallied, and the credit improvement was driven by the same technical factor – the risk of orphaning. An orphaned CDS is one where there are no deliverables, effectively making the CDS near worth less. This clearly results in CDS spreads tightening, though the rally is not triggered by underlying credit improvement.
In the case of Wind, the orphaning rumours are triggered by reports that the debt issued out of Wind Acquisition (the entity referenced by CDS) will be repaid and refinanced through a different entity. Wind was taken private in in the noughties LBO boom and has a complicated capital structure typical of such companies. It has long been one of the most liquid names in the European high-yield universe and is a constituent of the Markit iTraxx Crossover. There is no concrete news on the refinancing, so this name could be subject to further volatility, but its current spread level of 134bps is the tightest on record.
EDP is a more solid credit and has rallied in recent years thanks to the Portuguese sovereign’s perceived credit improvement. But the recent tightening in EDP’s CDS was likely prompted by orphaning risk. Debt is no longer being issued from the Energias de Portugal entity; bonds are now sold out of EDP Finance BV. This is reflected in the composition of the new iTraxx indices. Energias de Portugal will not be included in iTraxx Europe Series 28 as it has less than €100 million in debt outstanding. But EDP Finance BV will be included, reflecting its status as the main EDP financing vehicle.
At the moment Energias de Portugal is the more liquid EDP entity, with a Markit liquidity score of 1 compared to a score of 4 for EDP Finance BV. But this can be expected to change after the roll, as the inclusion of a name in the iTraxx Europe typically puts a rocket under liquidity.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…