


Click here to learn more.
Join Fitch for the upcoming Outlook panel: Credit Outlook 2025 Private Credit
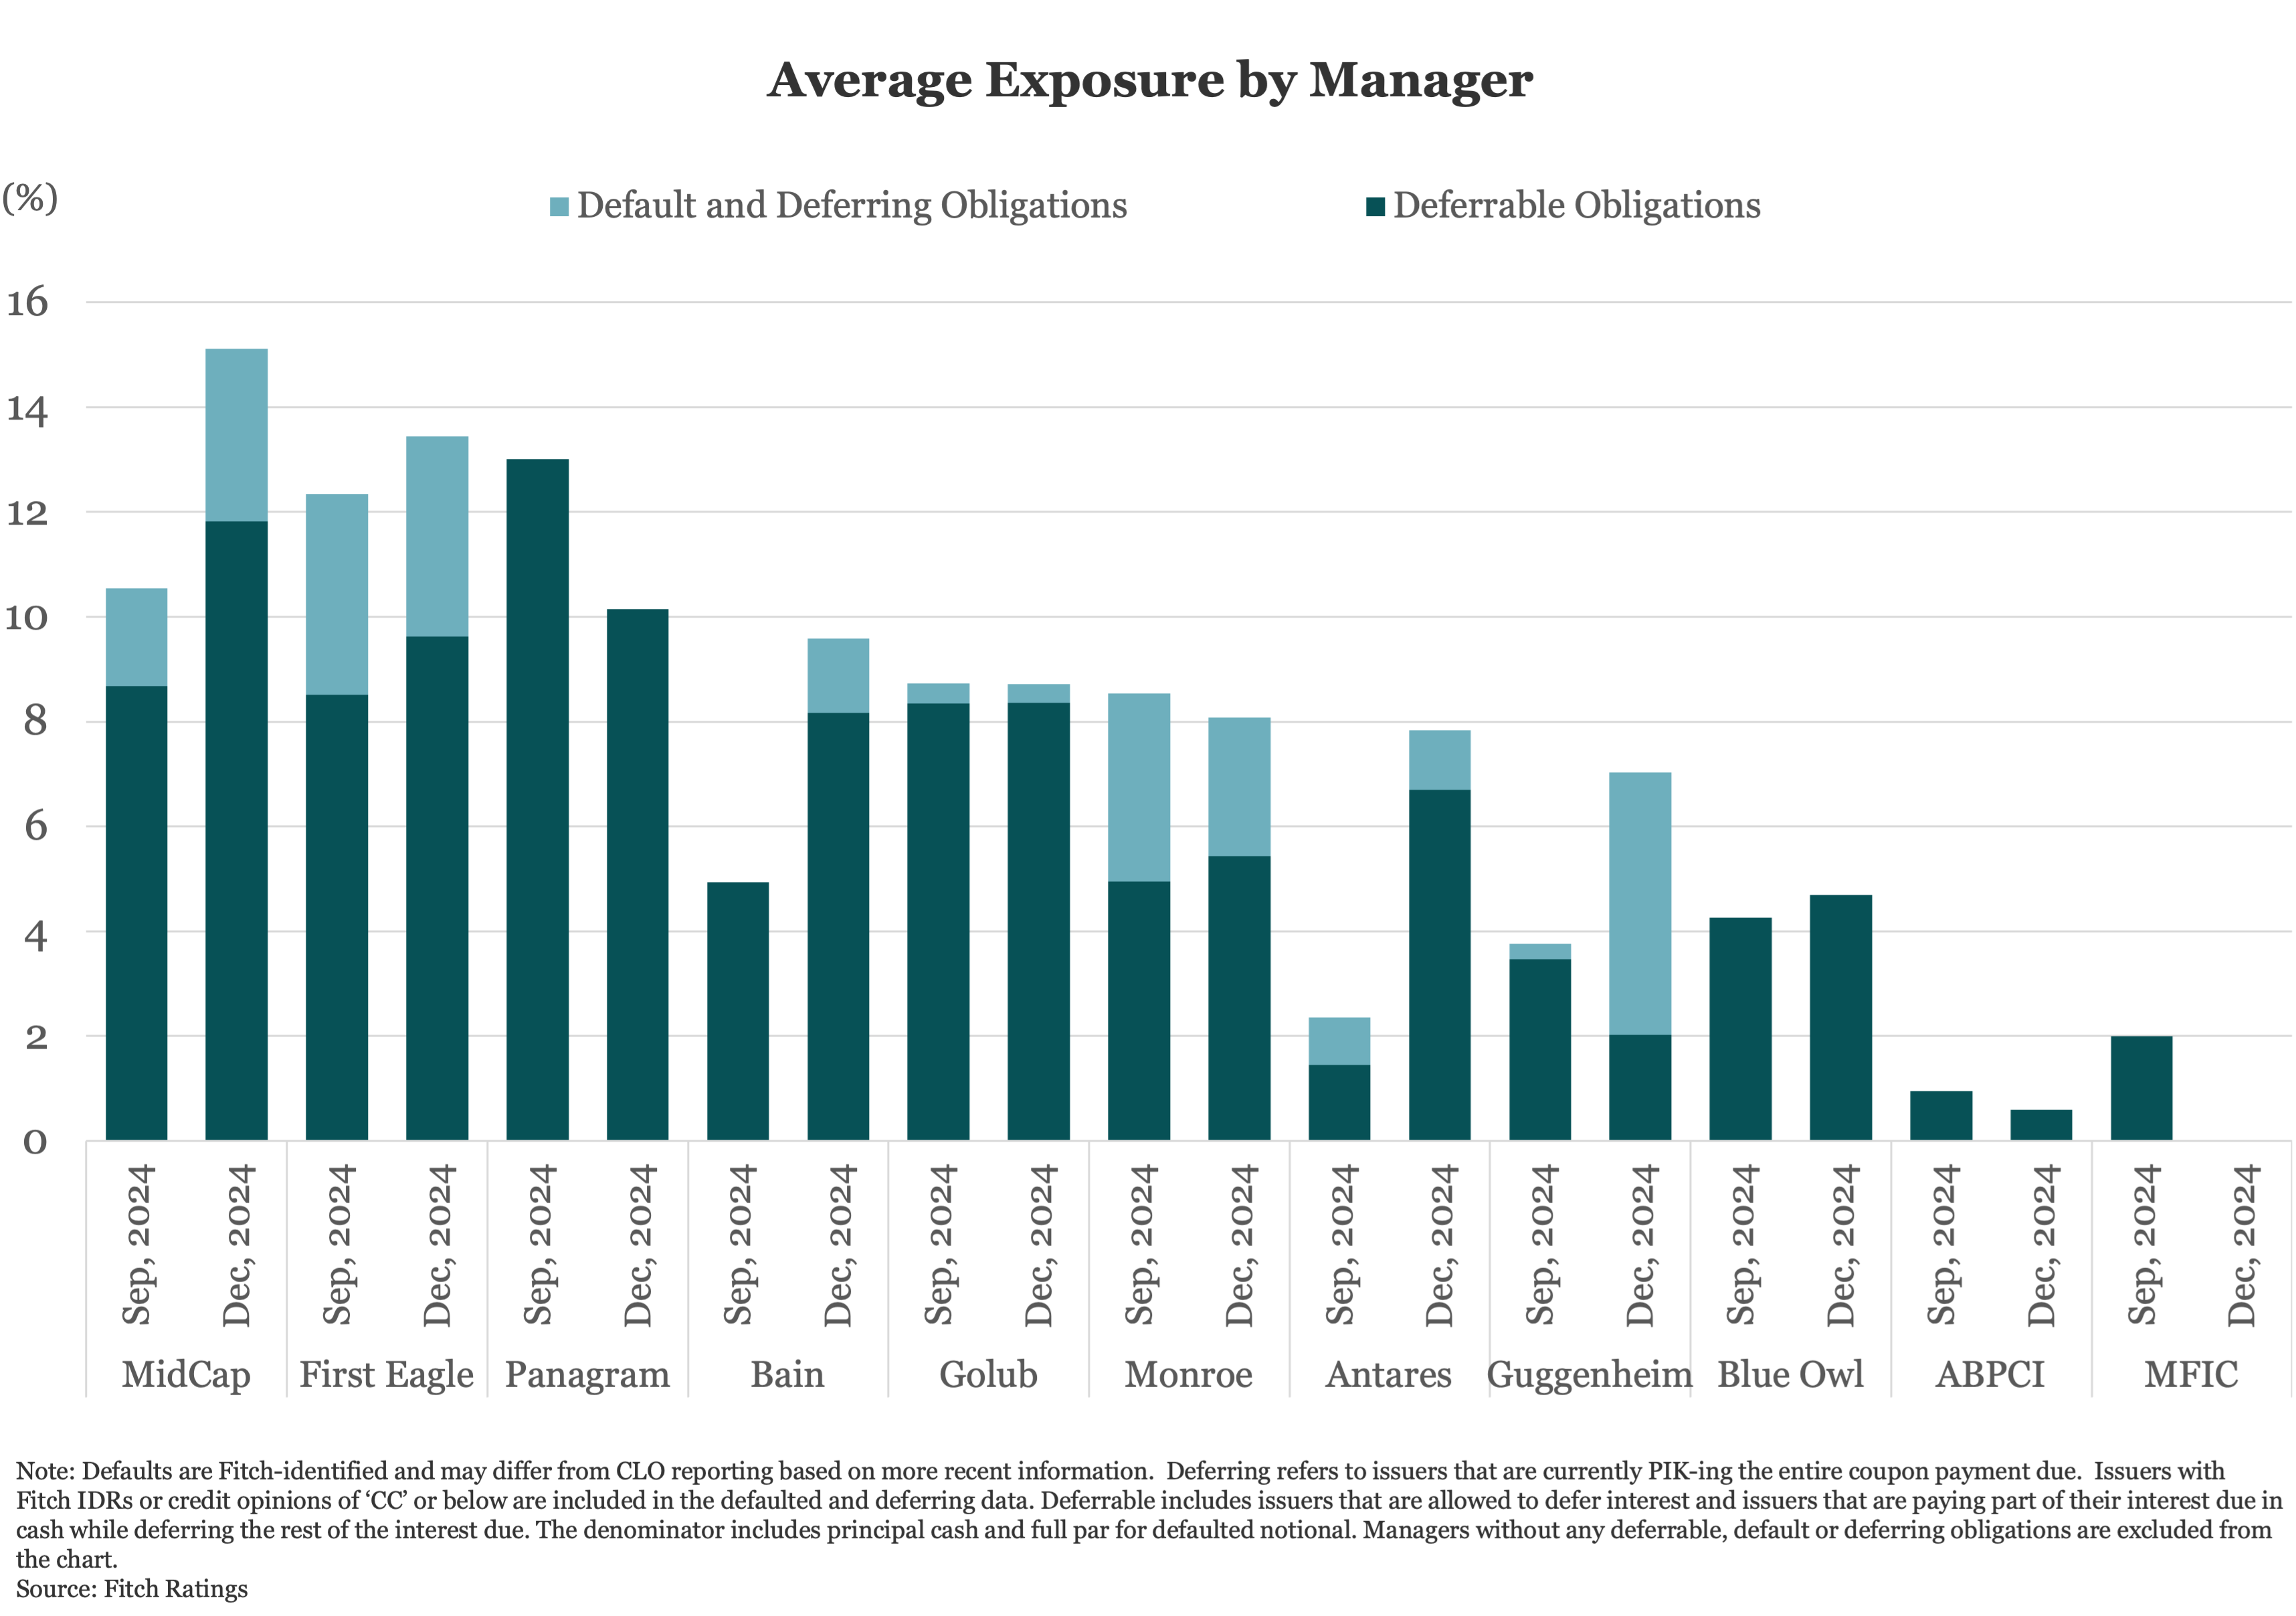
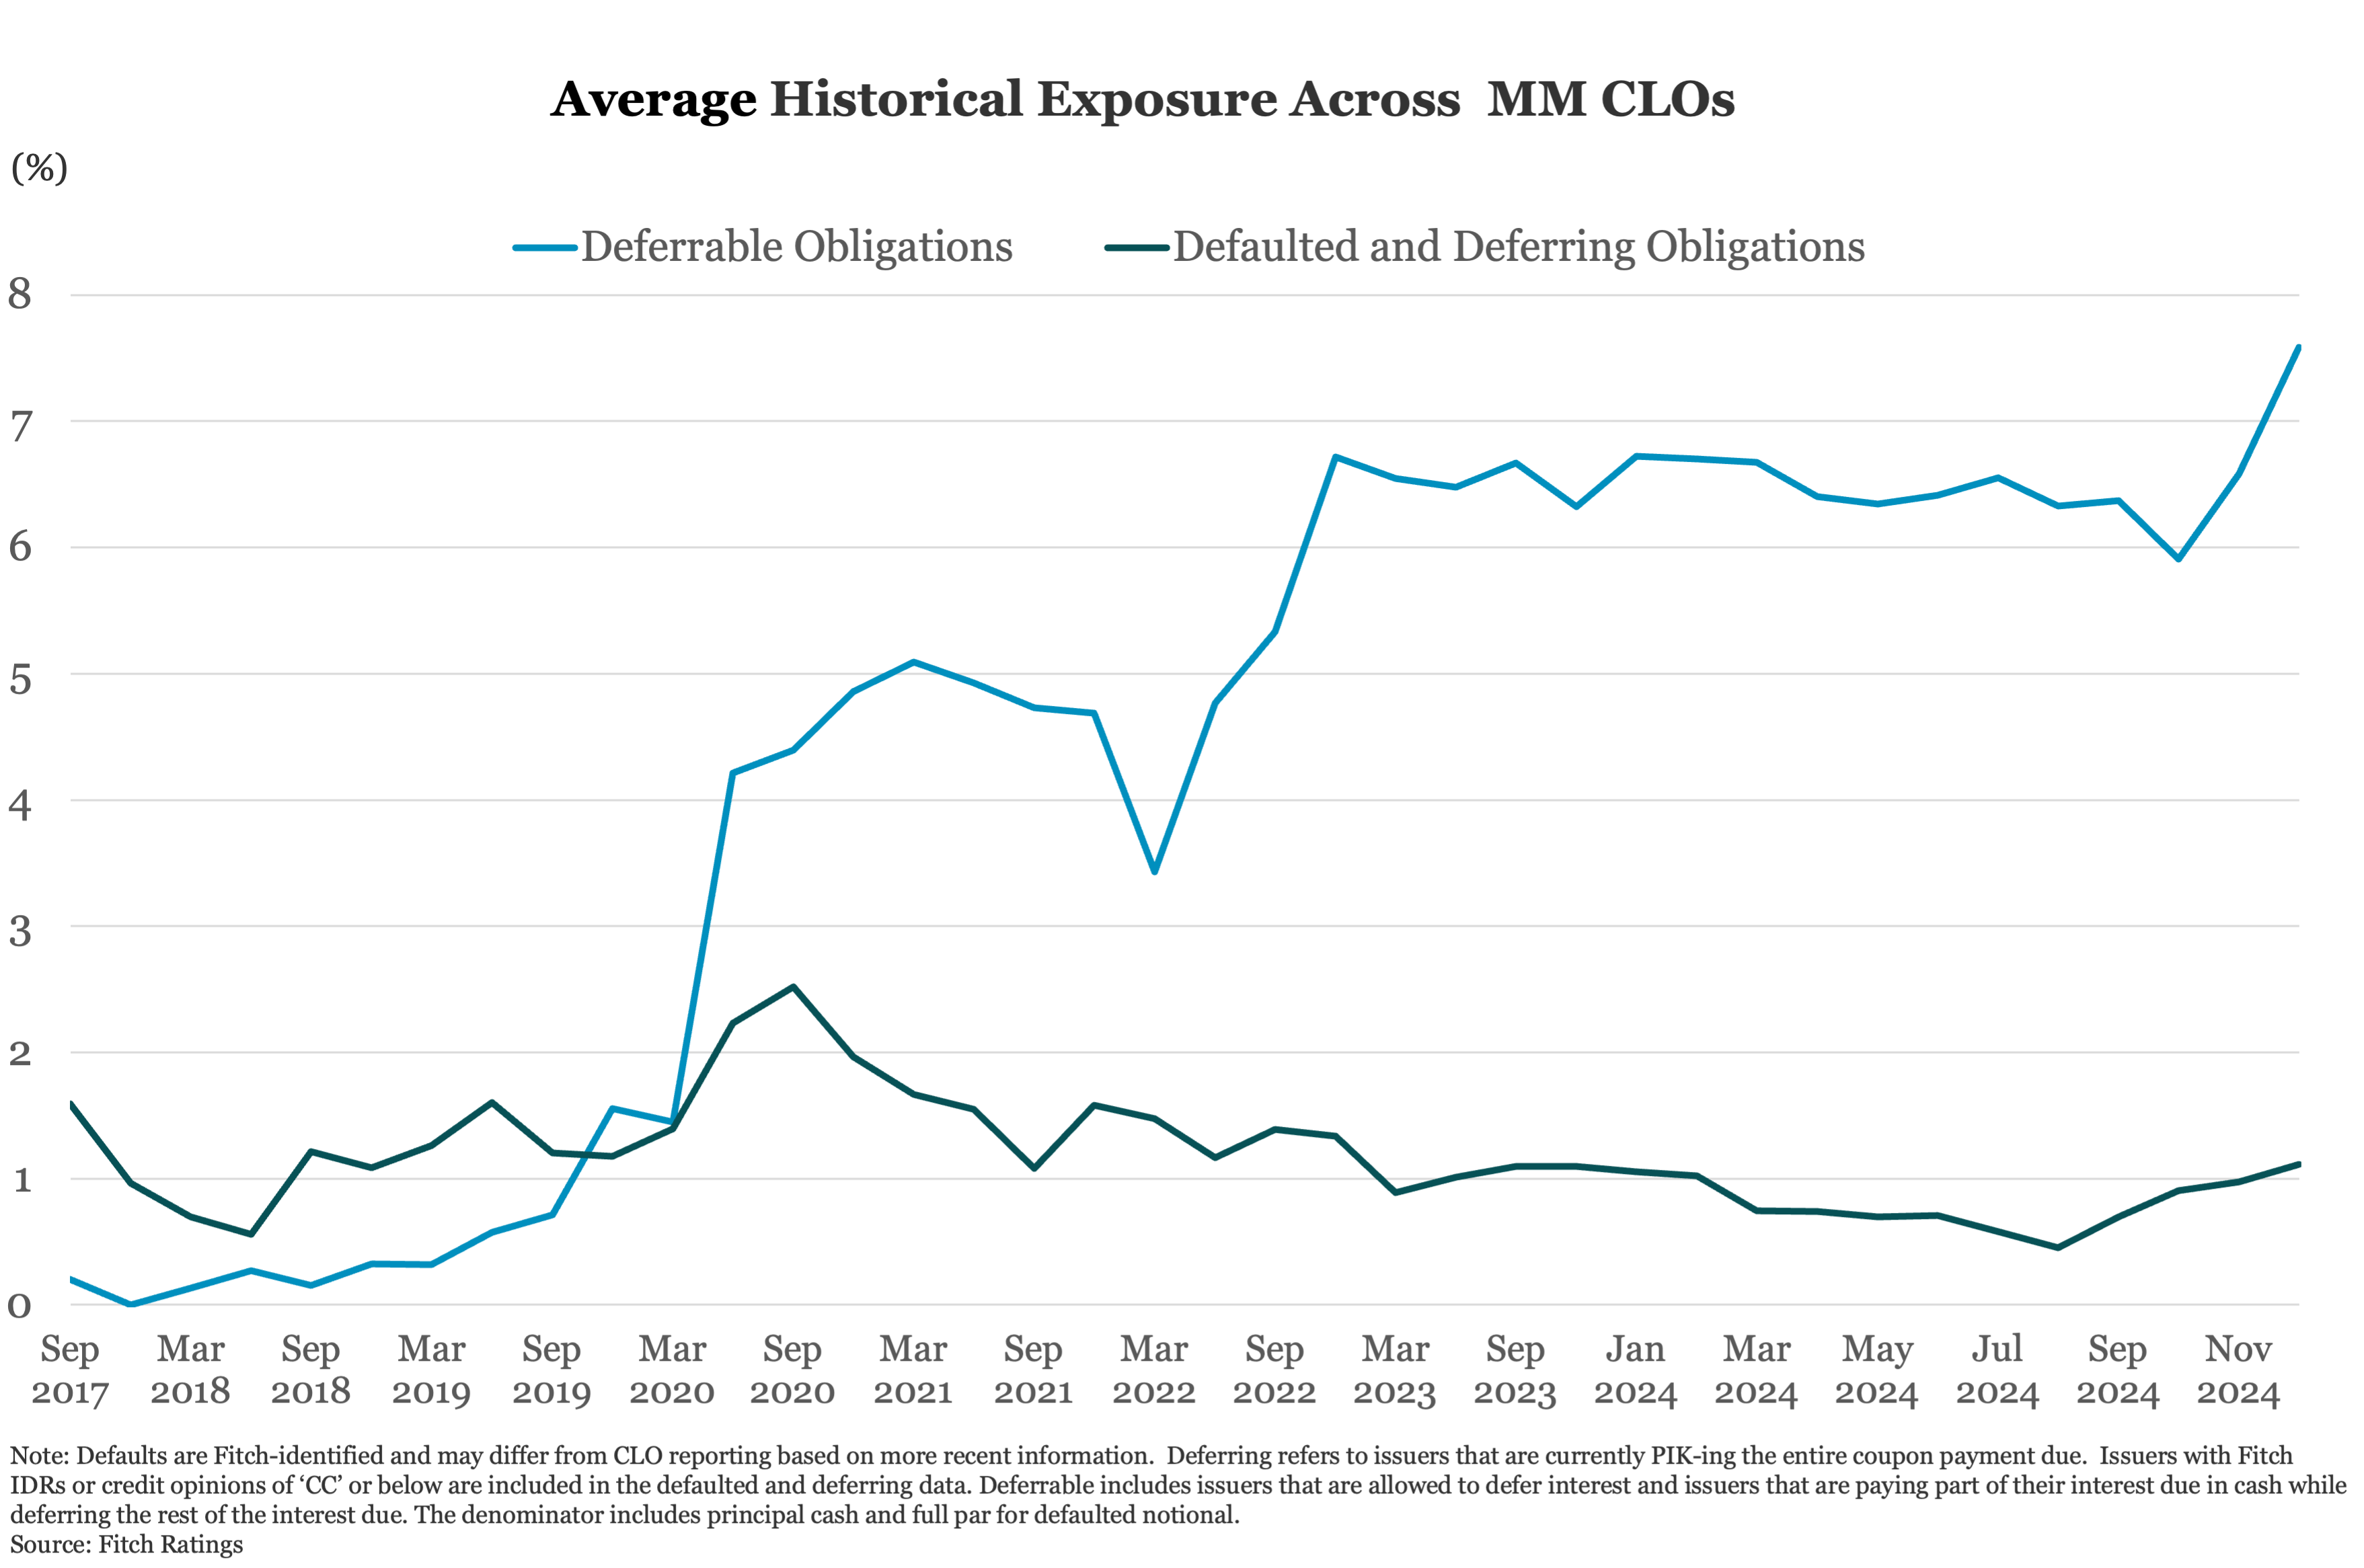
At the end of 2024, 24 CLOs had exposure to at least one defaulted or deferring issuer. The average exposure in middle market (MM) CLOs rose to 1.1%, up from 0.7% in the previous quarter, while remaining unchanged from the same period last year. In December, six new defaulted or deferring issuers were reported across eight MM CLOs, these issuers contributing to a combined exposure rate of 0.7% to 1.4% across these transactions. Additionally, one prior defaulted issuer emerged and another one was removed from the Fitch-rated CLOs in December.



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.