


Click here to learn more.
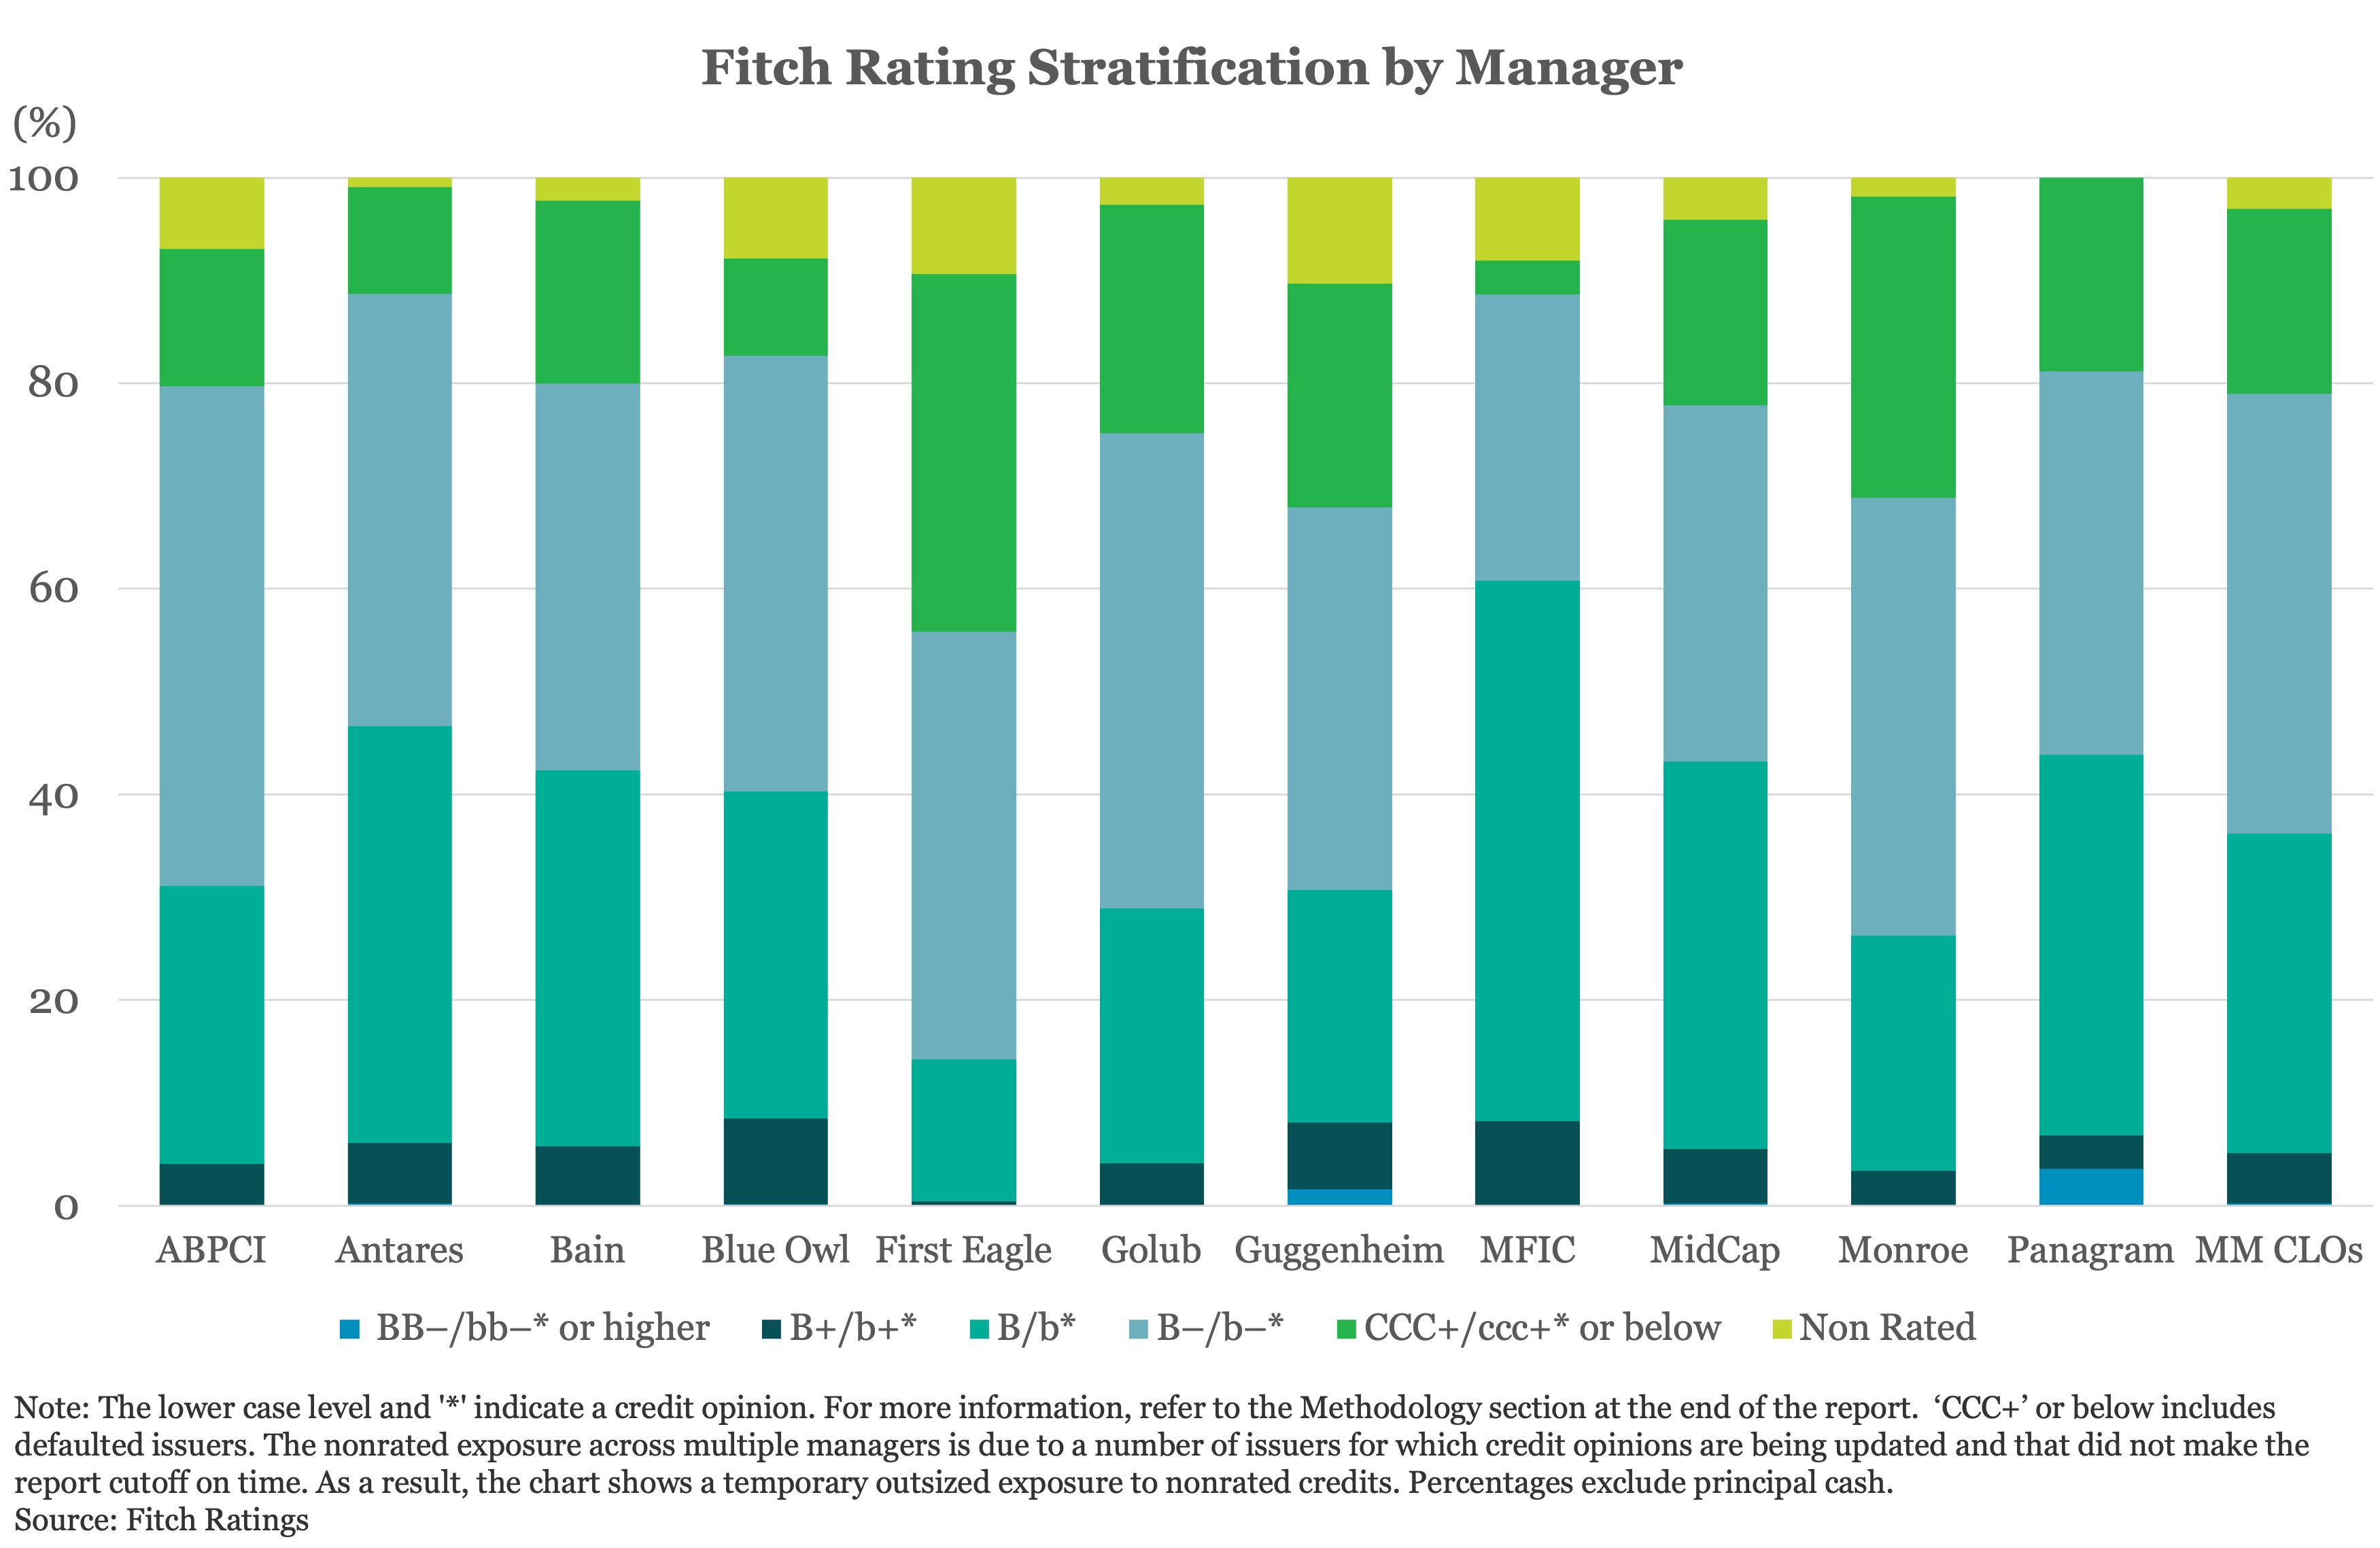
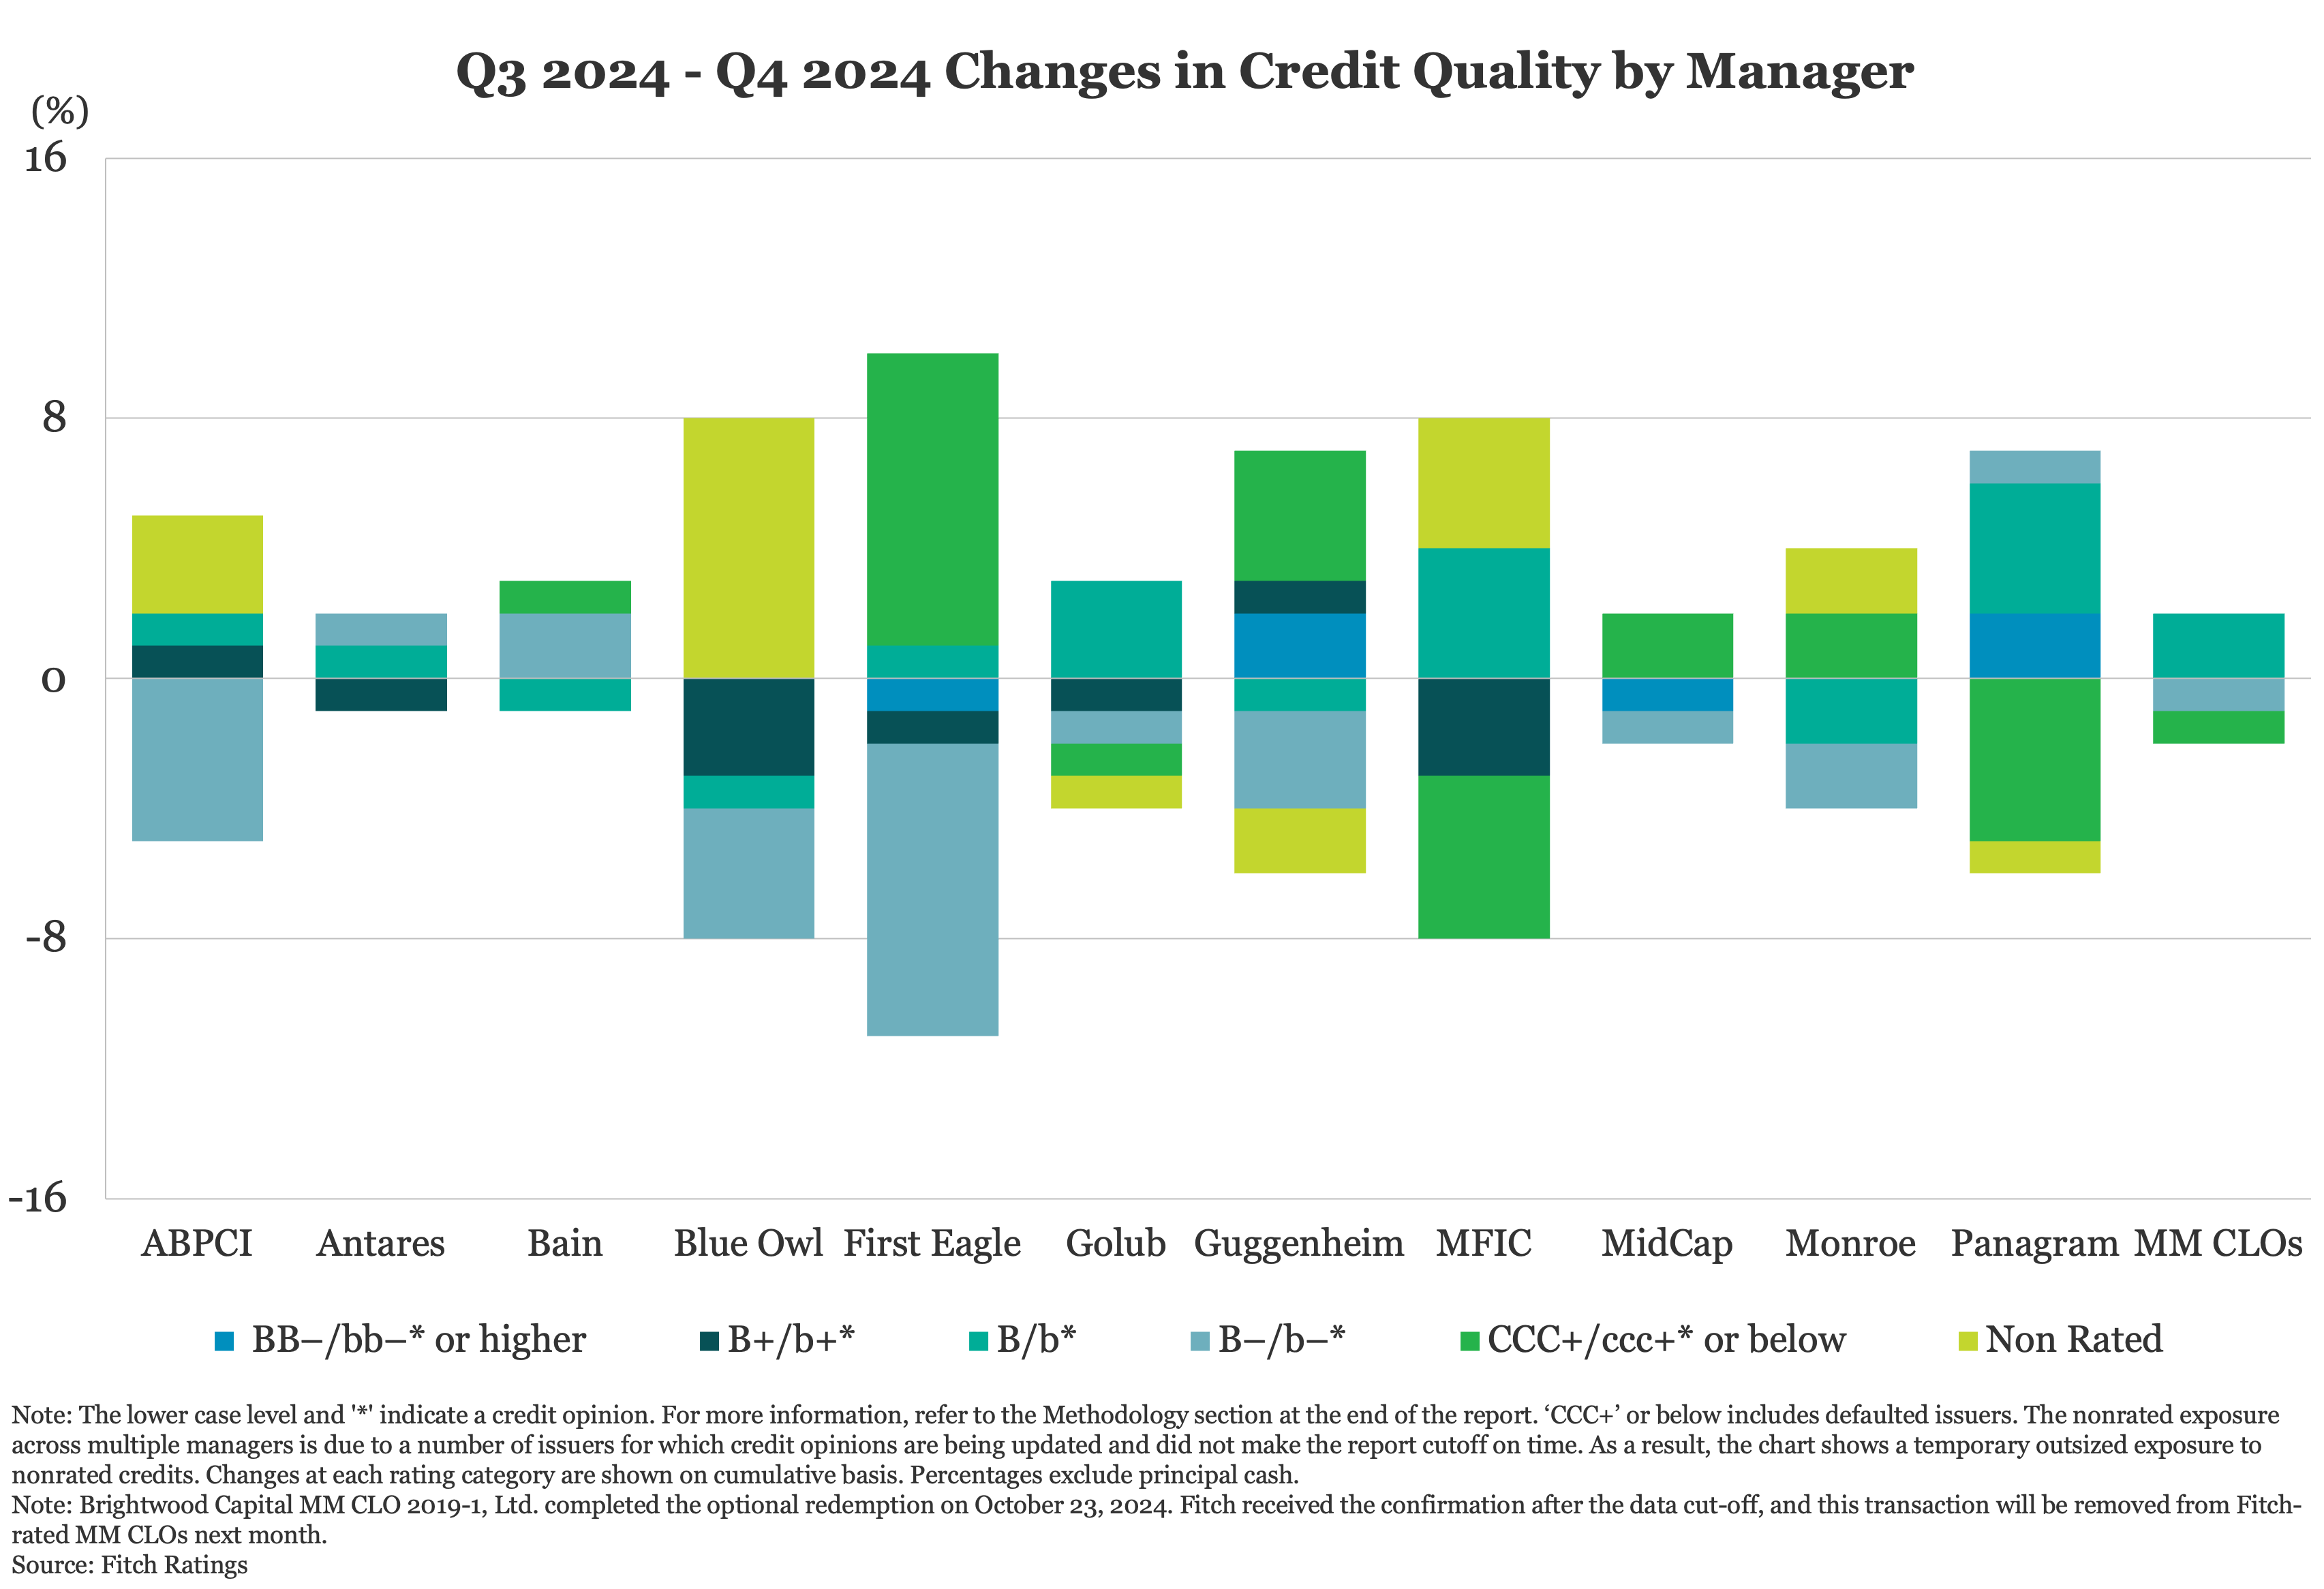
Exposure to assets with Fitch IDRs or credit opinions of ‘CCC+’ or below, excluding non-rated assets, has slightly decreased since last quarter and the same period last year, now standing at 18.5%, down from 19.3% last quarter and 18.9% last year. This slight reduction is primarily driven by the redemption of six Fitch-rated MM CLOs in the last quarter, which had a high ‘CCC’ exposure averaging 31.6%. Notably, all MM CLOs in reinvestment are currently passing the Fitch ‘CCC’ concentration limit test.



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.