


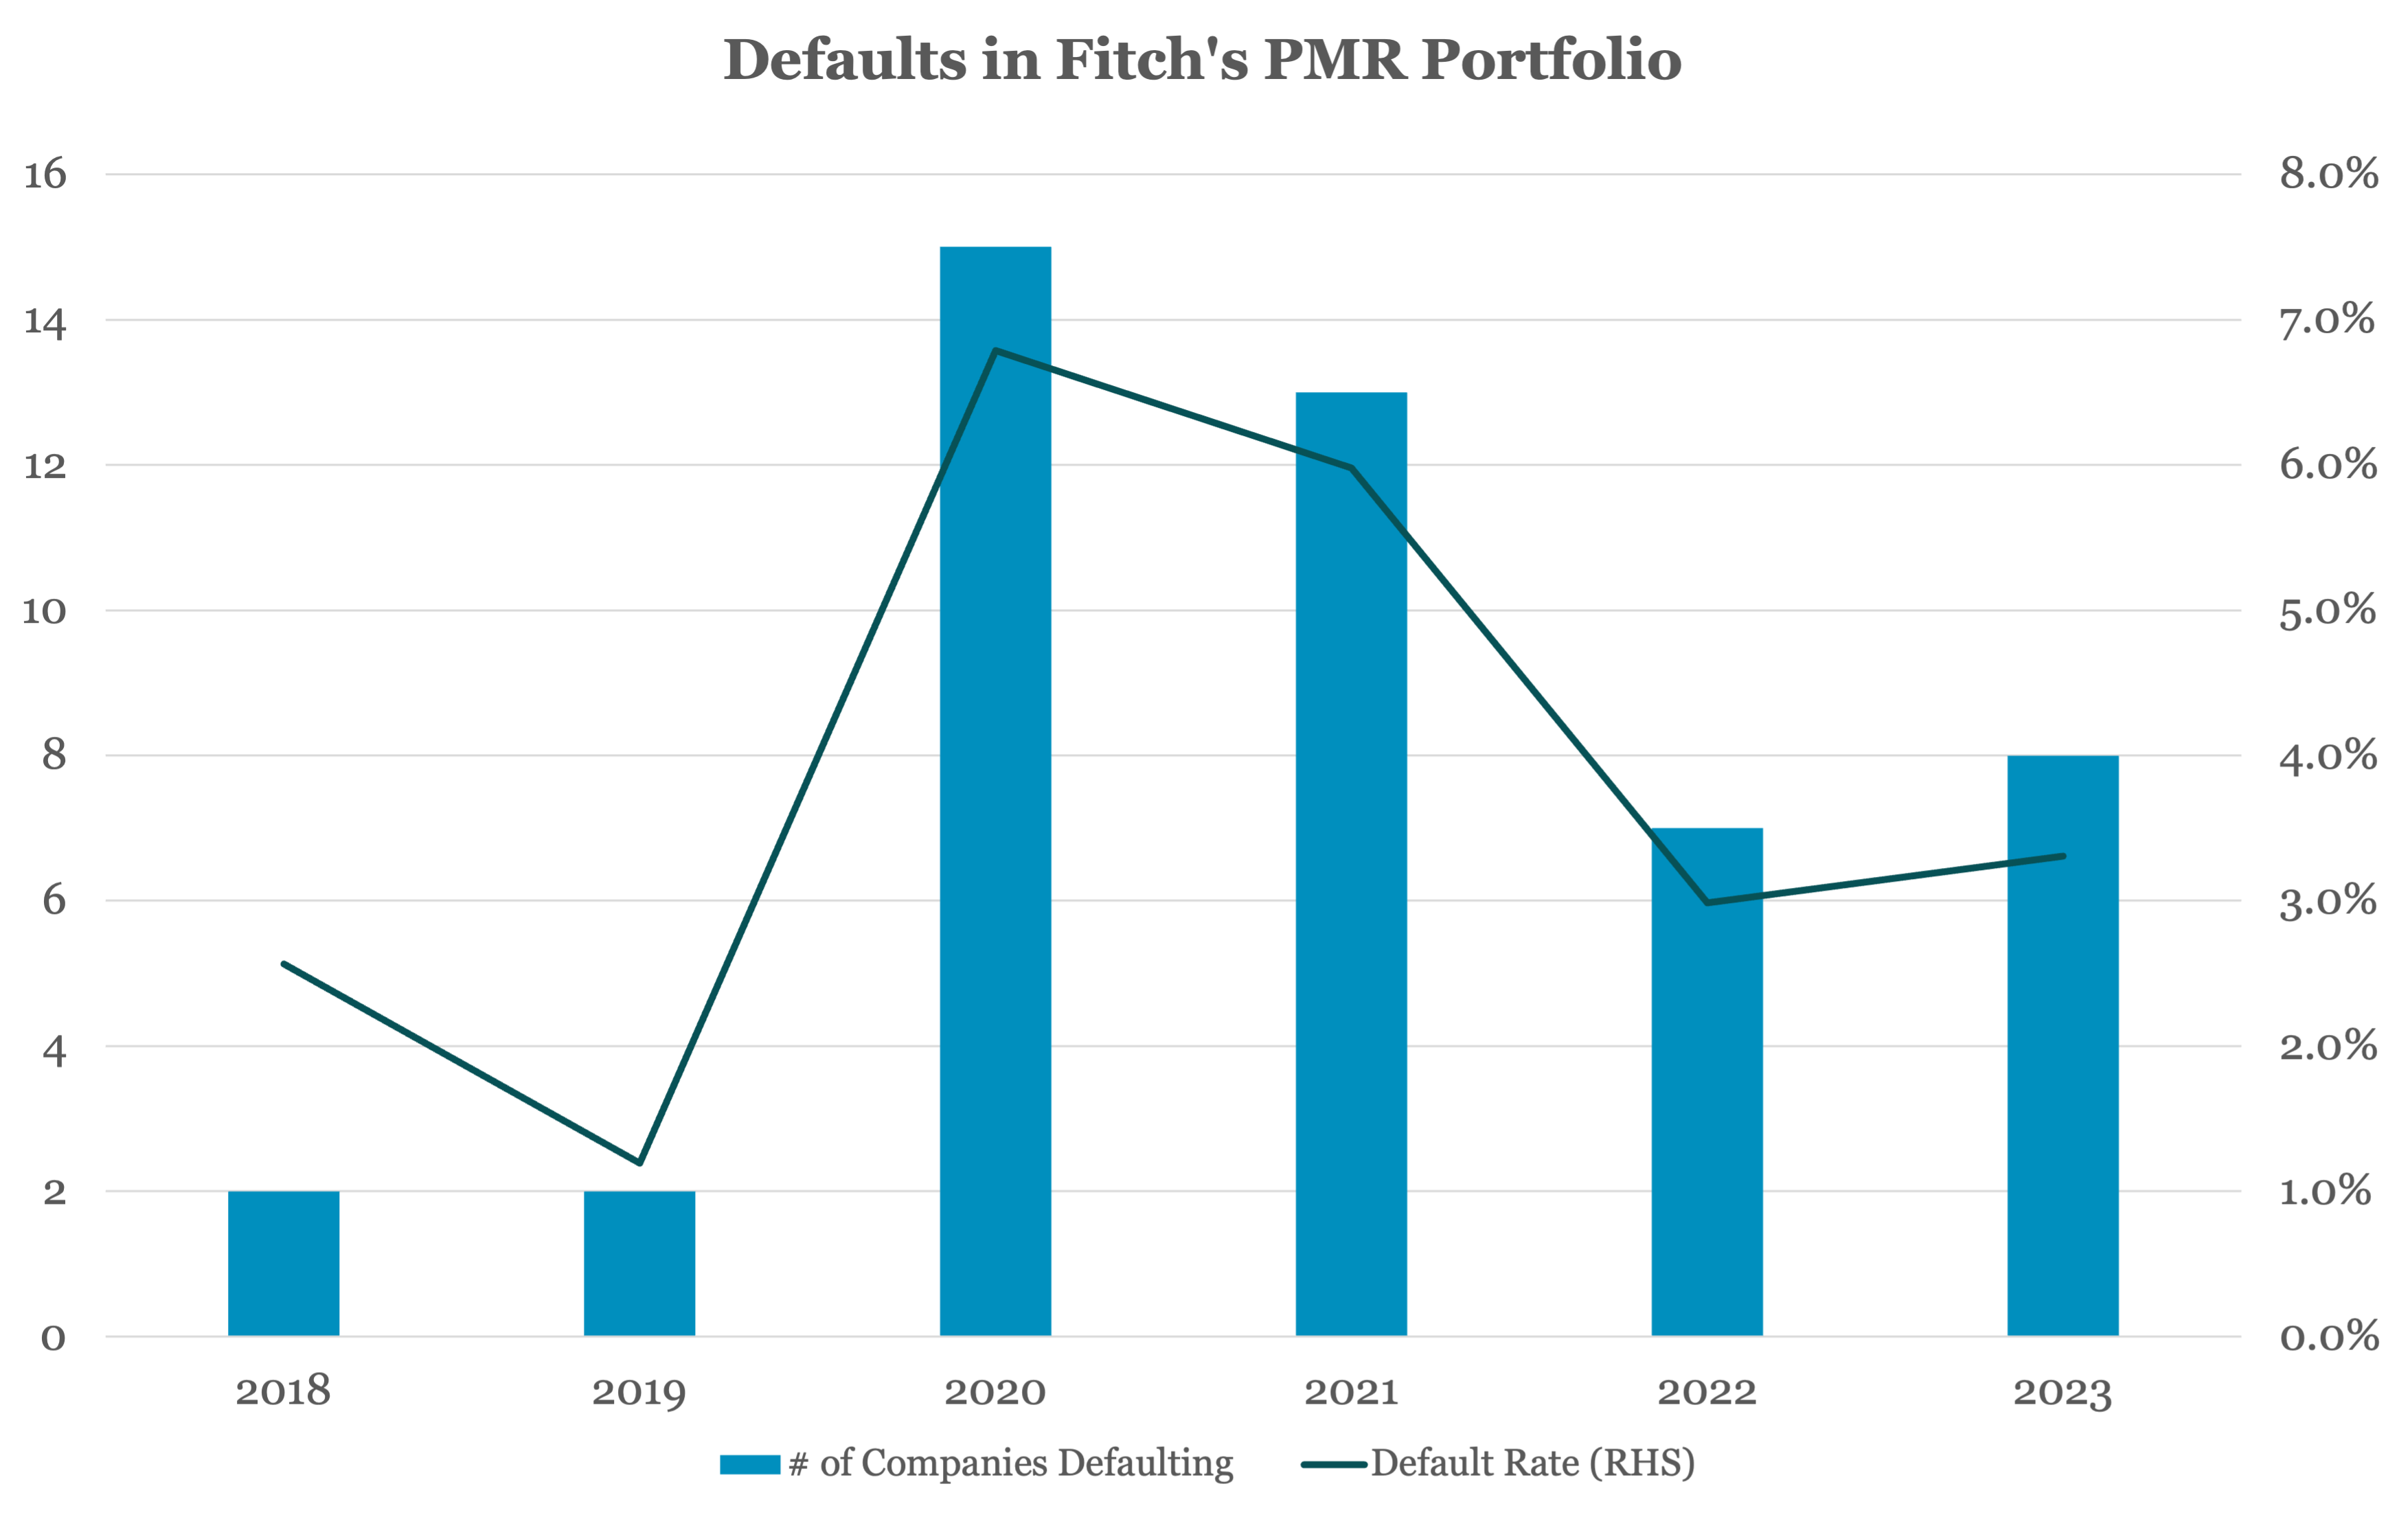
The default data is derived from Fitch’s portfolio of PMRs in the U.S. The ratings are largely of middle market sized companies of around $500 million of debt or less, or $100 million or less in EBITDA. These ratings are generally requested by asset managers that placed the loans with insurance companies requiring ratings for regulatory capital purposes. Fitch’s portfolio in the U.S. totals around 275 issuers, although the data draw from the ratings on more than 500 companies Fitch has rated in this portfolio since 2017. Since the portfolio reached a critical mass of more than 100 ratings in 2018, Fitch has recorded a total of 57 defaults across 37 unique issuers.
(Past performance is no guarantee of future results.)
Contact: Brad Hamner
brad.hamner@fitchratings.com



Latest news

With inflation running hot, rate hike expectations strengthen
A hotter-than-expected inflation reading has renewed expectations for near-term Federal Reserve tightening. The Consumer Price Index rose 0.6% month-over-month, pushing…

Open Tab
Leveraged loans keep running up a tab. Senior direct lending already knows what it owes.
