


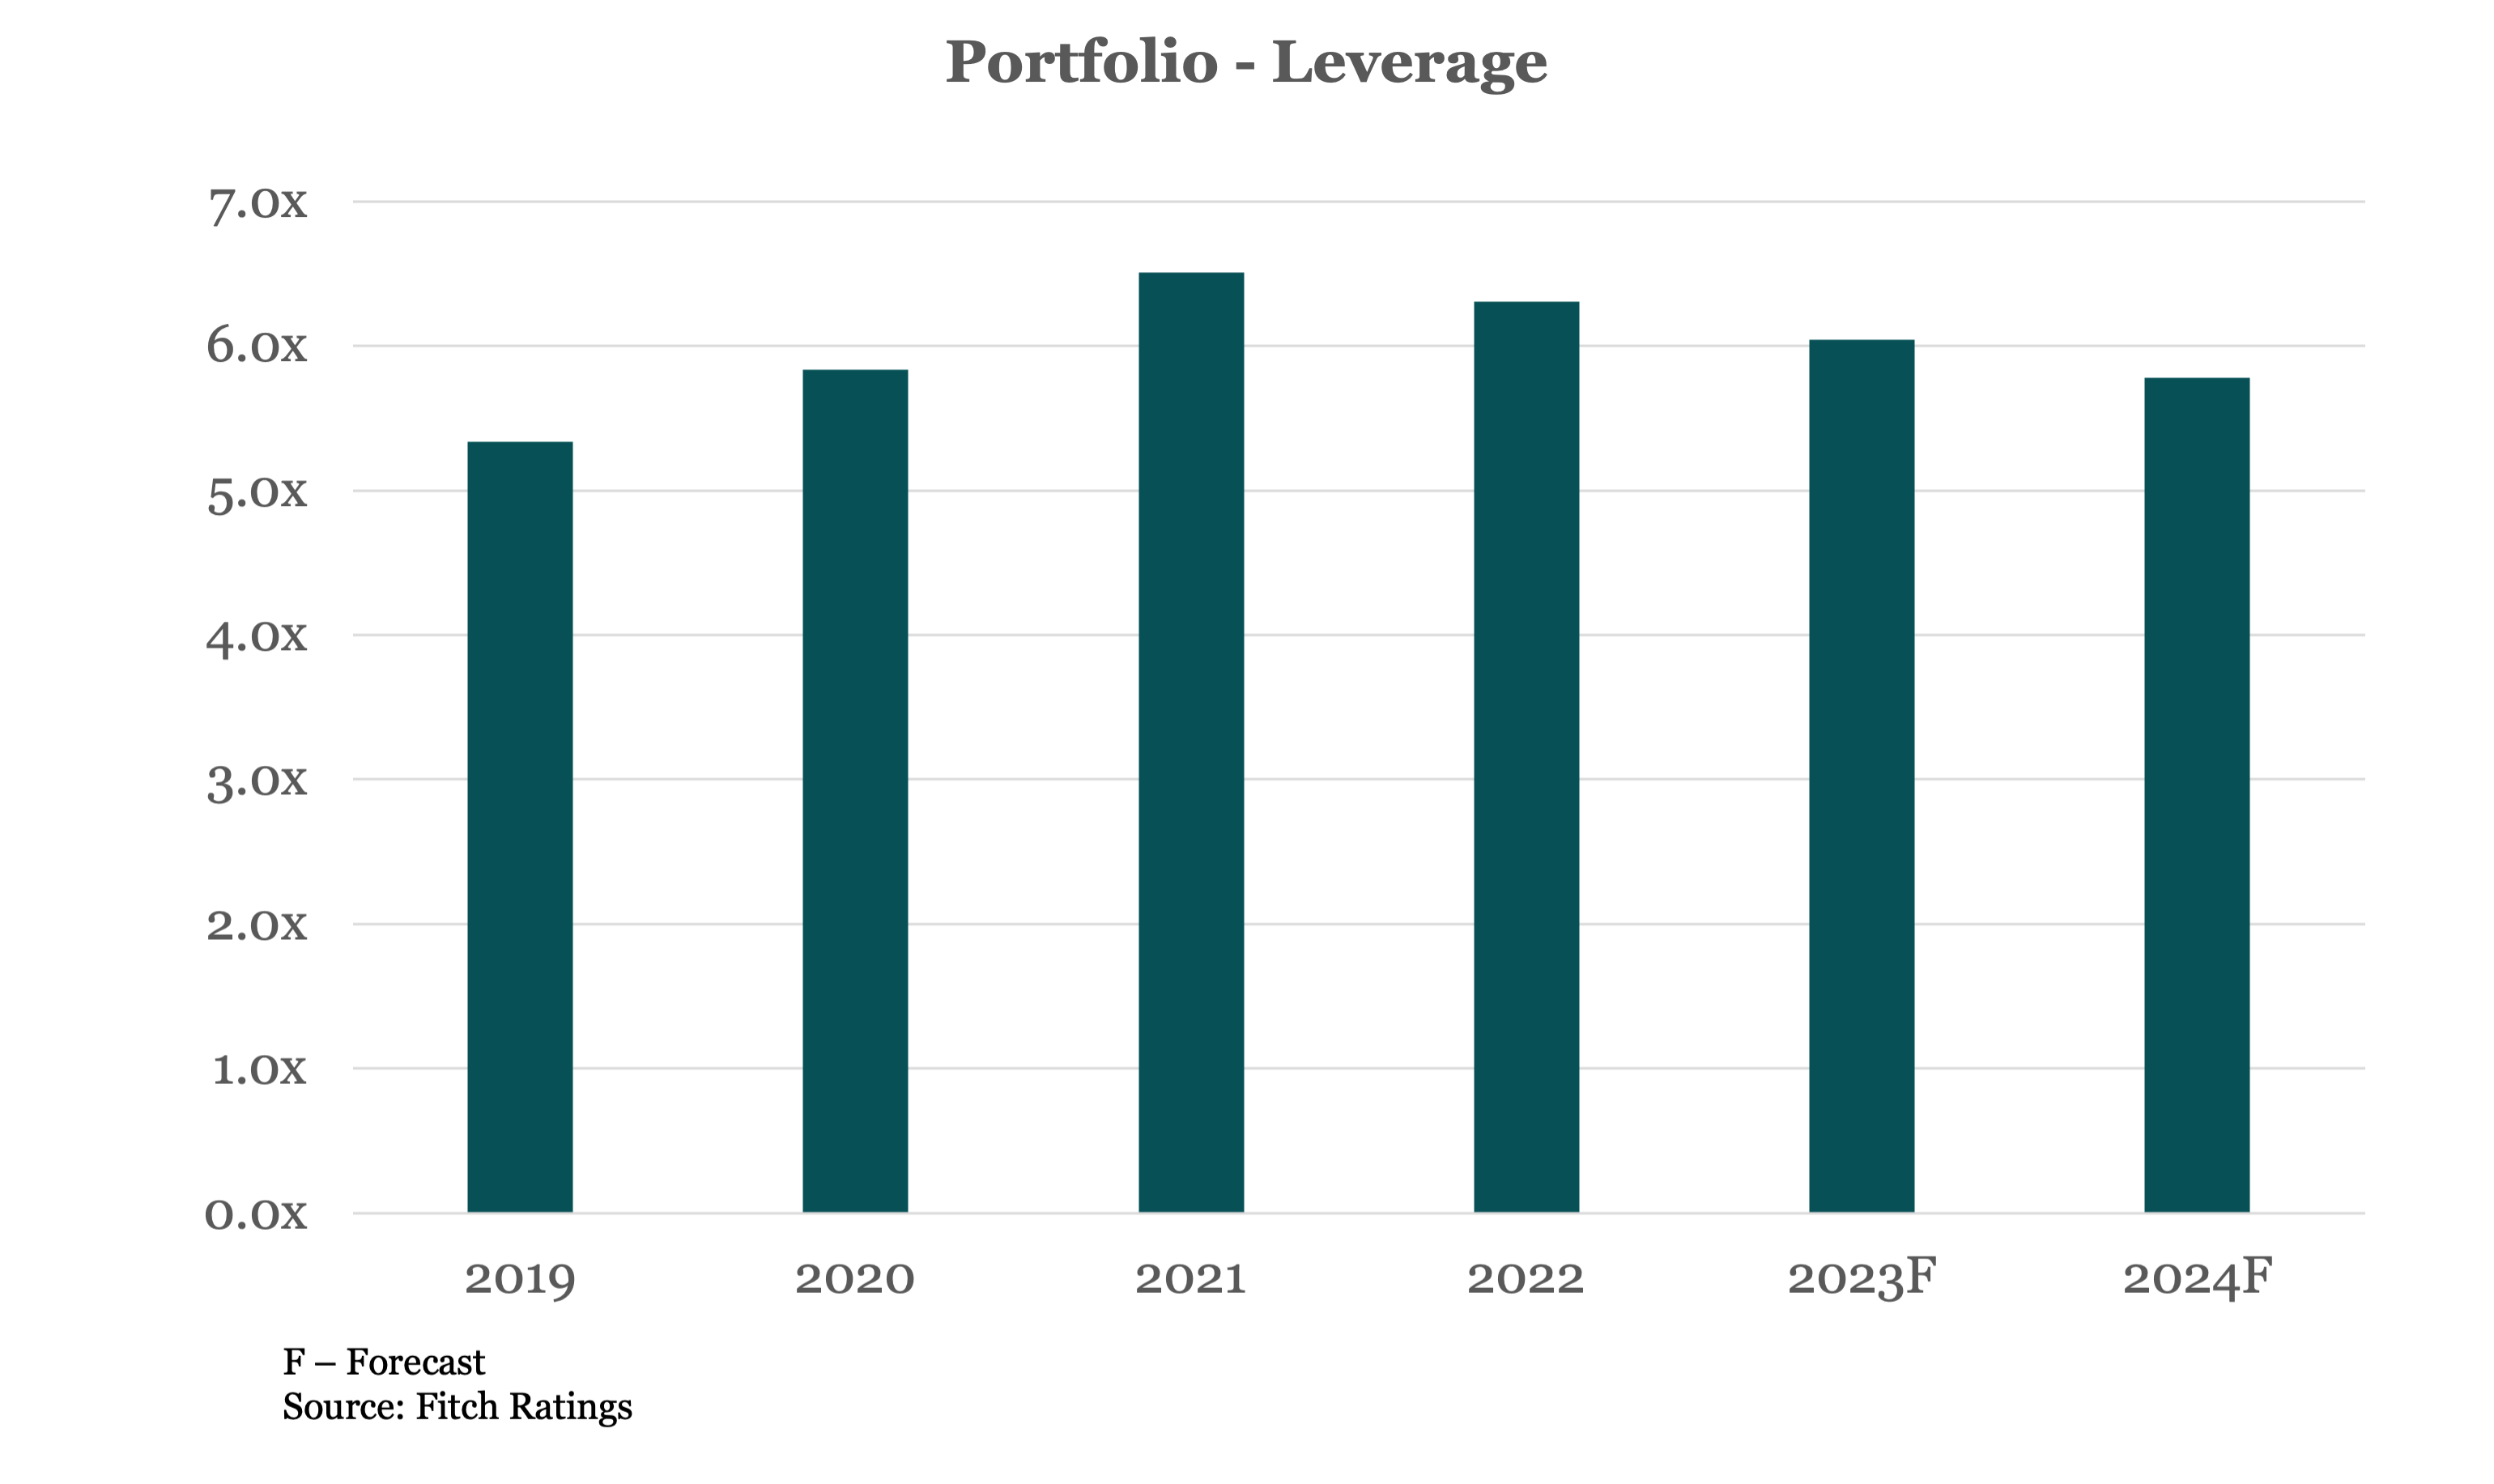
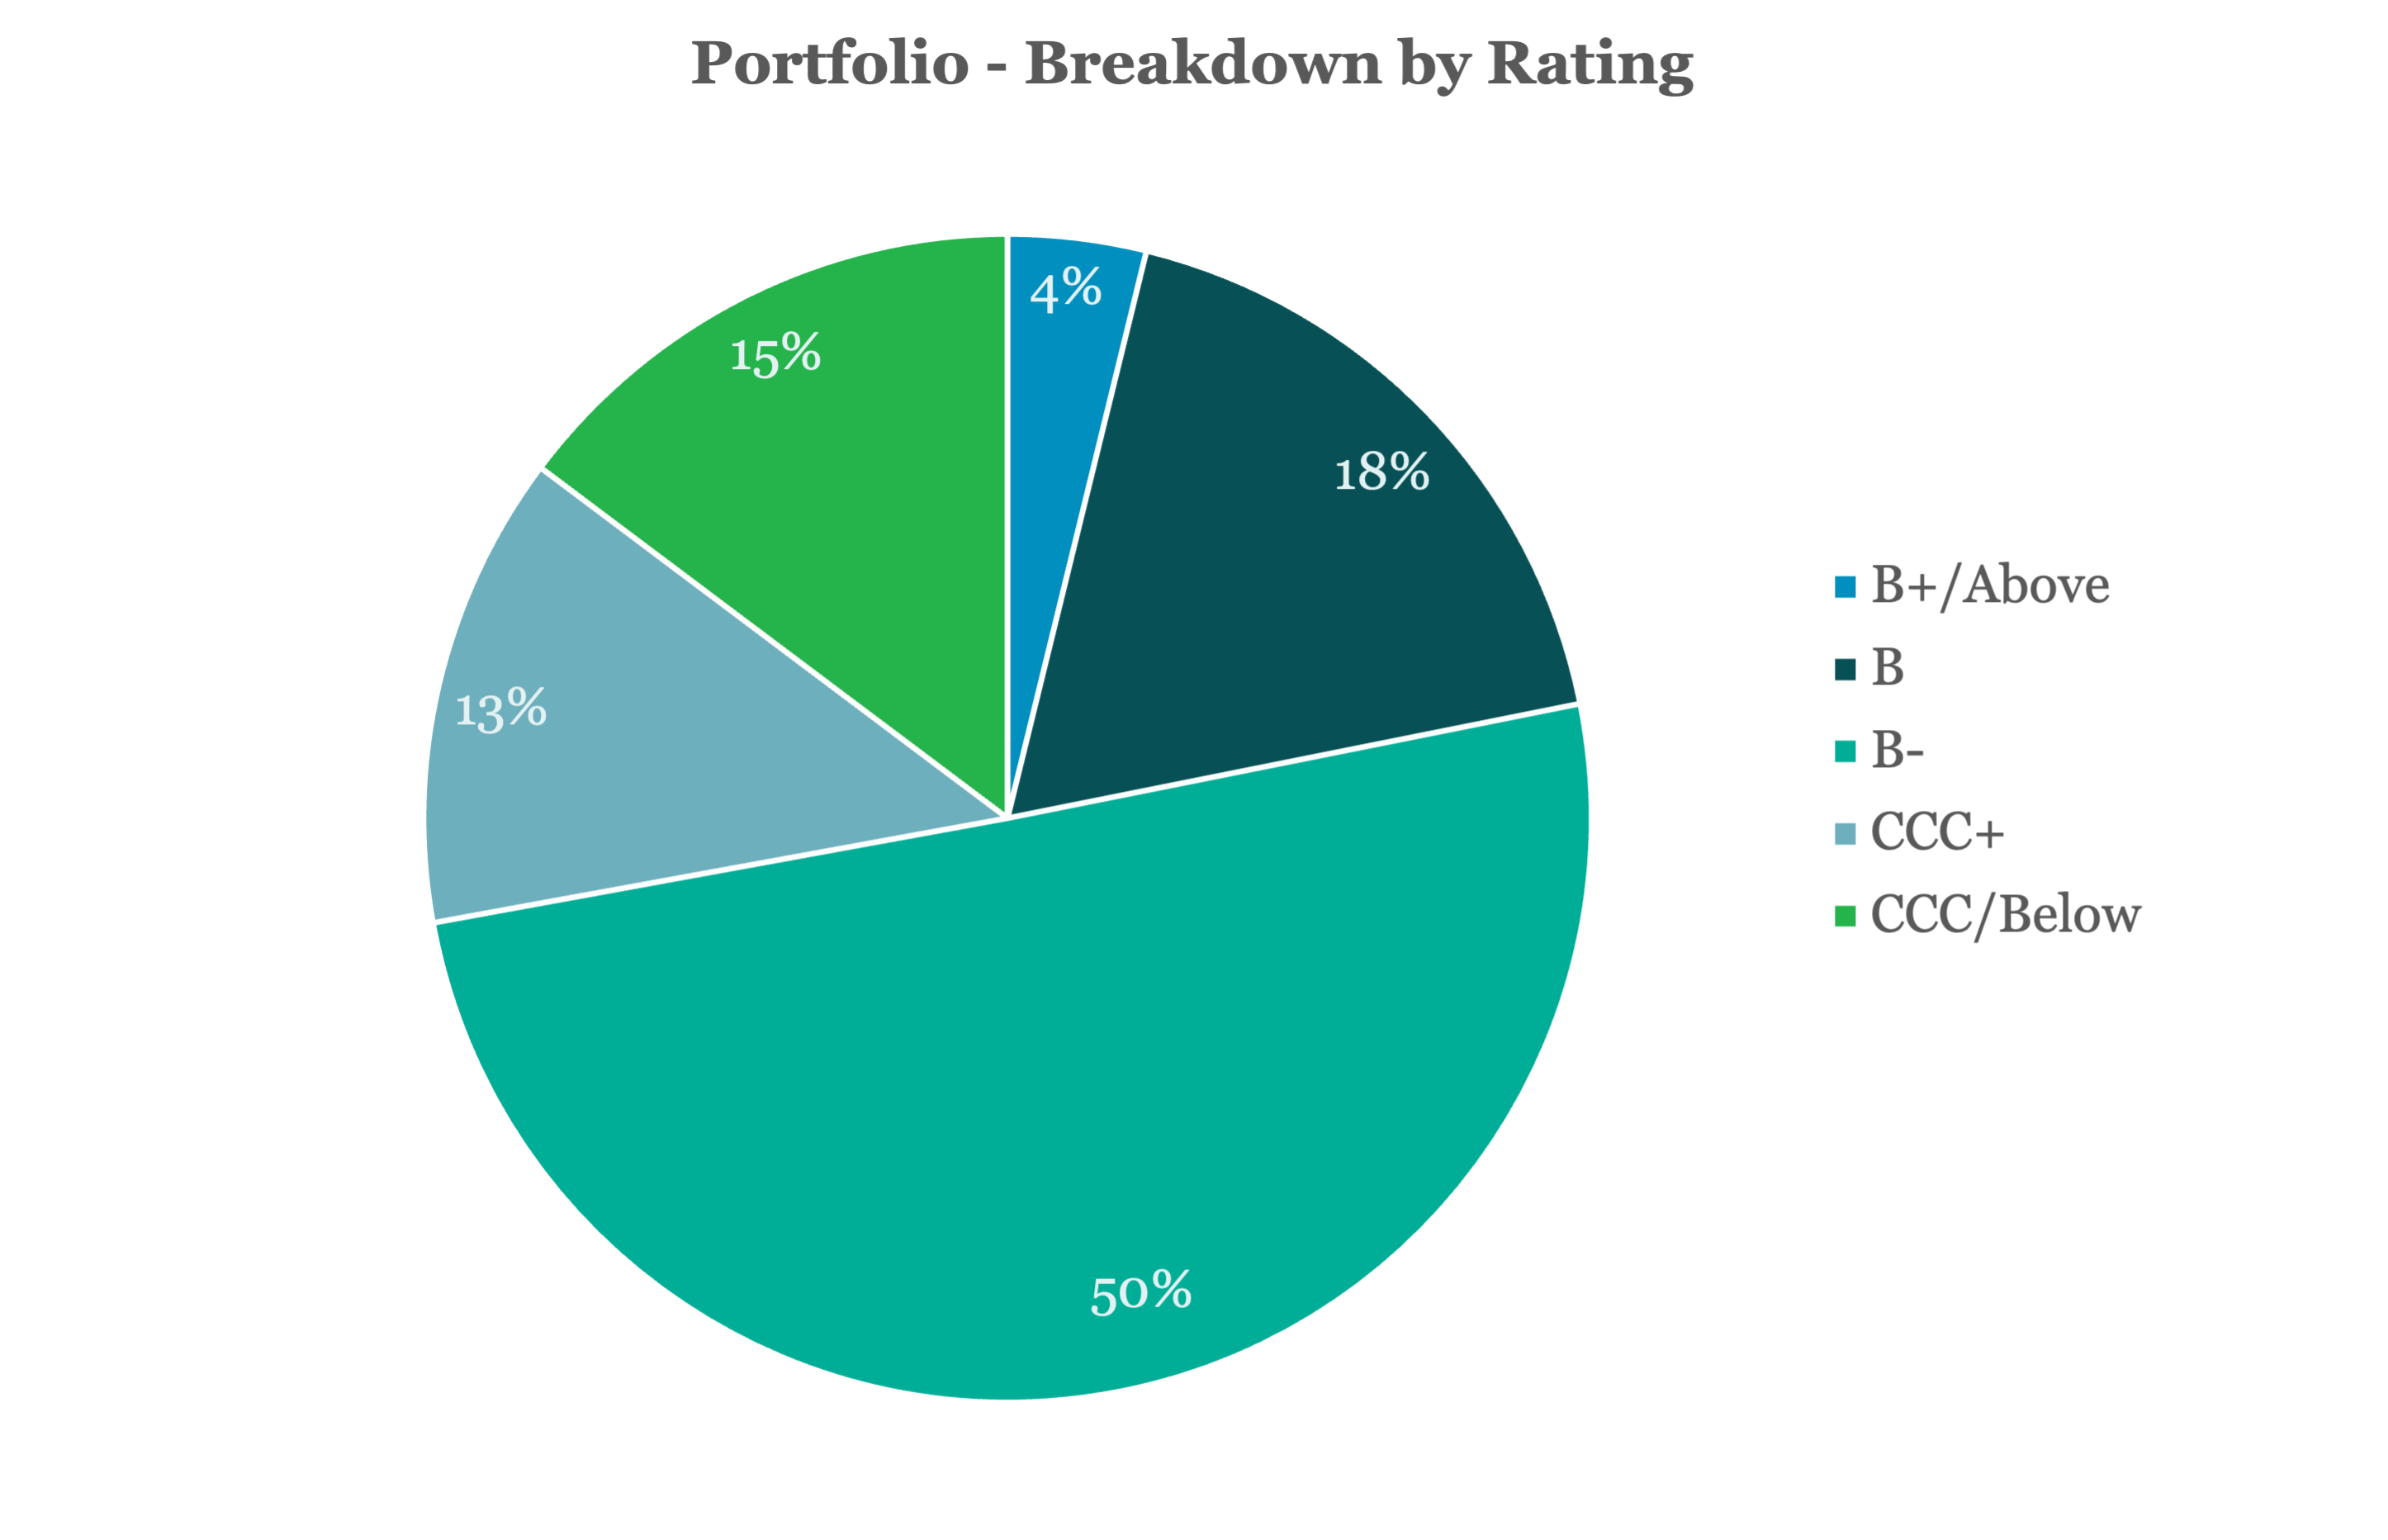
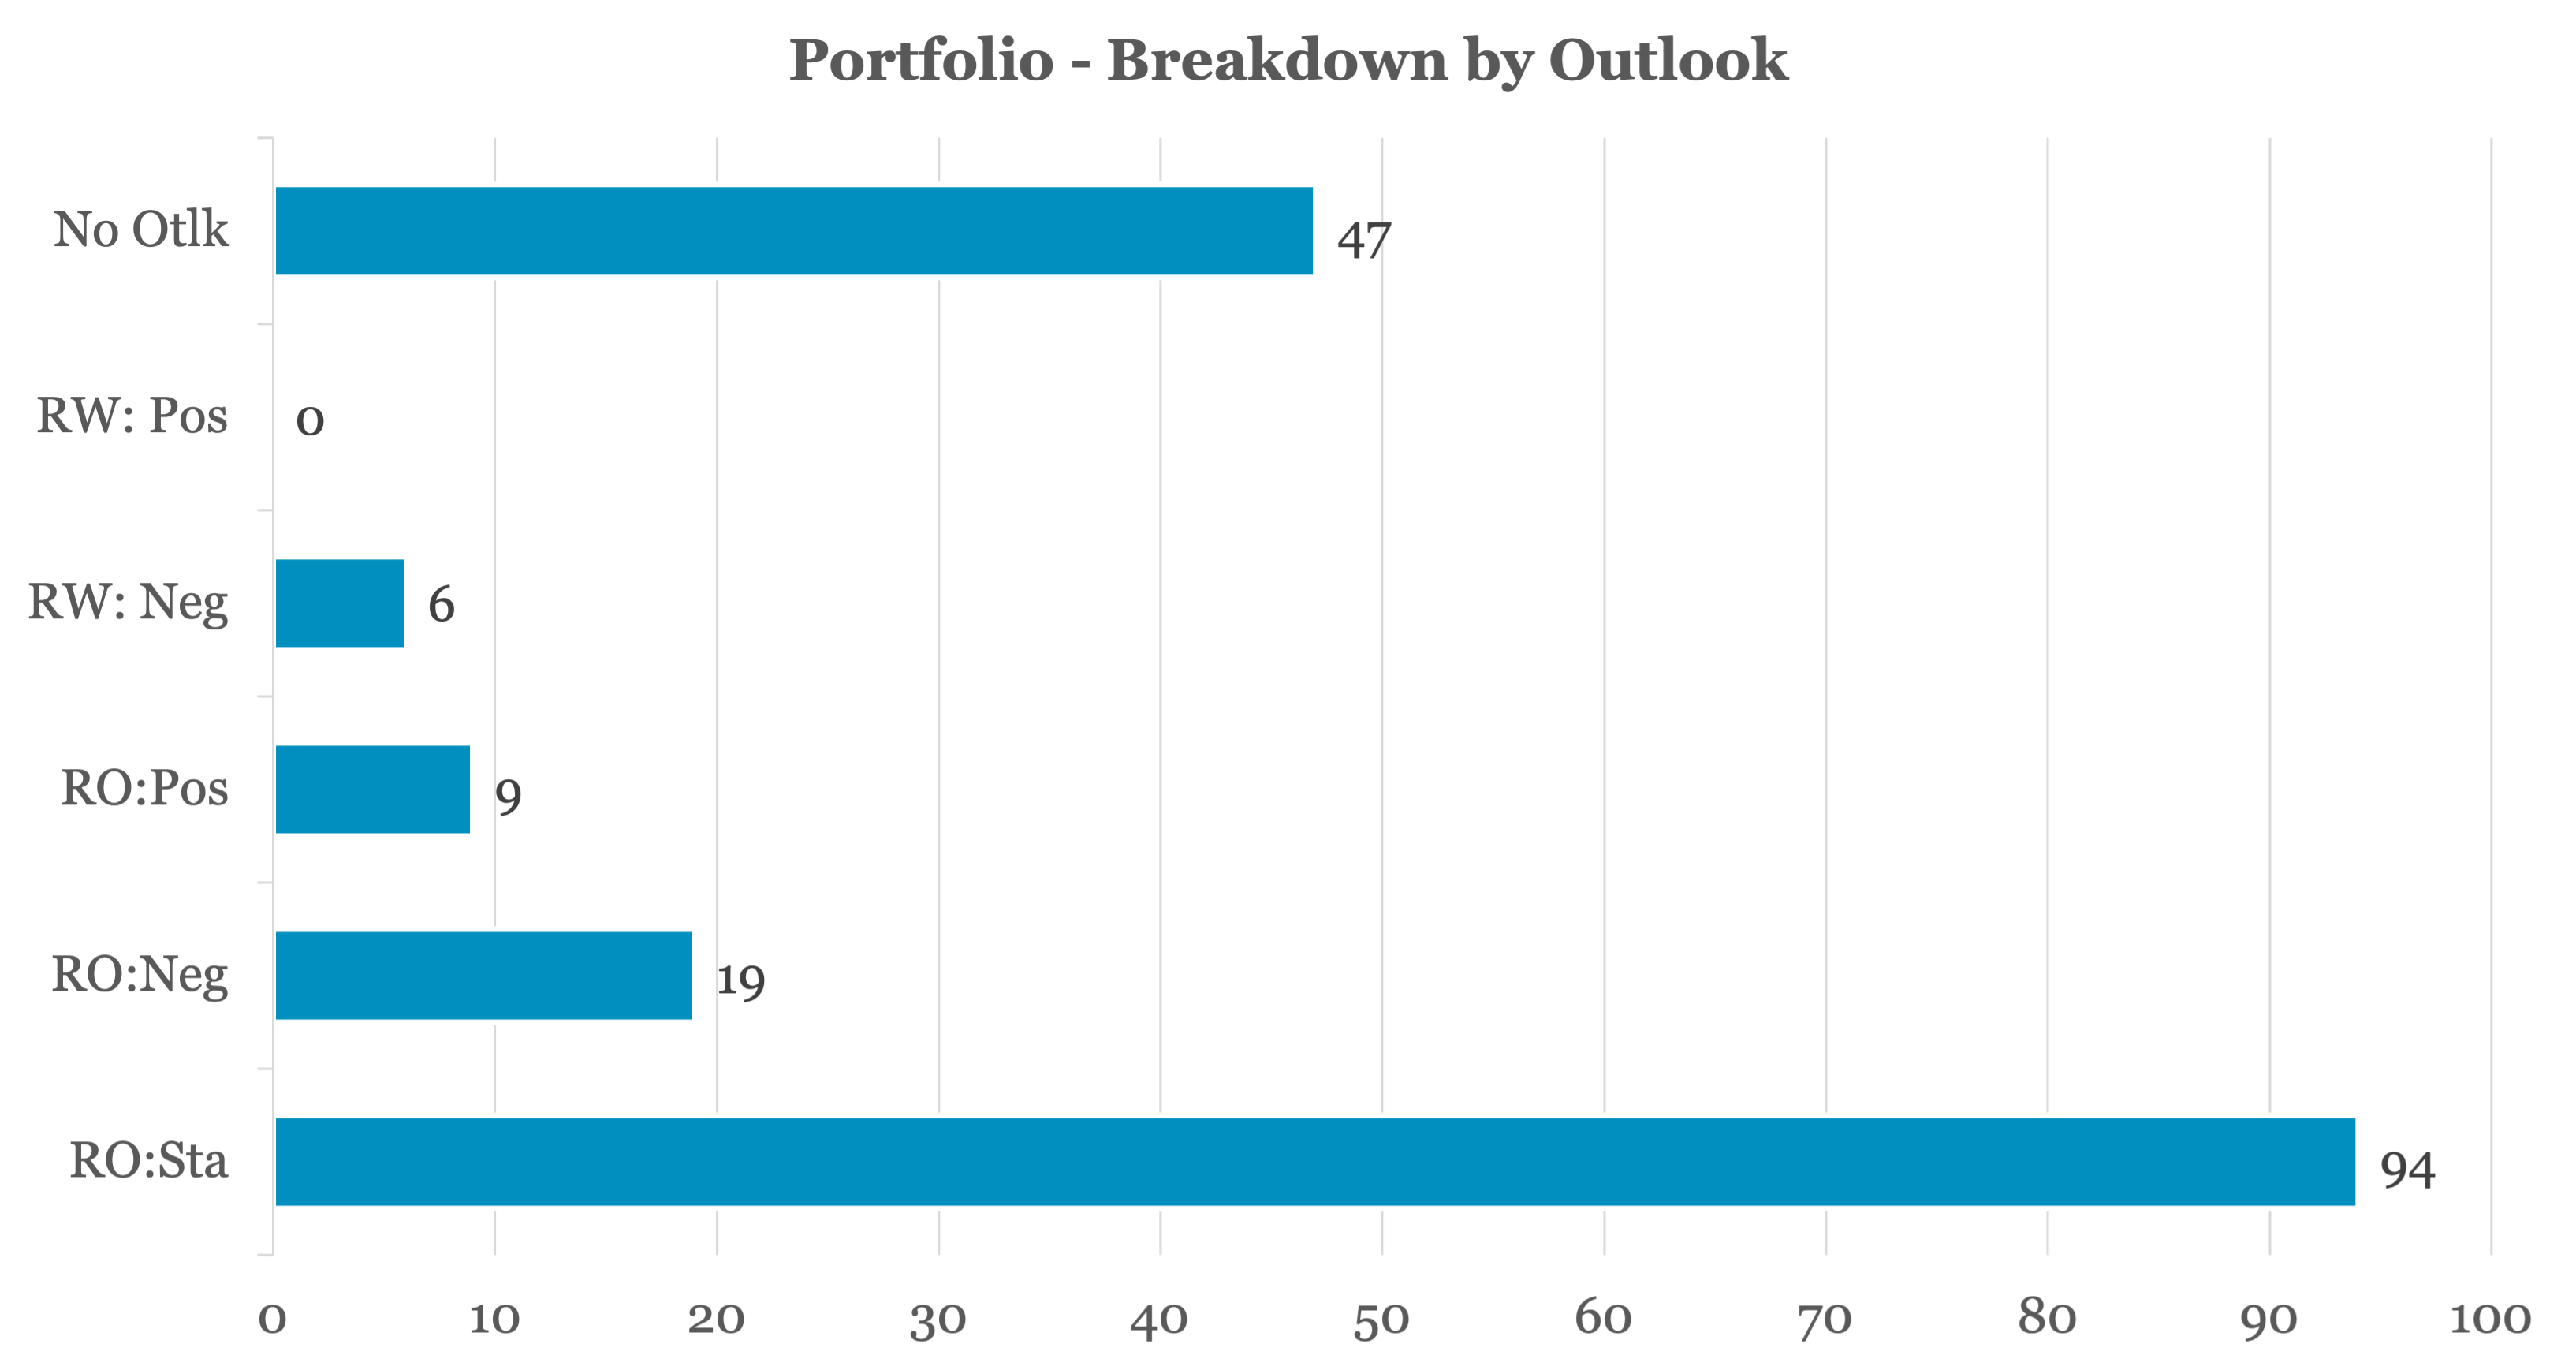
In the charts above, Fitch presents aggregate data for MM companies, defined as in the area of $500 million of debt or $100 million of EBITDA or below, that it privately rates for asset managers.
- Fitch estimates median EBITDA leverage of 6.0x for 2023 and expects the deleveraging trend to continue in 2024 to 5.8x. EBITDA leverage rose to 6.5x in 2021 from 5.3x in 2019 as issuers grappled with stresses from the pandemic and the aftermath effects, including inflationary input costs, supply chain and labor issuers, as well as higher-for-longer interest rates. However, issuers in Fitch’s PMM portfolio as a whole successfully navigated these issues in 2022 and 2023, and entered 2024 better prepared to take advantage of an arguably normalizing environment. The decrease in 2023 EBITDA leverage was led by Food, Beverage & Tobacco, with a 2x turn decrease to 6.5x, driven particularly by EBITDA strongly rebounding for issuers in the Food sub-sector. Given considerably smaller scale and low negotiating power when compared to both their suppliers and customers, these issuers initially struggled to contain input costs and navigate supply chain challenges. The Healthcare and Diversified Services sectors also contributed to the overall portfolio’s EBITDA leverage decline in 2023, experiencing reductions of 1.2x and 1.1x yoy to 6.6x and 6.2x, respectively.
(Past performance is no guarantee of future results.)
Contact Brad Hamner



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
September 17, 2026
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
September 17, 2026
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
September 16, 2026
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…