


US Private Credit Defaults Rose Sharply in 2024 While Lender Losses Remained Limited
Click here to learn more.
Join Fitch Rating upcoming Webinar: The Highs and Lows of Private Credit Defaults and Recoveries
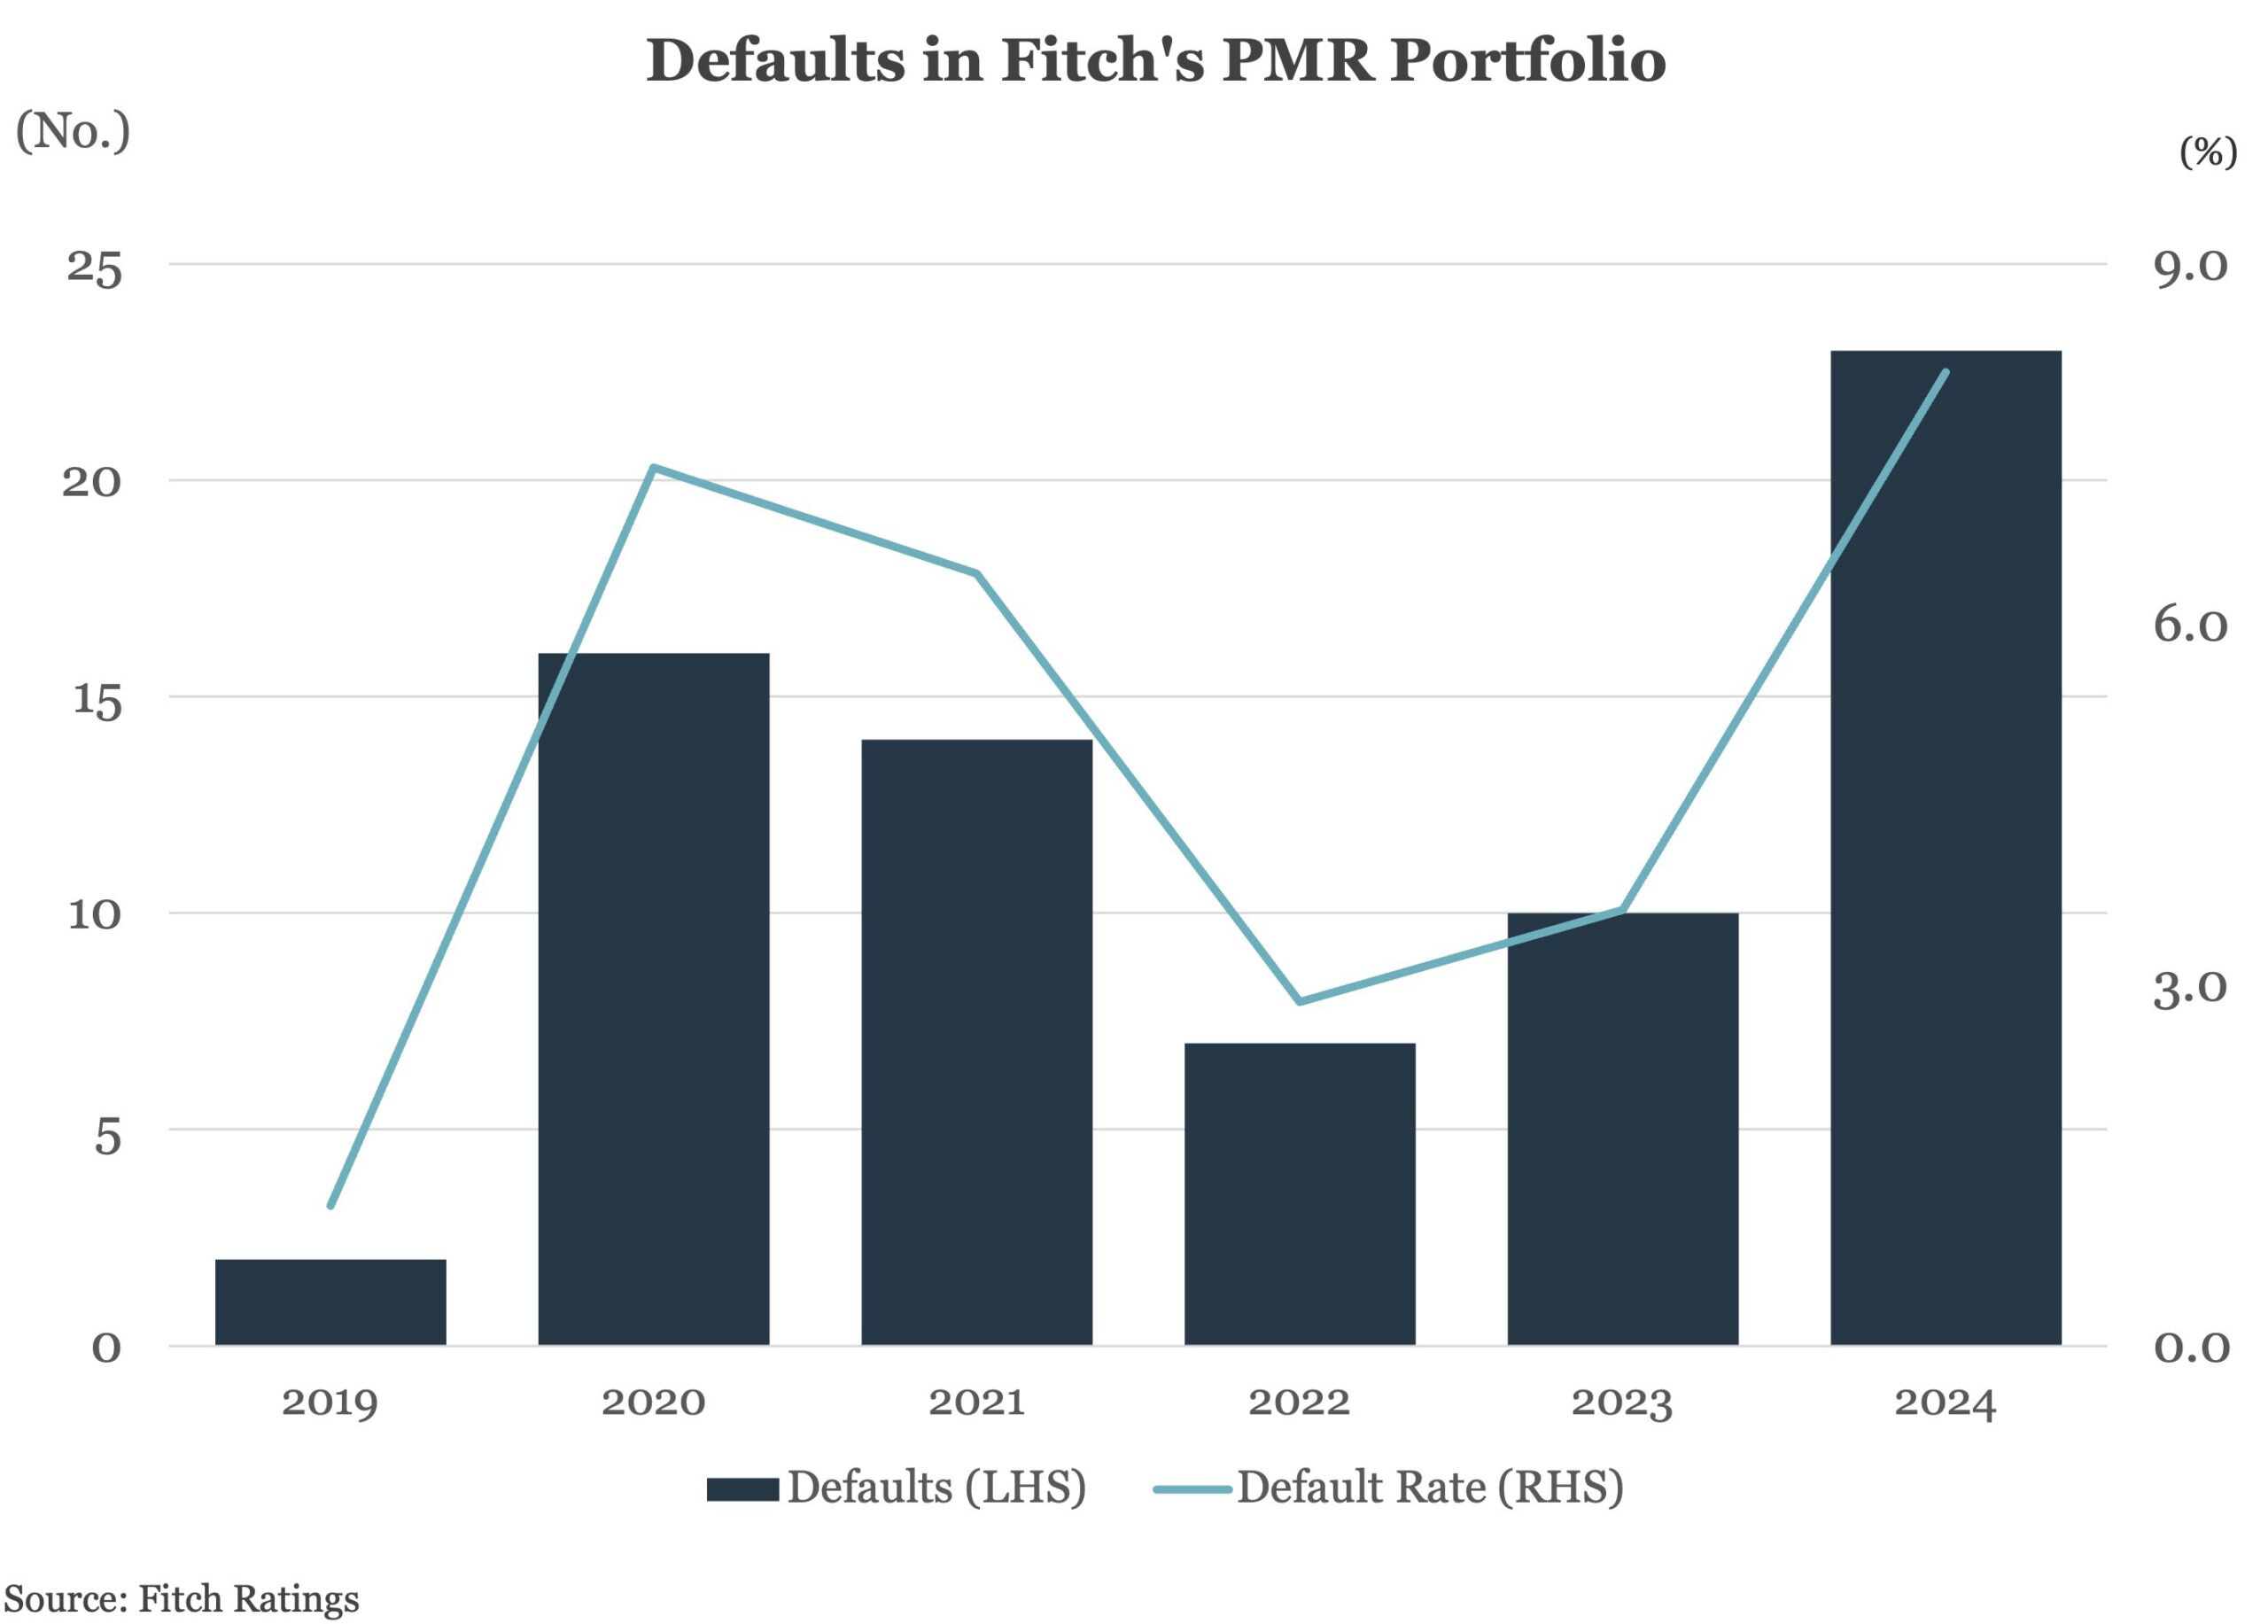
The default rate in Fitch Ratings’ portfolio of U.S. privately monitored ratings (PMR) rose sharply to 8.1% in 2024. This is the highest level since Fitch recorded the first default in the portfolio in 2019.
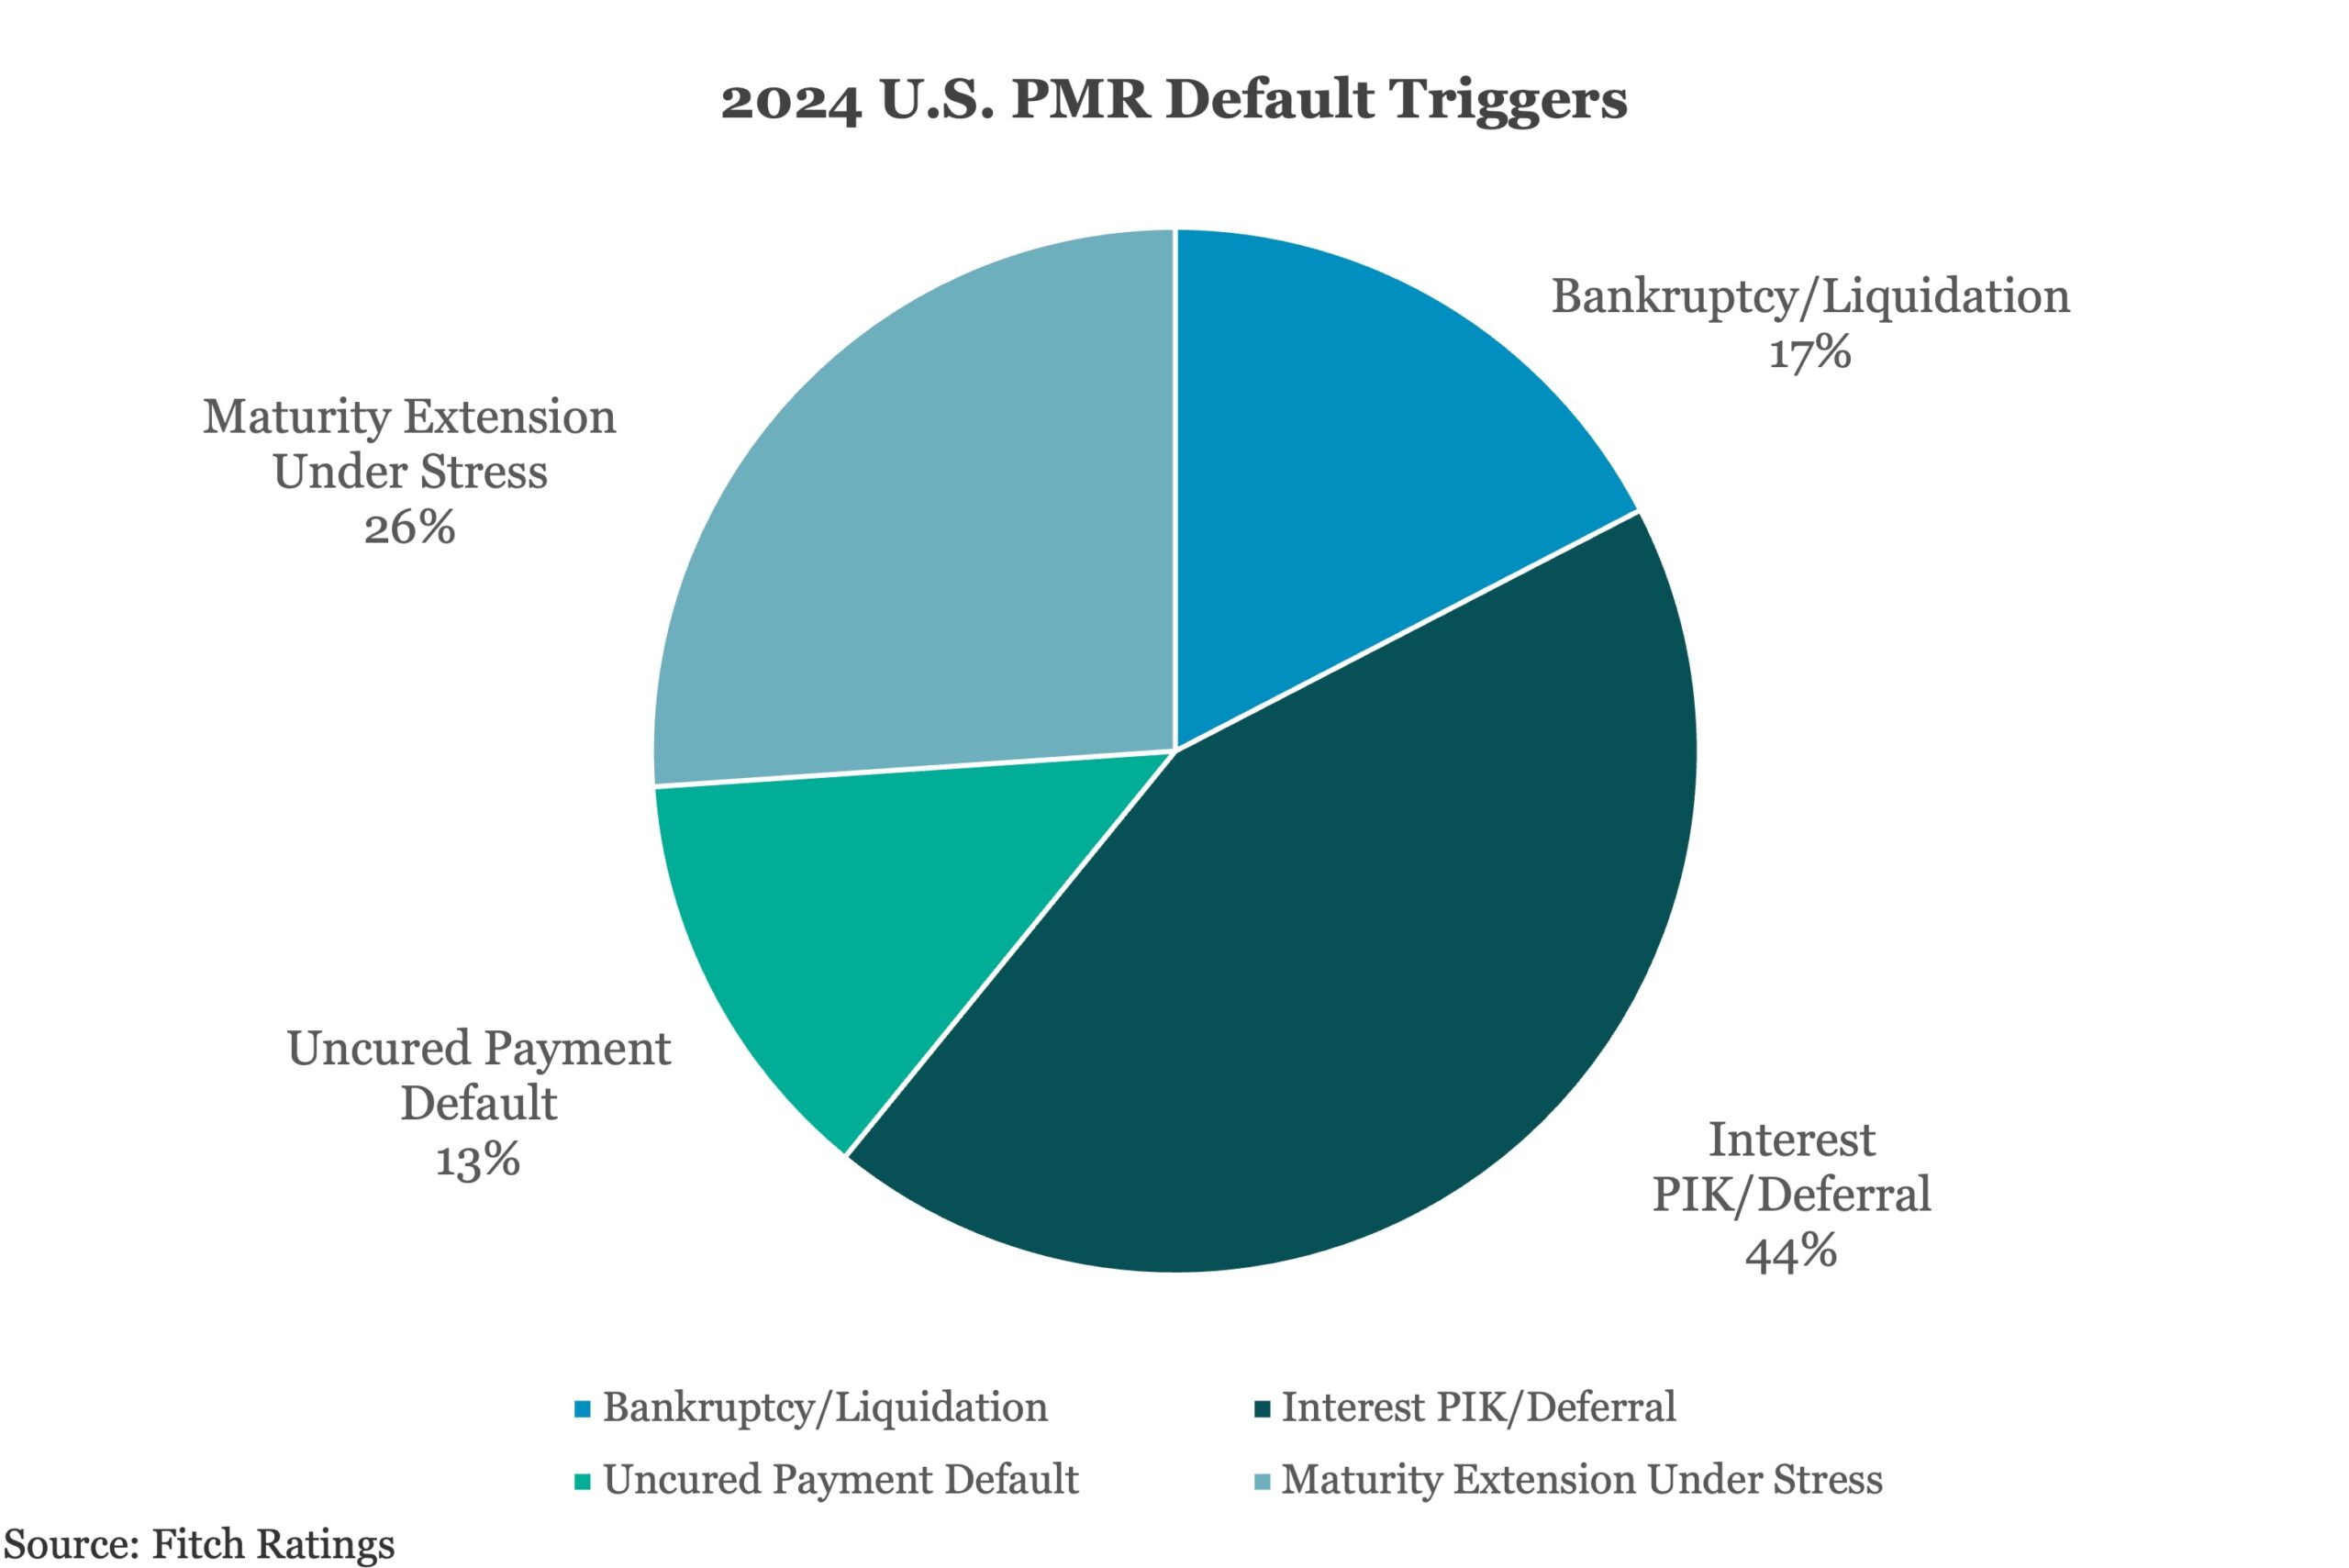
While distressed debt exchanges (DDEs) drove most defaults in 2023, over half of last year’s defaults stemmed from bankruptcy filings and maturity extensions for struggling issuers. Fitch believes much of the increase in default rates in the U.S. PMR portfolio is attributable to the impact of elevated base rates on cash flow and liquidity.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
