


Inflows, Competition to Pressure Perpetual BDC Earnings, Asset Quality
Click here to learn more.
The elevated competitive underwriting environment for business development companies (BDCs) will persist in 2025 due to significant capital being raised, especially in perpetual, non-traded BDCs amid sluggish M&A activity. The difficult environment will negatively affect earnings and asset-quality metrics, while also pressuring spreads and deal structures across the middle market.
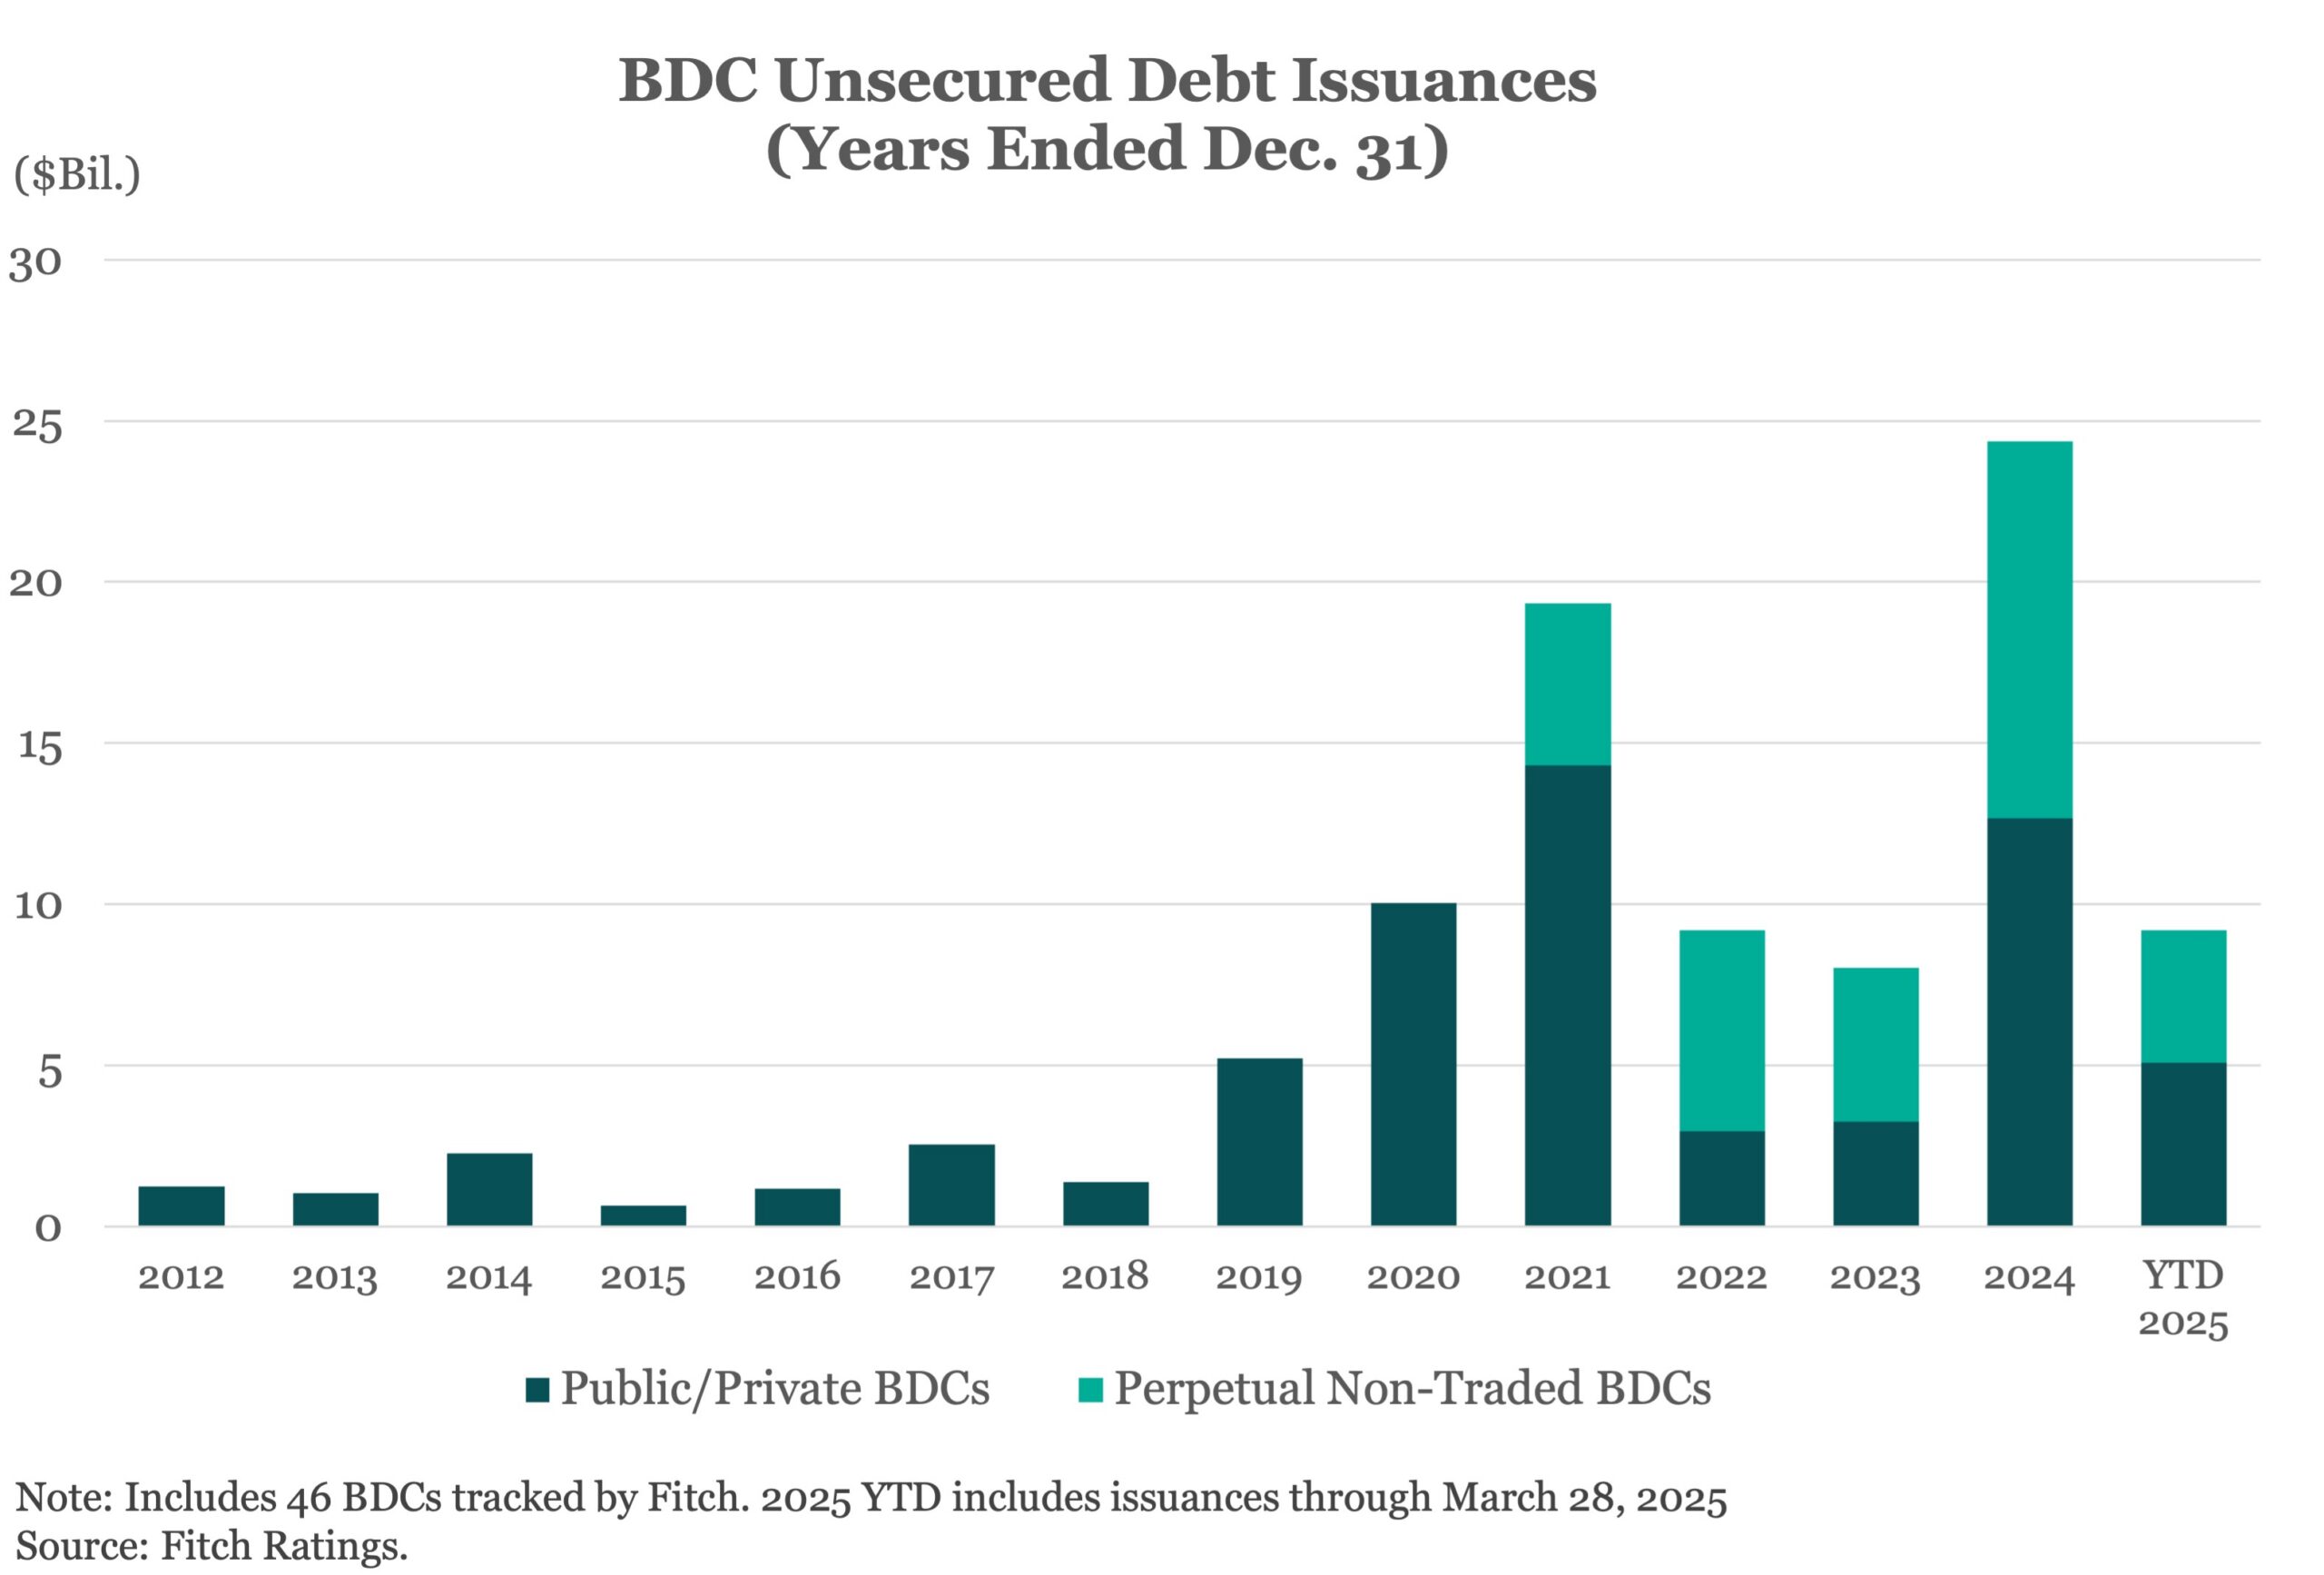
Perpetual BDCs have demonstrated strong market access, issuing $11.7 billion of unsecured debt in 2024 and $5.1 billion YTD through March 28, 2025. Fitch-rated public and private BDCs issued $12.7 billion and $5.1 billion during the same time periods. Despite strong issuance over the past year, unsecured debt at perpetual BDCs averaged 26.3% of total debt as of Dec. 31, 2024, well below the 50.5% average for Fitch-rated public and private BDCs.
Perpetual BDCs have limited near-term refinancing needs but will need to continue to issue unsecured debt to maintain or improve funding flexibility as they grow. Unsecured debt maturities are expected to pick up across the sector in 2026. For perpetual BDCs, 42.2% of unsecured debt at YE 2024 matures in 2029 or beyond.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…