


Fitch-rated U.S. business development companies (BDCs) face persistent headwinds in 2024, with rising paid-in-kind (PIK) income and continued markdowns of investments during 1Q24 signaling additional credit issues and resultant net investment income (NII) pressure. However, increased utilization of supplemental dividend policies will support dividend coverage, with BDCs well positioned for new originations as M&A activity picks up given relatively low leverage and strong funding profiles.
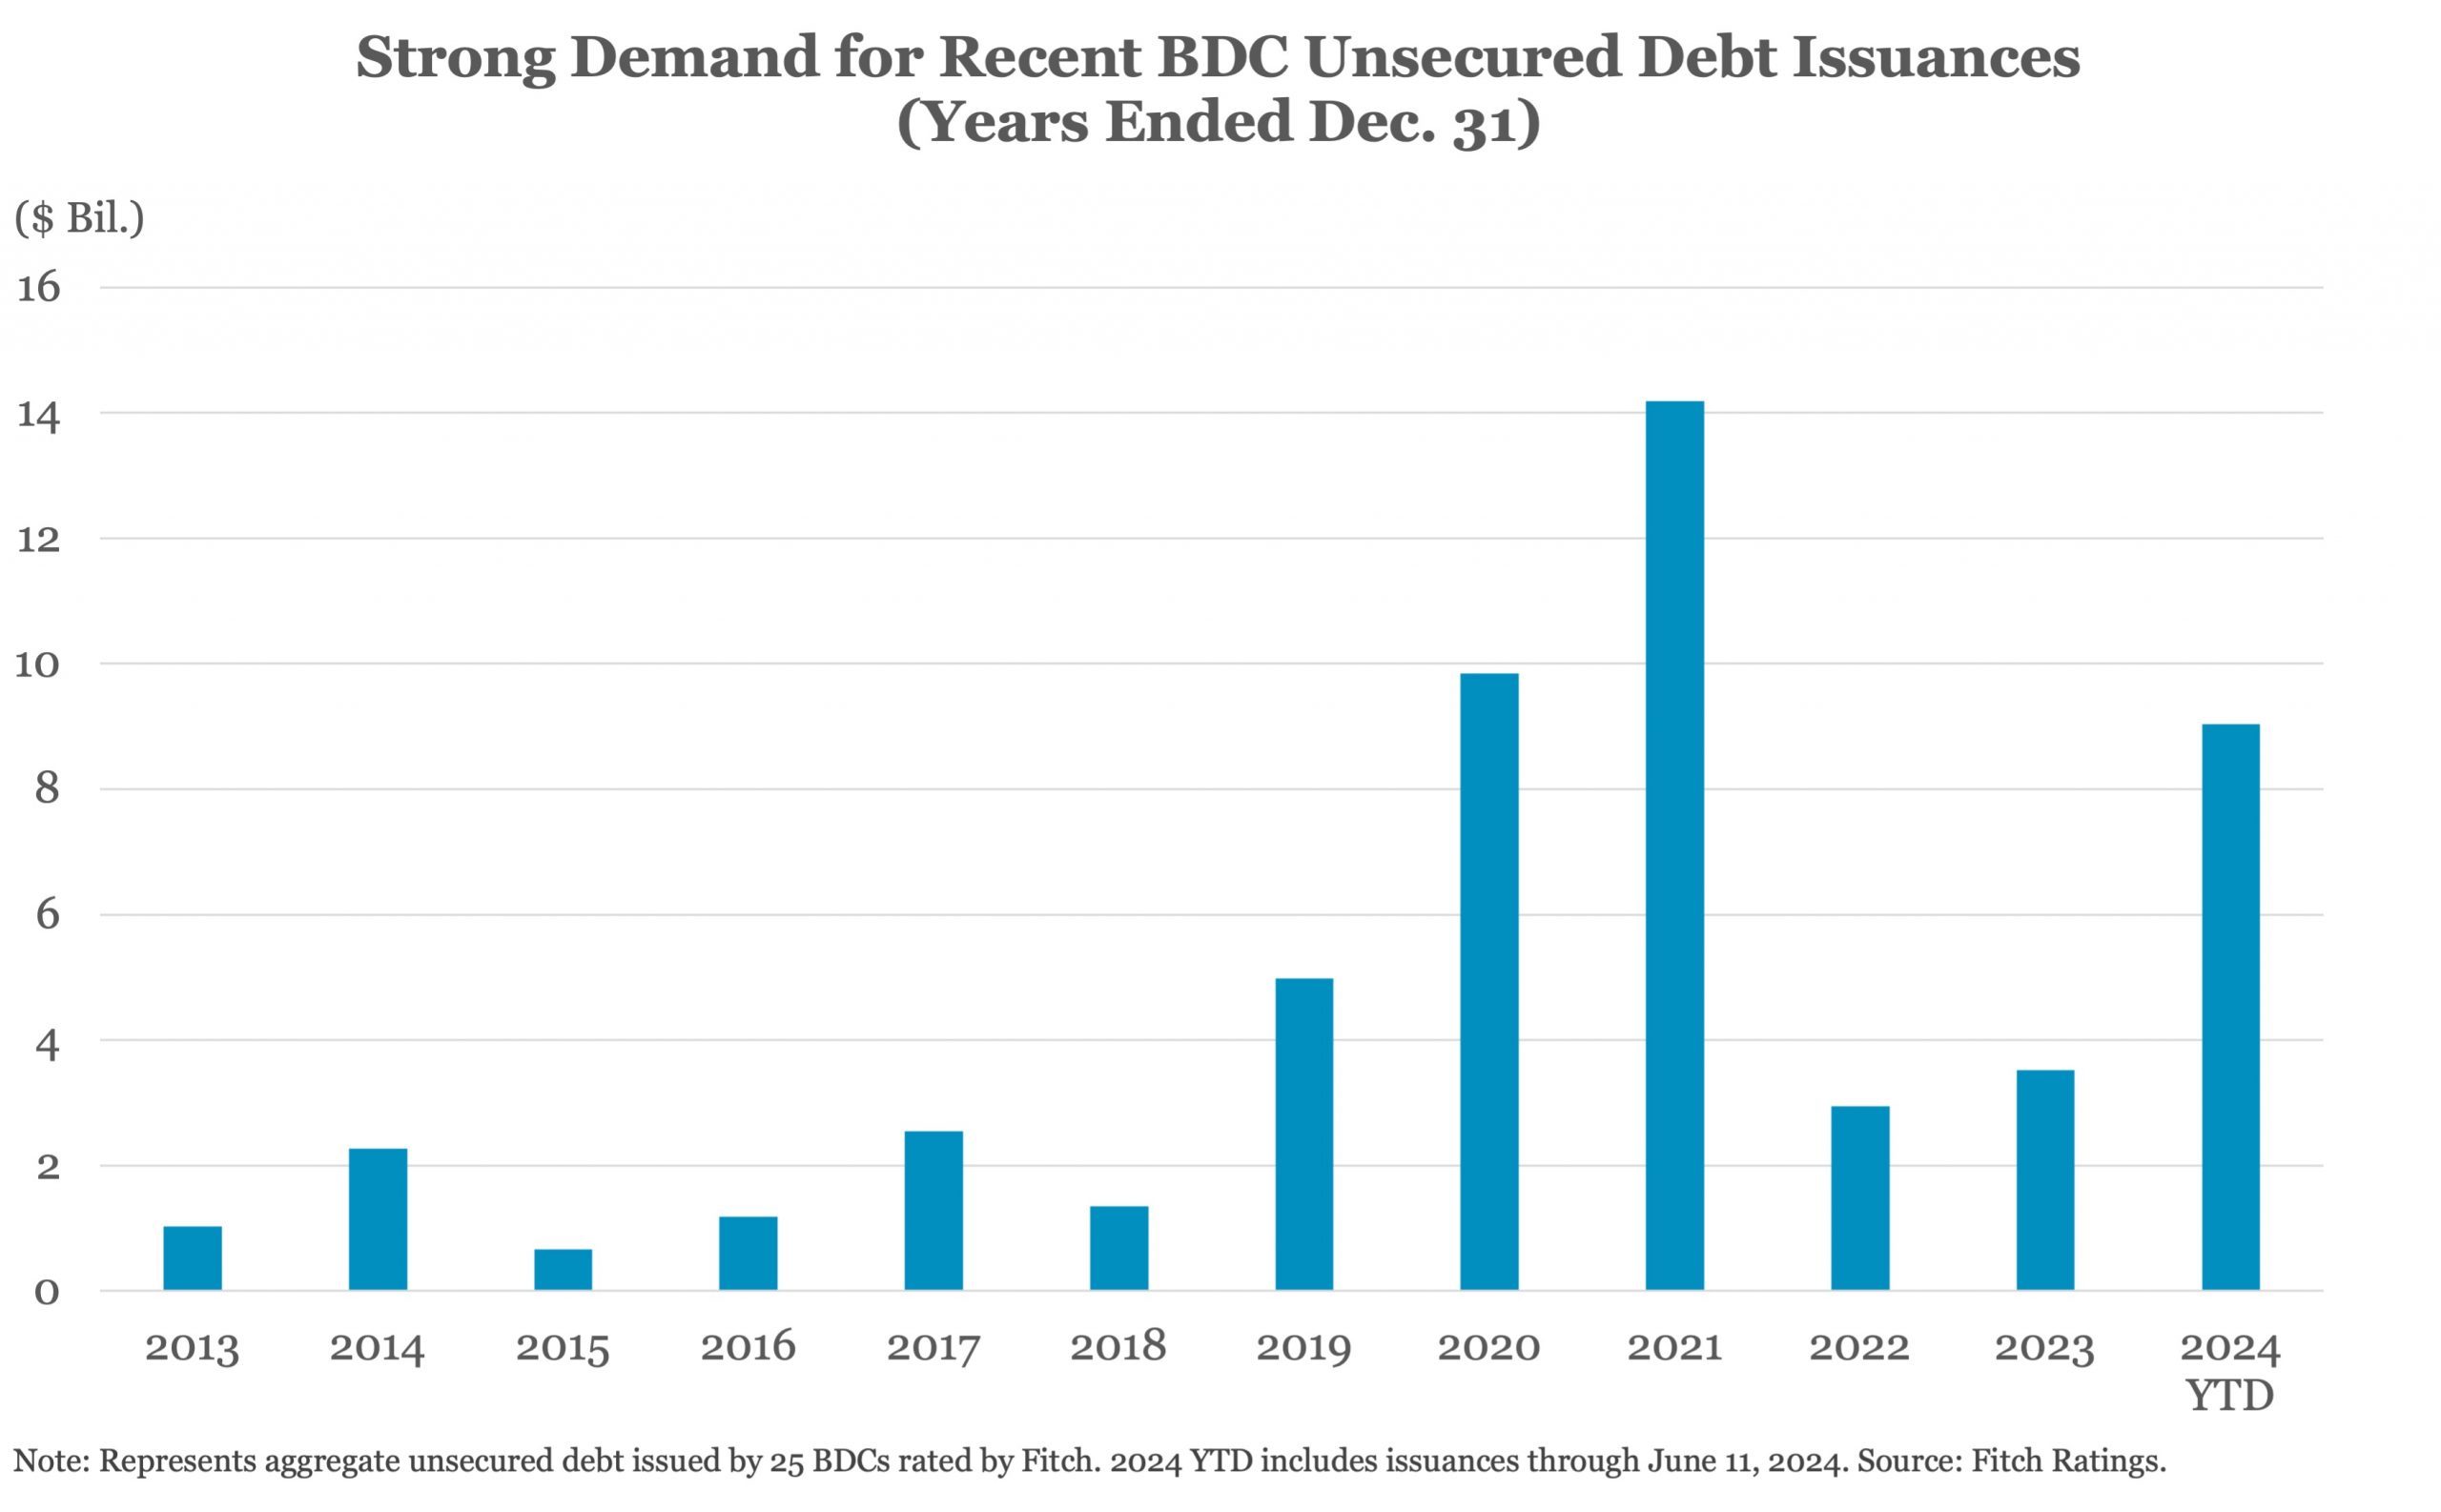
BDCs continue to tap the unsecured debt markets, with four rated BDCs issuing $1.9 billion in May to-date, bringing the year-to-date total to $7.1 billion, more than the $6.5 billion issued in 2022 and 2023 combined. Elevated rates have driven higher coupons on recent issuances compared to upcoming maturities, but BDCs have been increasingly utilizing interest rate swaps to prepare for eventual rate cuts. Unsecured debt averaged 52.0% of total debt at 1Q24 and secured debt averaged 23.1% of assets, providing solid funding flexibility.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
