


Default Rate Rises in Fitch’s U.S. Privately Monitored Corporate Ratings Portfolio
Click here to learn more.
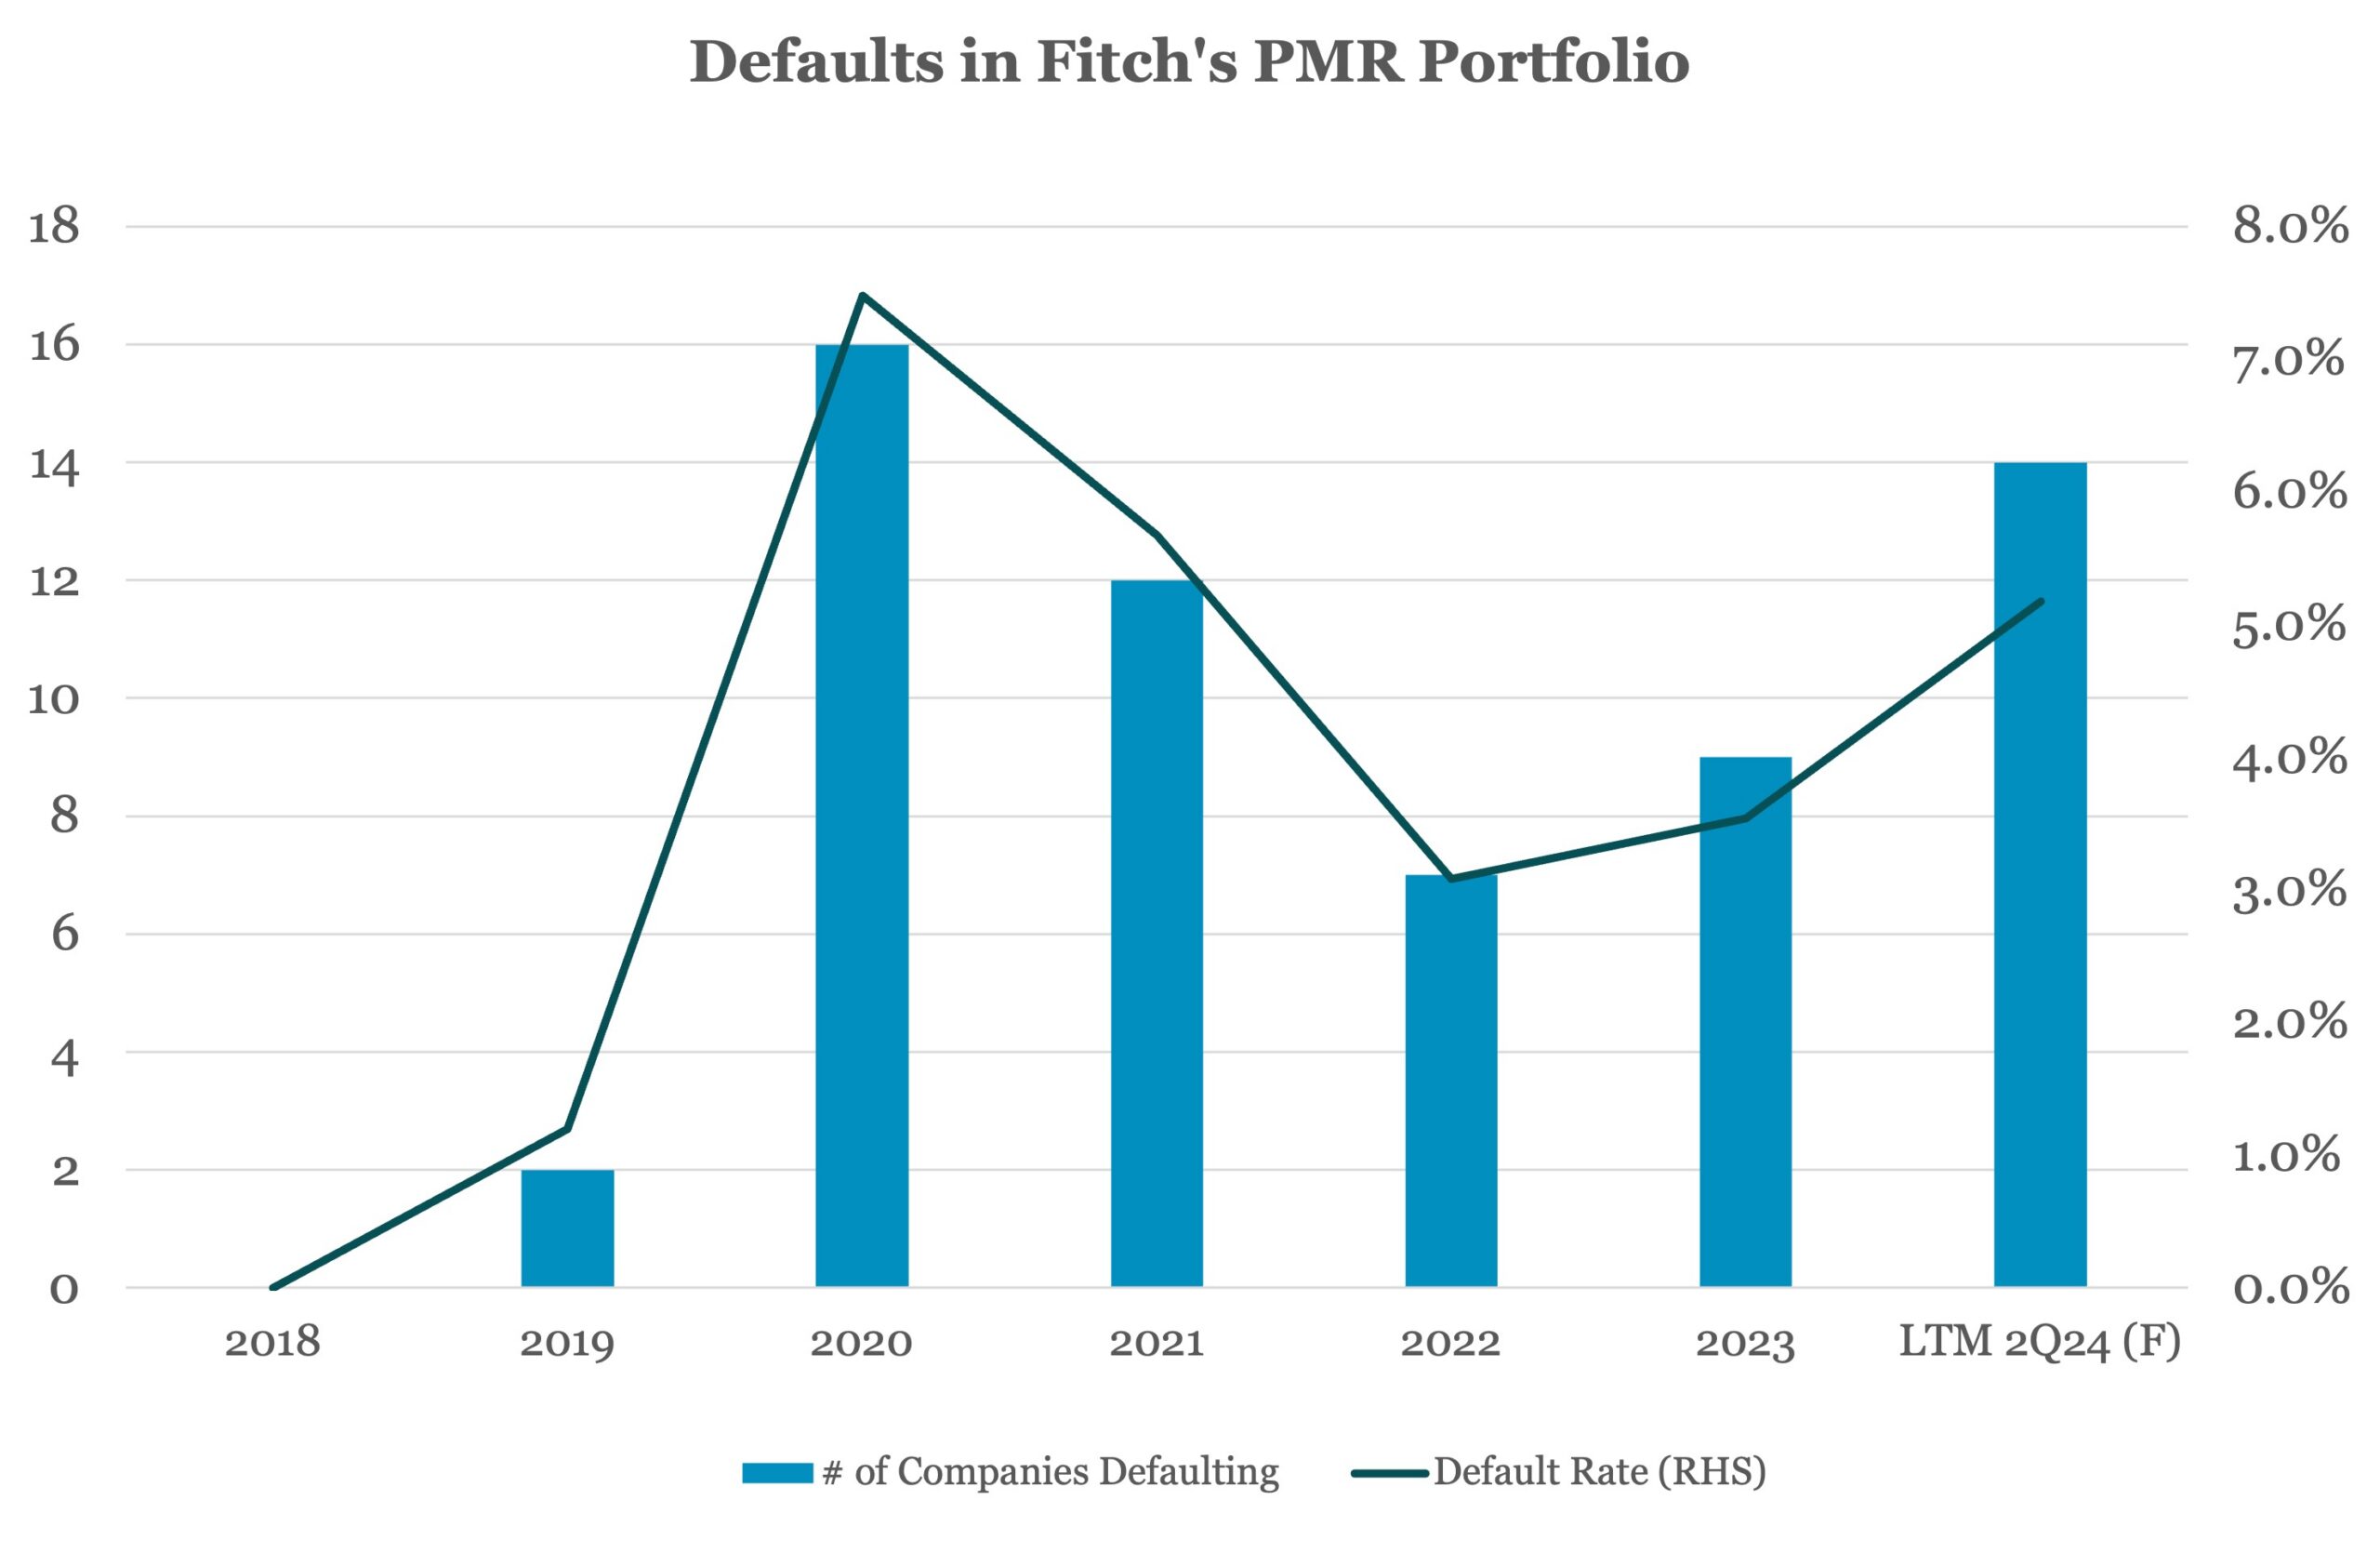
The default rate for Fitch’s corporate portfolio of U.S. Privately Monitored Ratings (PMR) continues to rise despite better-than-expected resilience and growth of the U.S. economy as issuers continue to struggle with elevated interest rates and impending loan maturities. We continue to expect defaults to remain elevated in 2024 with an increase in the number of restructurings in the portfolio where lenders take control of and/or liquidate the companies.
The increase in defaults is above Fitch’s expectations heading into 2024 as US economic growth and anticipated rate cuts were expected to support cash flows, easing concerns about refinancing and liquidity. However, depressed deal making has limited exit opportunities for sponsors and lenders resulting in challenges in addressing loan maturities, while higher-than-anticipated inflation has pushed out expectations for rate cuts and reduced corporate cash flows, pressuring issuers’ ability to make cash interest payments.
For the quarter-to-date through May 31, there were four new defaults in the portfolio and one that will roll off in 2Q24. Assuming no new defaults in June, these three incremental net defaults would push the portfolio TTM default rate through 2Q24 to approximately 5.2%, up from 4.1% in March and 3.7% at YE23.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…