


Click here to learn more.
‘CCC’ Exposure Marginally Up
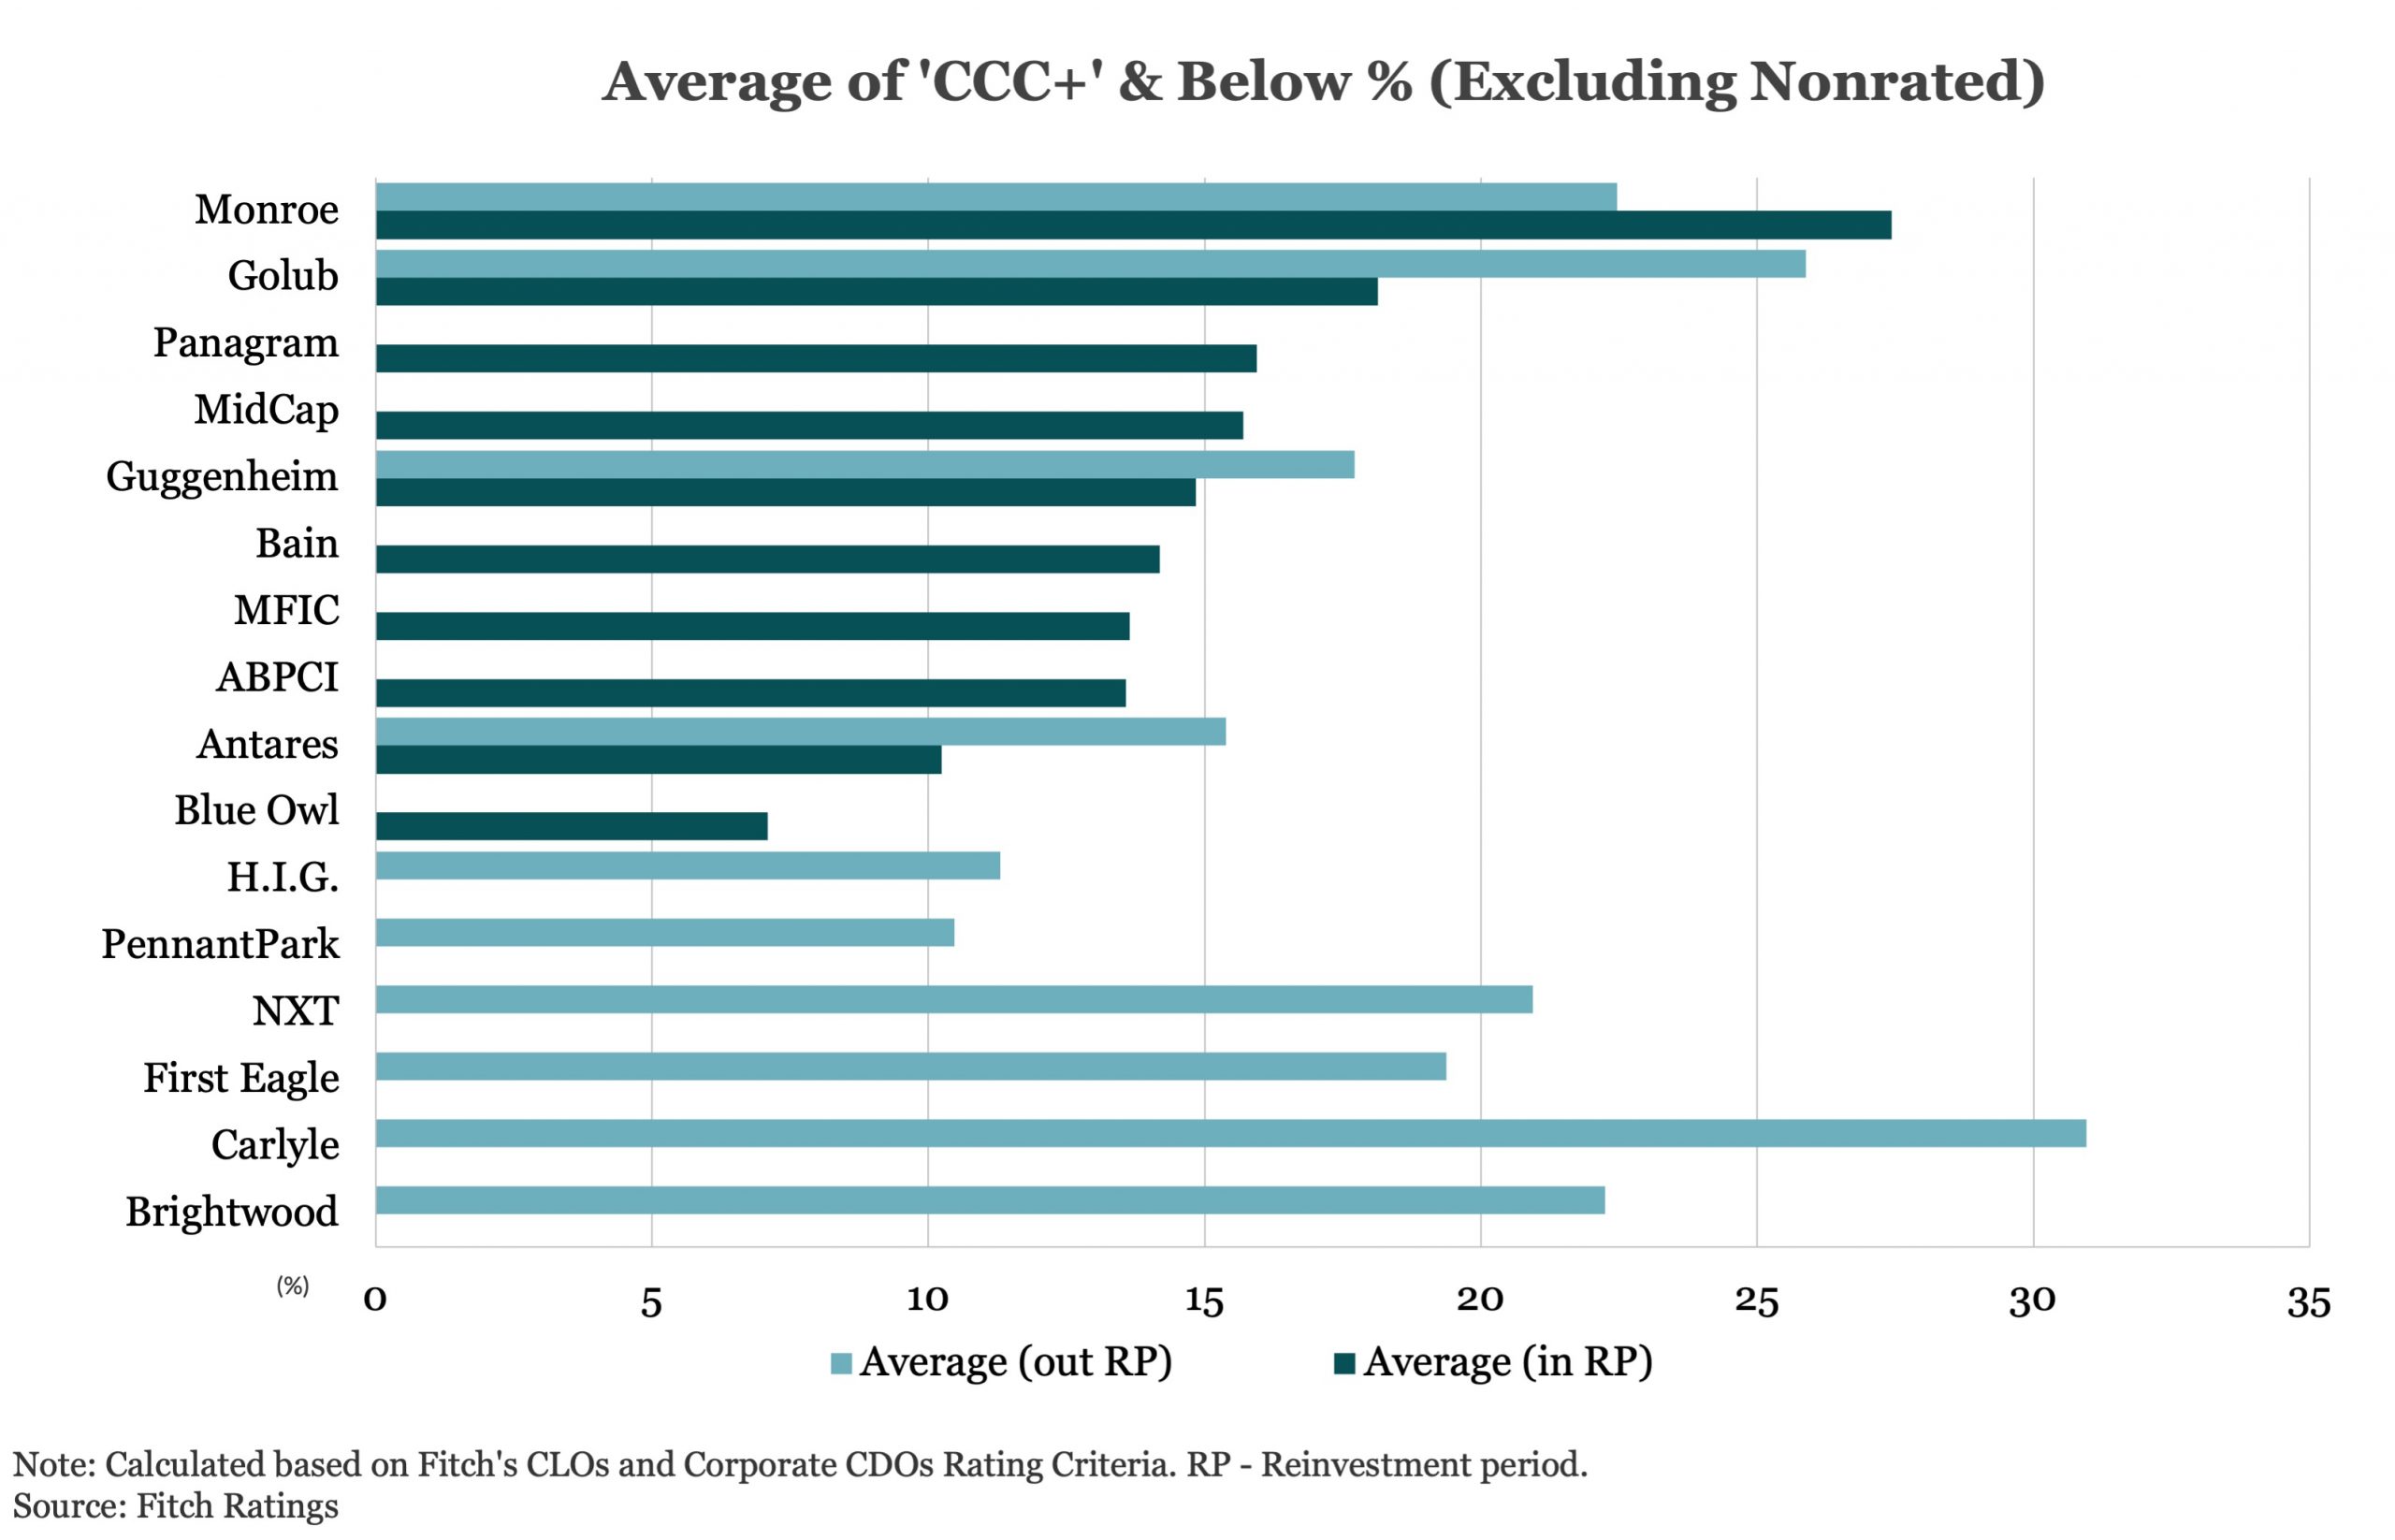
Exposure to assets with Fitch IDRs or credit opinions of ‘CCC+’ or below, excluding nonrated assets, increased by 20 bps to 18.6%, compared to last month and 3.5% higher than a year ago. For the 25 transactions with a rise in exposure since last month, the increase averaged 1.6%. For the 25 MM CLOs with a decline, exposure was 1.3% lower on average. Four MM CLOs in reinvestment are failing at least one of the rating agencies’ ‘CCC+’ concentration limits.
Cushions in Collateral Quality Tests Stay Mostly Positive
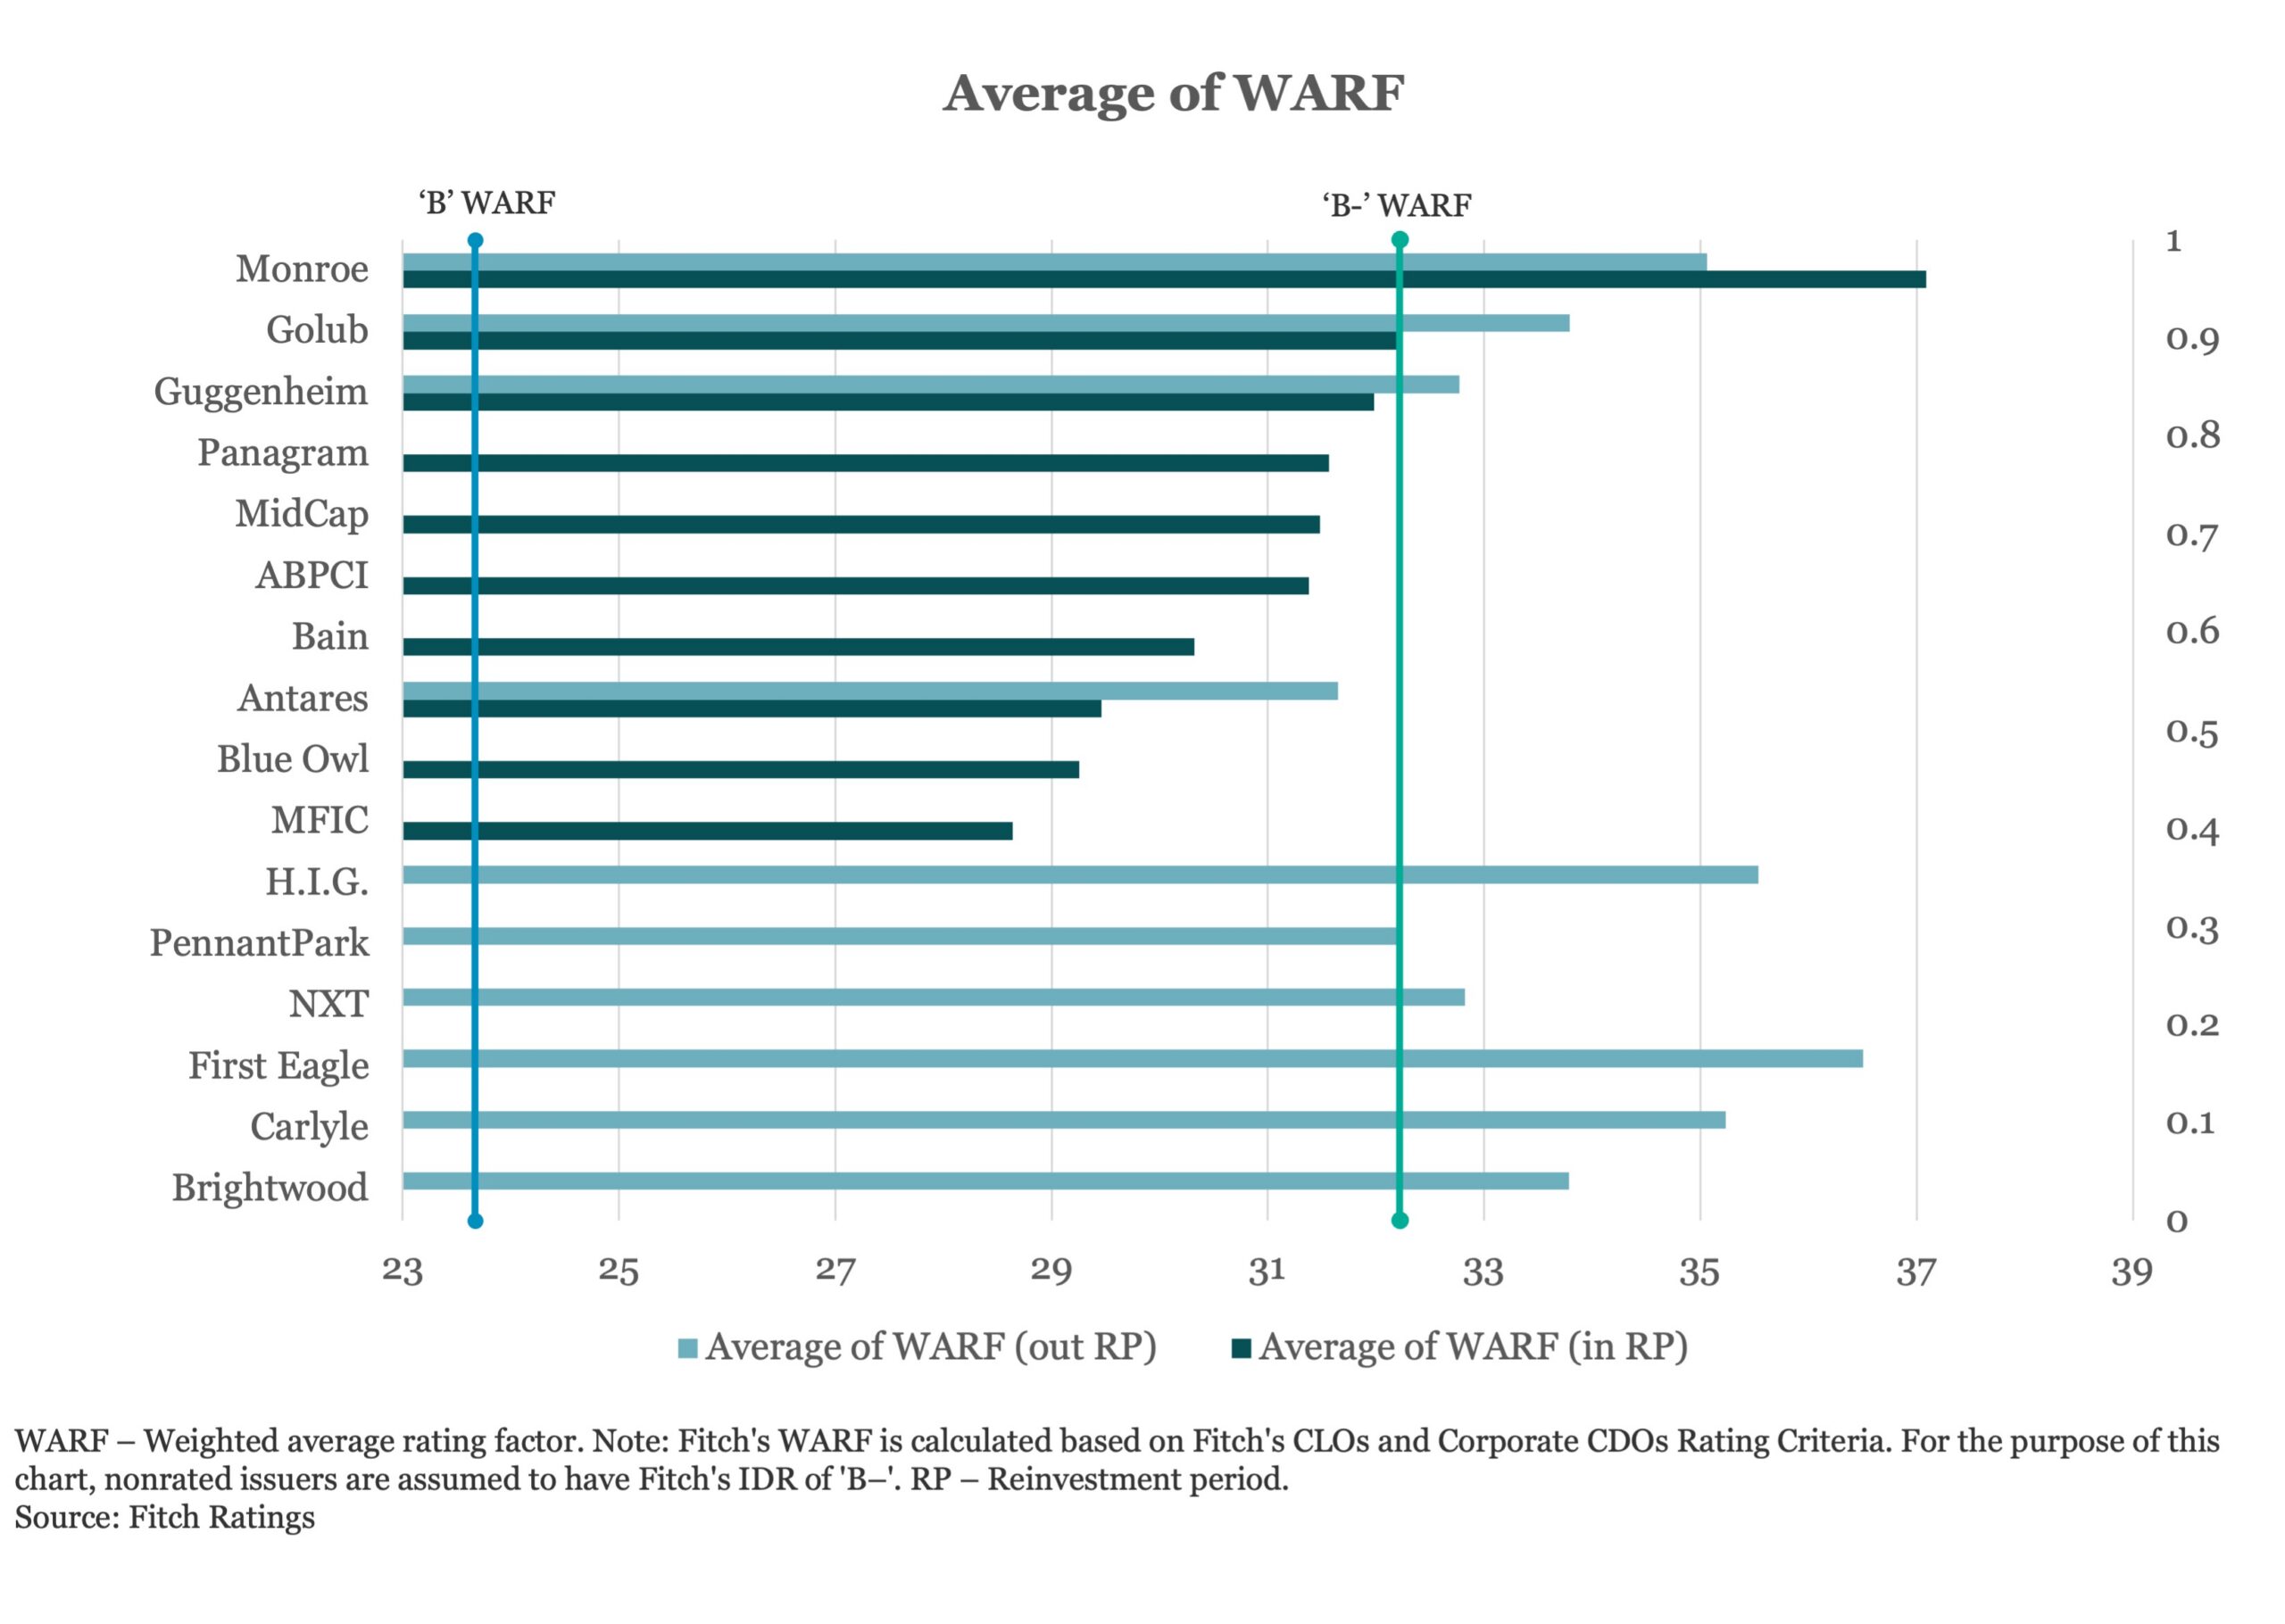
All Fitch-rated MM CLOs include a Fitch Test Matrix as part of a CLO’s Collateral Quality Tests (CQTs) in MM CLOs, including Fitch weighted average recovery rate (WARR), Fitch weighted average rating factor (WARF), weighted average spread (WAS) and weighted average life (WAL), generally remain in compliance against test limits for deals in reinvestment. The median cushion to limits were 2.3% for WARR, 2.0 points WARF, 0.4% WAS and 2.7 years WAL. Two MM CLOs in reinvestment are not in compliance with the WARR test limit, and no deal breached the Fitch WARF test at the end of May 2024.




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…