


Click here to learn more.
Fitch’s Privately Monitored Ratings Portfolio, Rating Activity
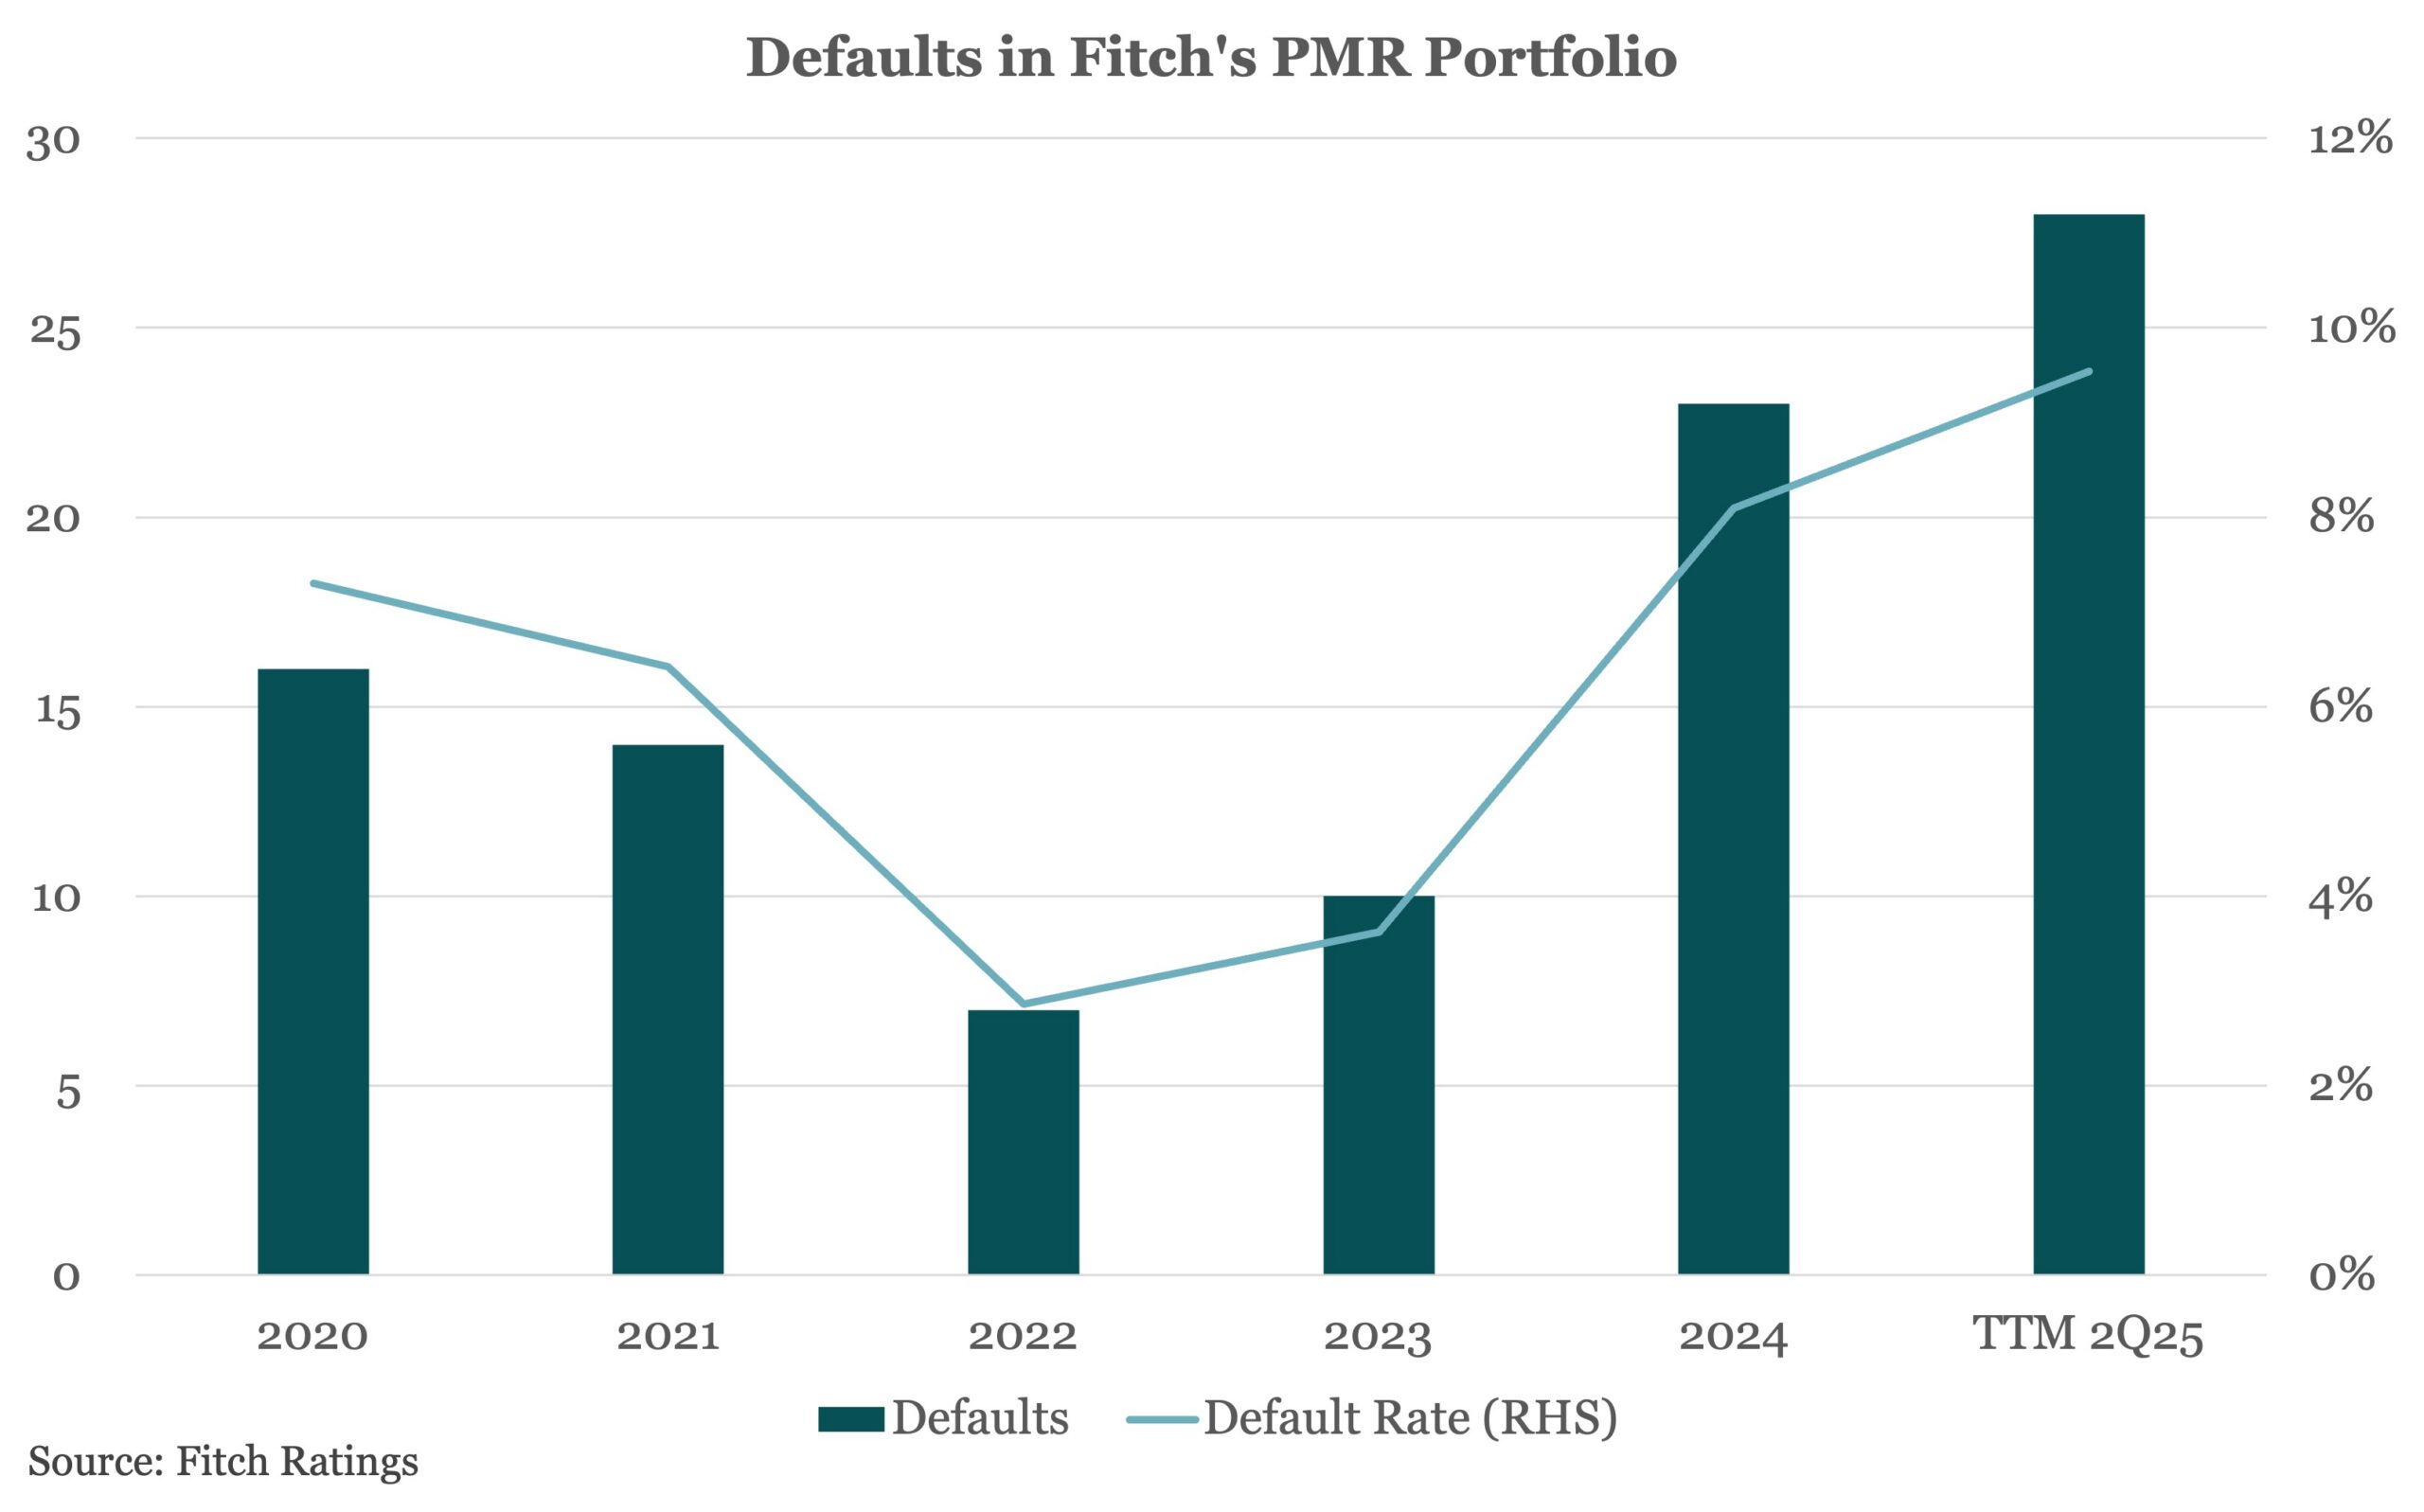
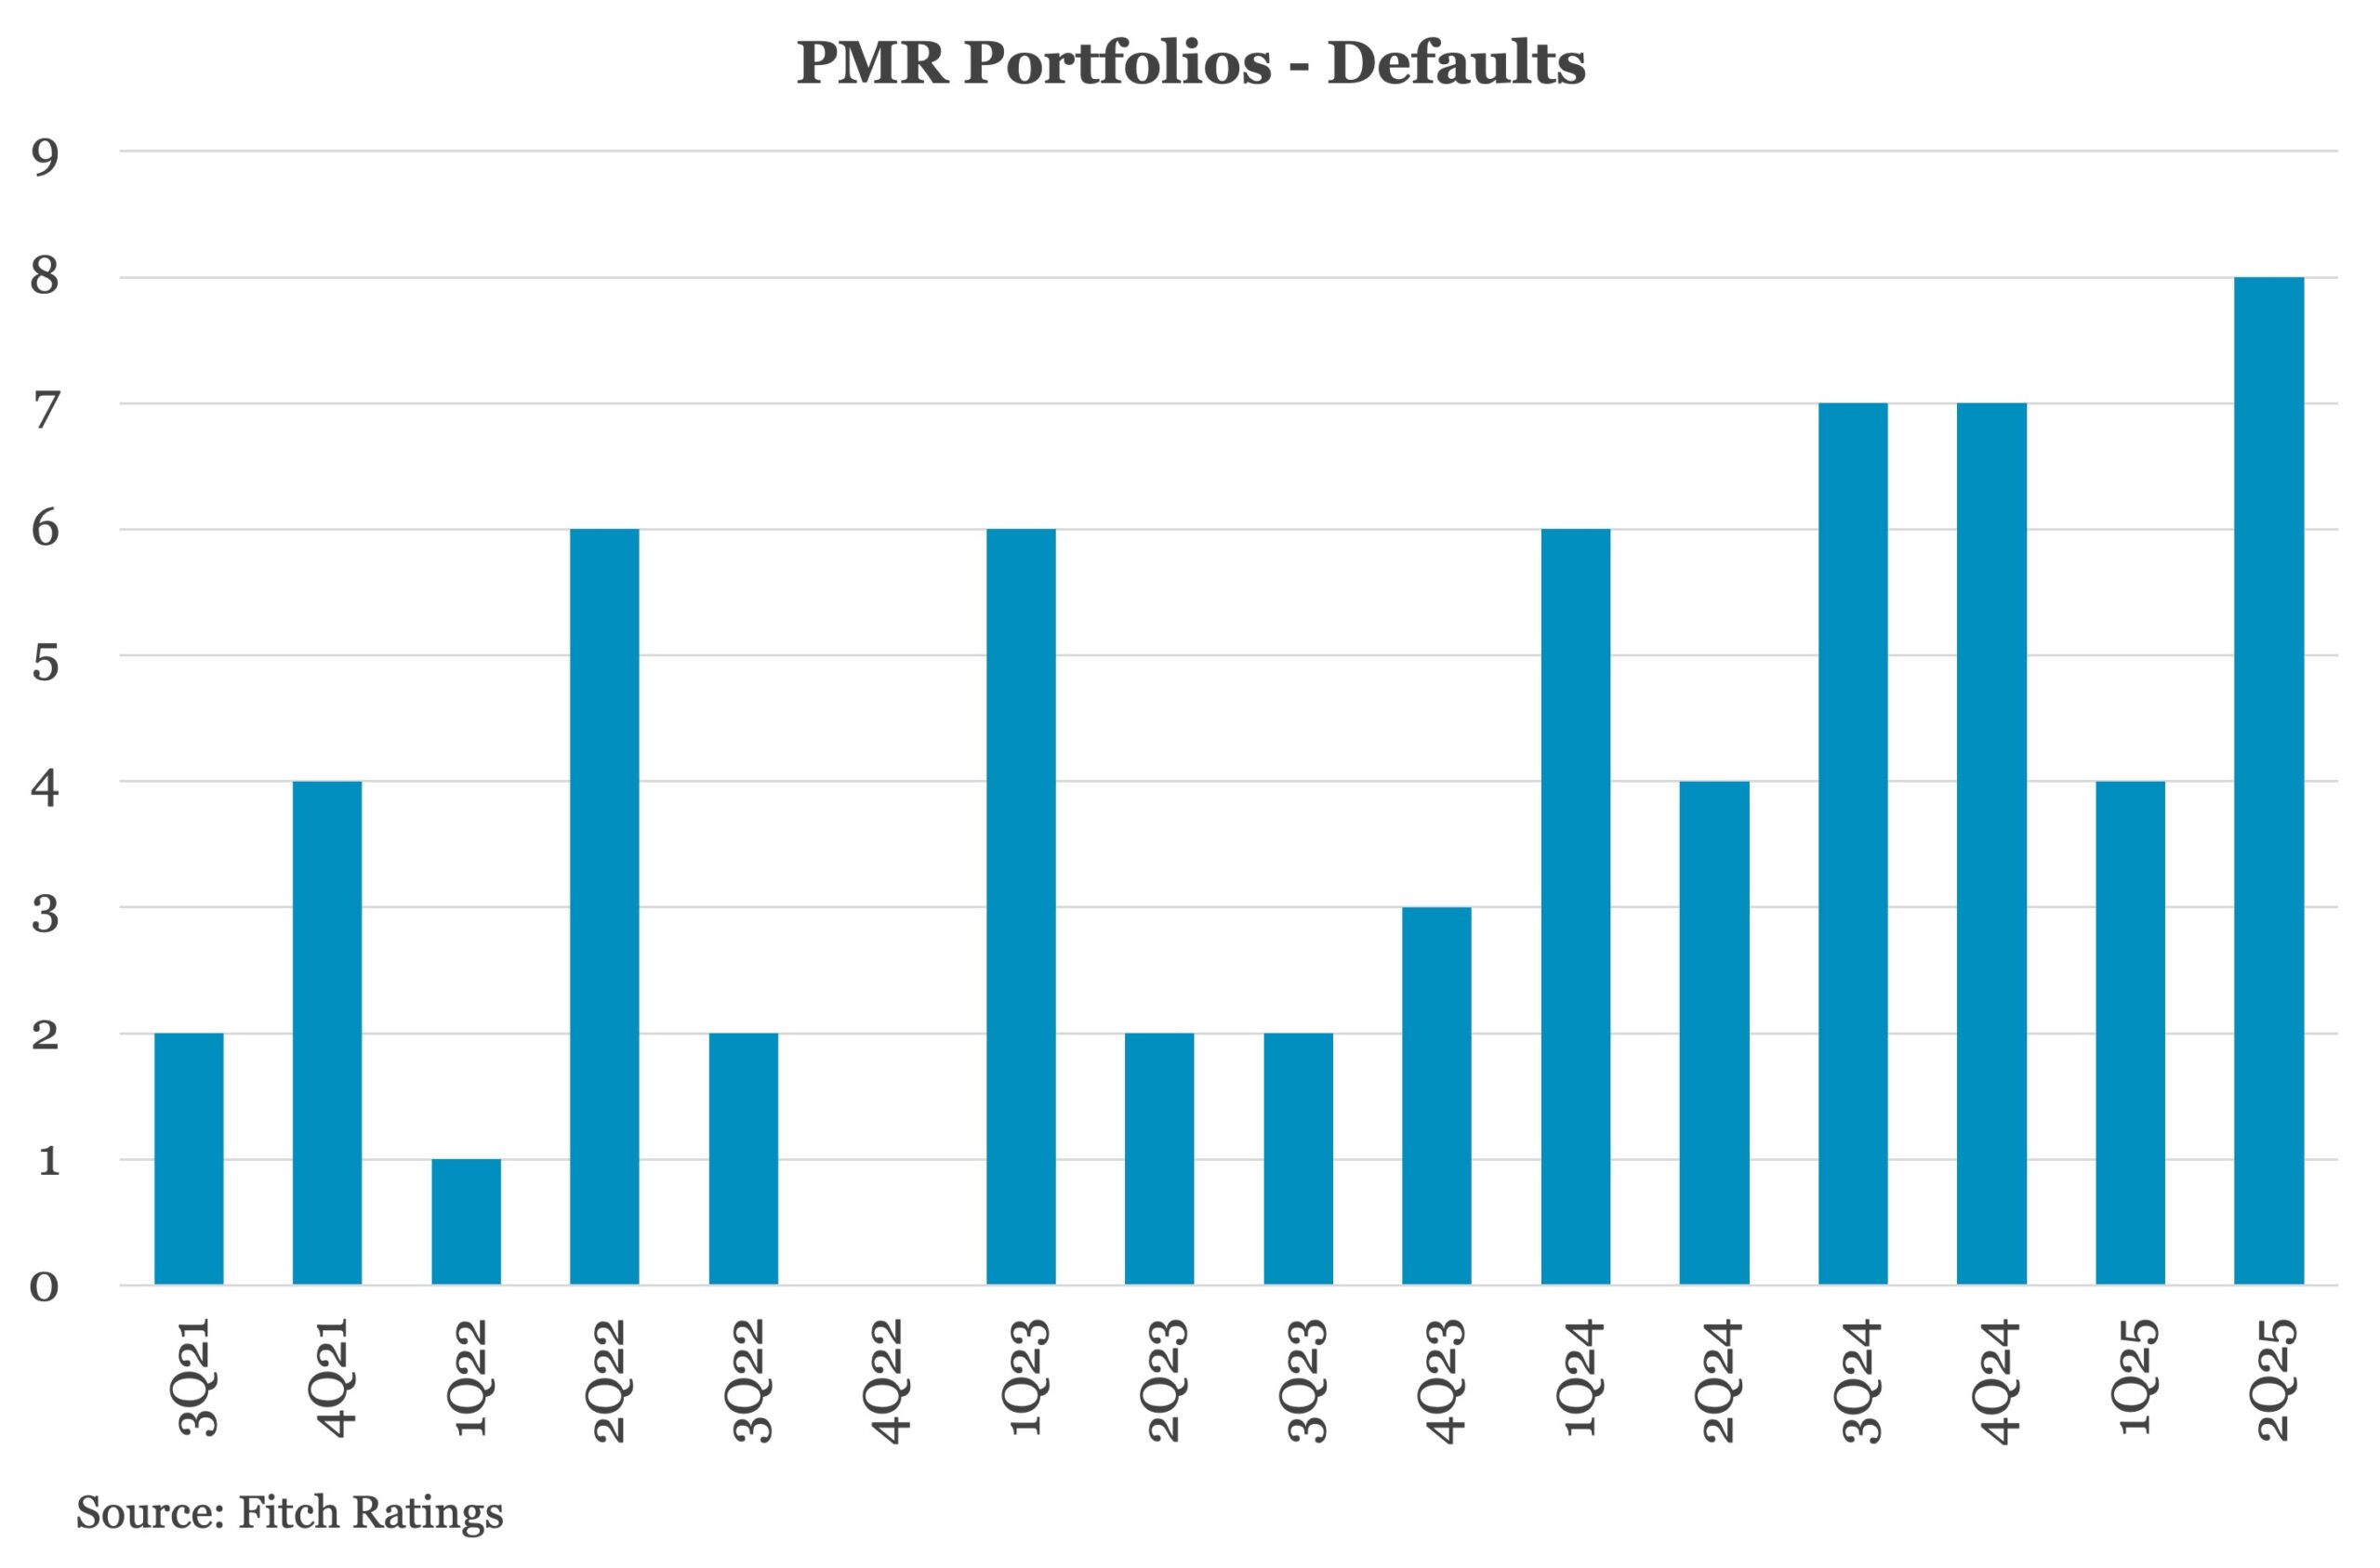
The issuer-weighted TTM default rate for PMRs rose to 9.5% in 2Q25 from 7.8% in 1Q25. Fitch recorded 28 unique defaults for the TTM period, up from 23 in 1Q25. This is the highest default rate since tracking began in 2017. Smaller, private issuers are more vulnerable than larger peers to economic swings, GDP slowdowns, and persistent elevated rates. Their floating-rate structures increase this risk.
Including repeat defaults by the same issuer, Fitch recorded 36 defaults in the TTM period ending 2Q25. Four defaults involved Chapter 11 bankruptcy or liquidation. Half of the cases involved interest deferrals or conversions of cash interest to payment-in-kind. Eight defaults were maturity extensions under stress.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…