


Click here to download report.
Defaults and Deferring Marginally Down
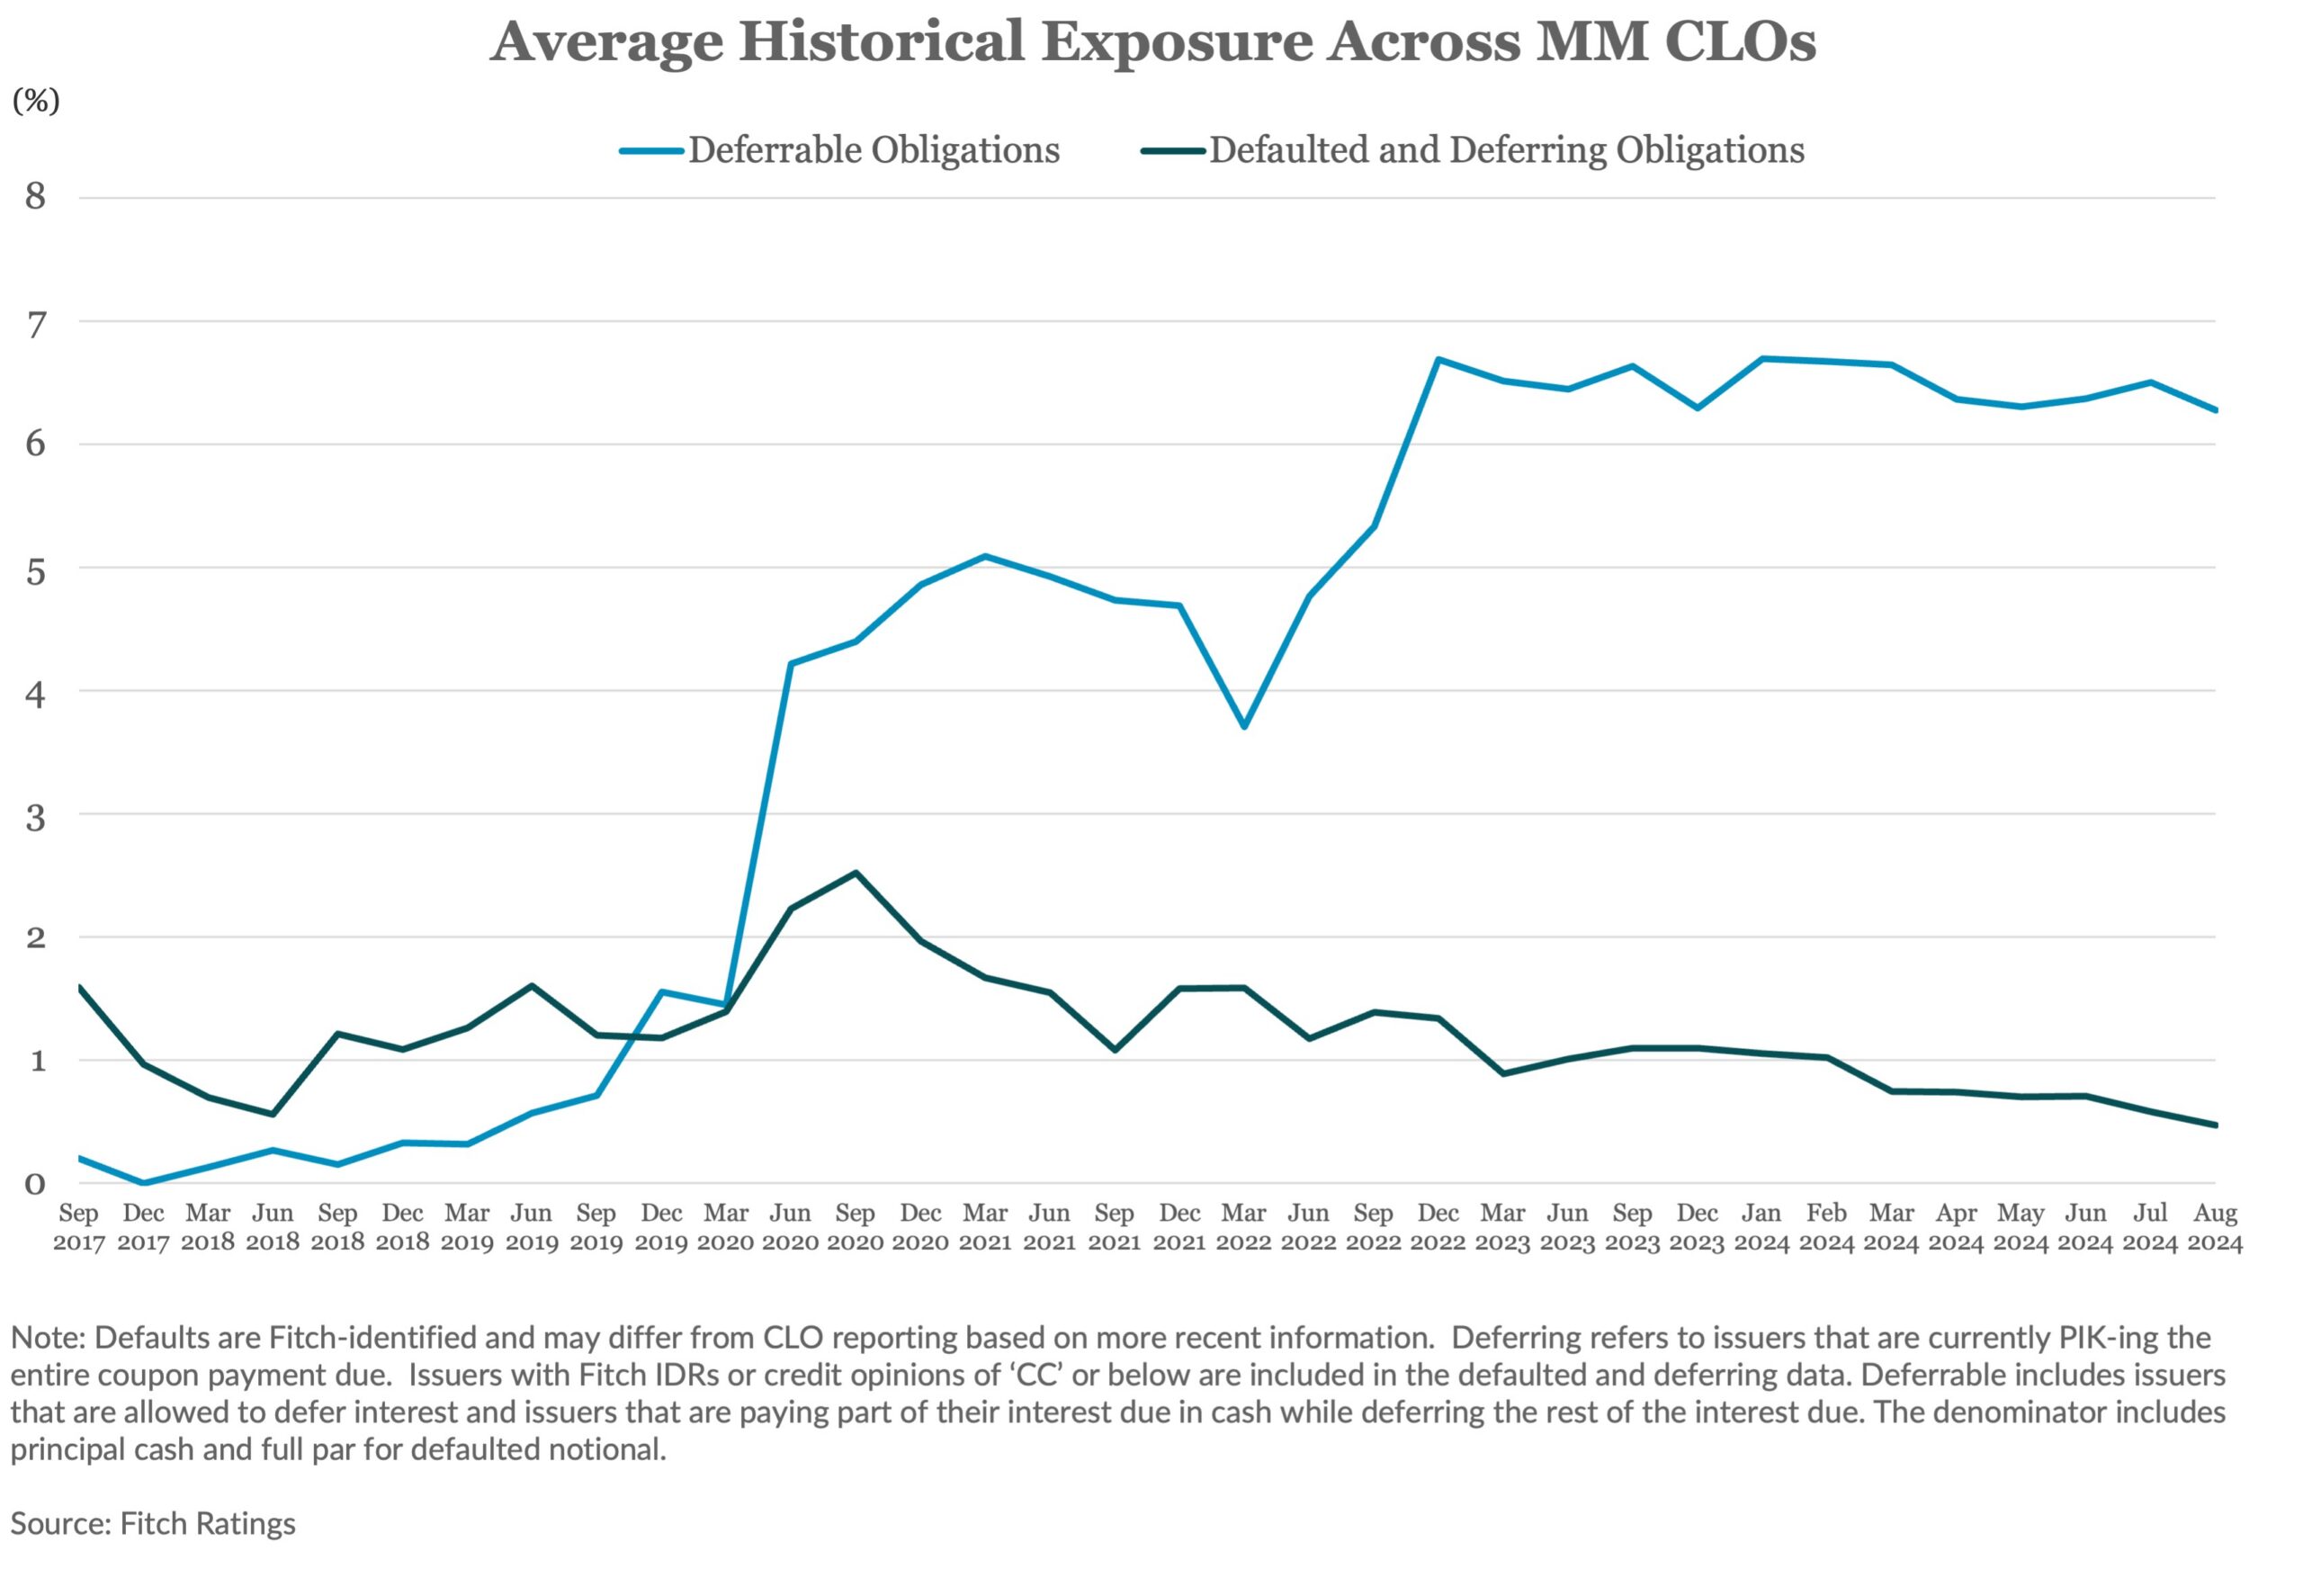
Fifteen CLOs had exposure to at least one defaulted or deferring issuer at the end of August 2024. Average defaulted and deferring exposure across middle market (MM) CLOs decreased to 0.5%, 10 basis points (bps) lower compared to last month. In August, two new defaulted or deferring issuers were reported. This was balanced by the removal of five prior defaults held in deals that were redeemed or reset. Additionally, one issuer was no longer reported as defaulted and two defaulted issuers were sold from the portfolio.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…