


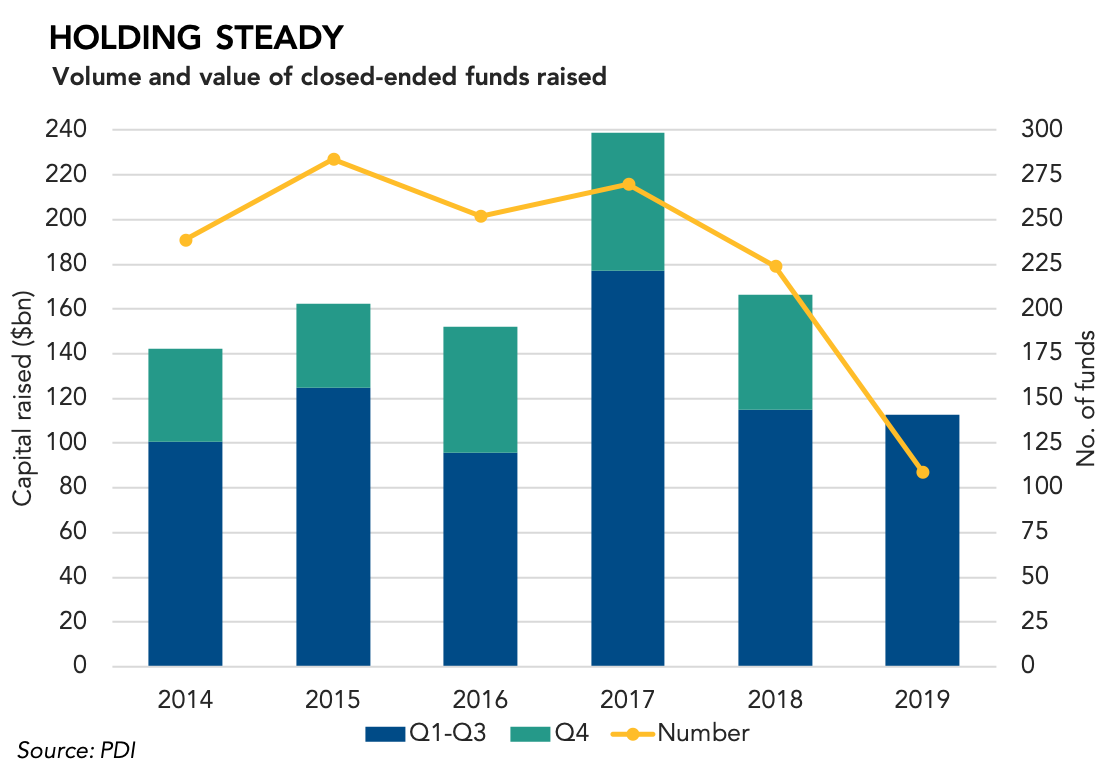
2017’s massive total of $239bn appears to be more of an aberration than a new norm.
Fundraising activity in the third quarter of this year is set to match 2018 levels as appetite for the asset class holds steady.
Preliminary figures for the PDI Q3 2019 Fundraising Report show total fundraising in the first nine months of the year reached $112.7 billion, slightly below the $114.9 billion raised in the same period last year.
With some fundraising late in the quarter likely to be added in the coming weeks, it is expected that the final fundraising amount for the third quarter will rise and may exceed 2018’s figure. Beyond the closed-ended fund space PDI has seen significant activity in evergreen vehicles and a growing number of LPs looking to co-invest or using separately managed accounts.
The fundraising totals suggest LP appetite for the asset class remains strong, though still well below the spike in activity in 2017, when Q3 fundraising reached $177 billion. Increasingly, 2017’s figures, which reached $239 billion at year end, appear to be an outlier amid more modest growth in private debt fundraising overall.
The most fundraising activity typically takes place in the fourth quarter and at least an additional $53.5 billion of capital will need to be added in 2019 to beat 2018’s total.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
