


Download PDI’s Report: Fundraising sees Q3 revival
After a period of much-publicised struggles, fund managers seeking fresh capital have been given a shot in the arm by the latest figures.
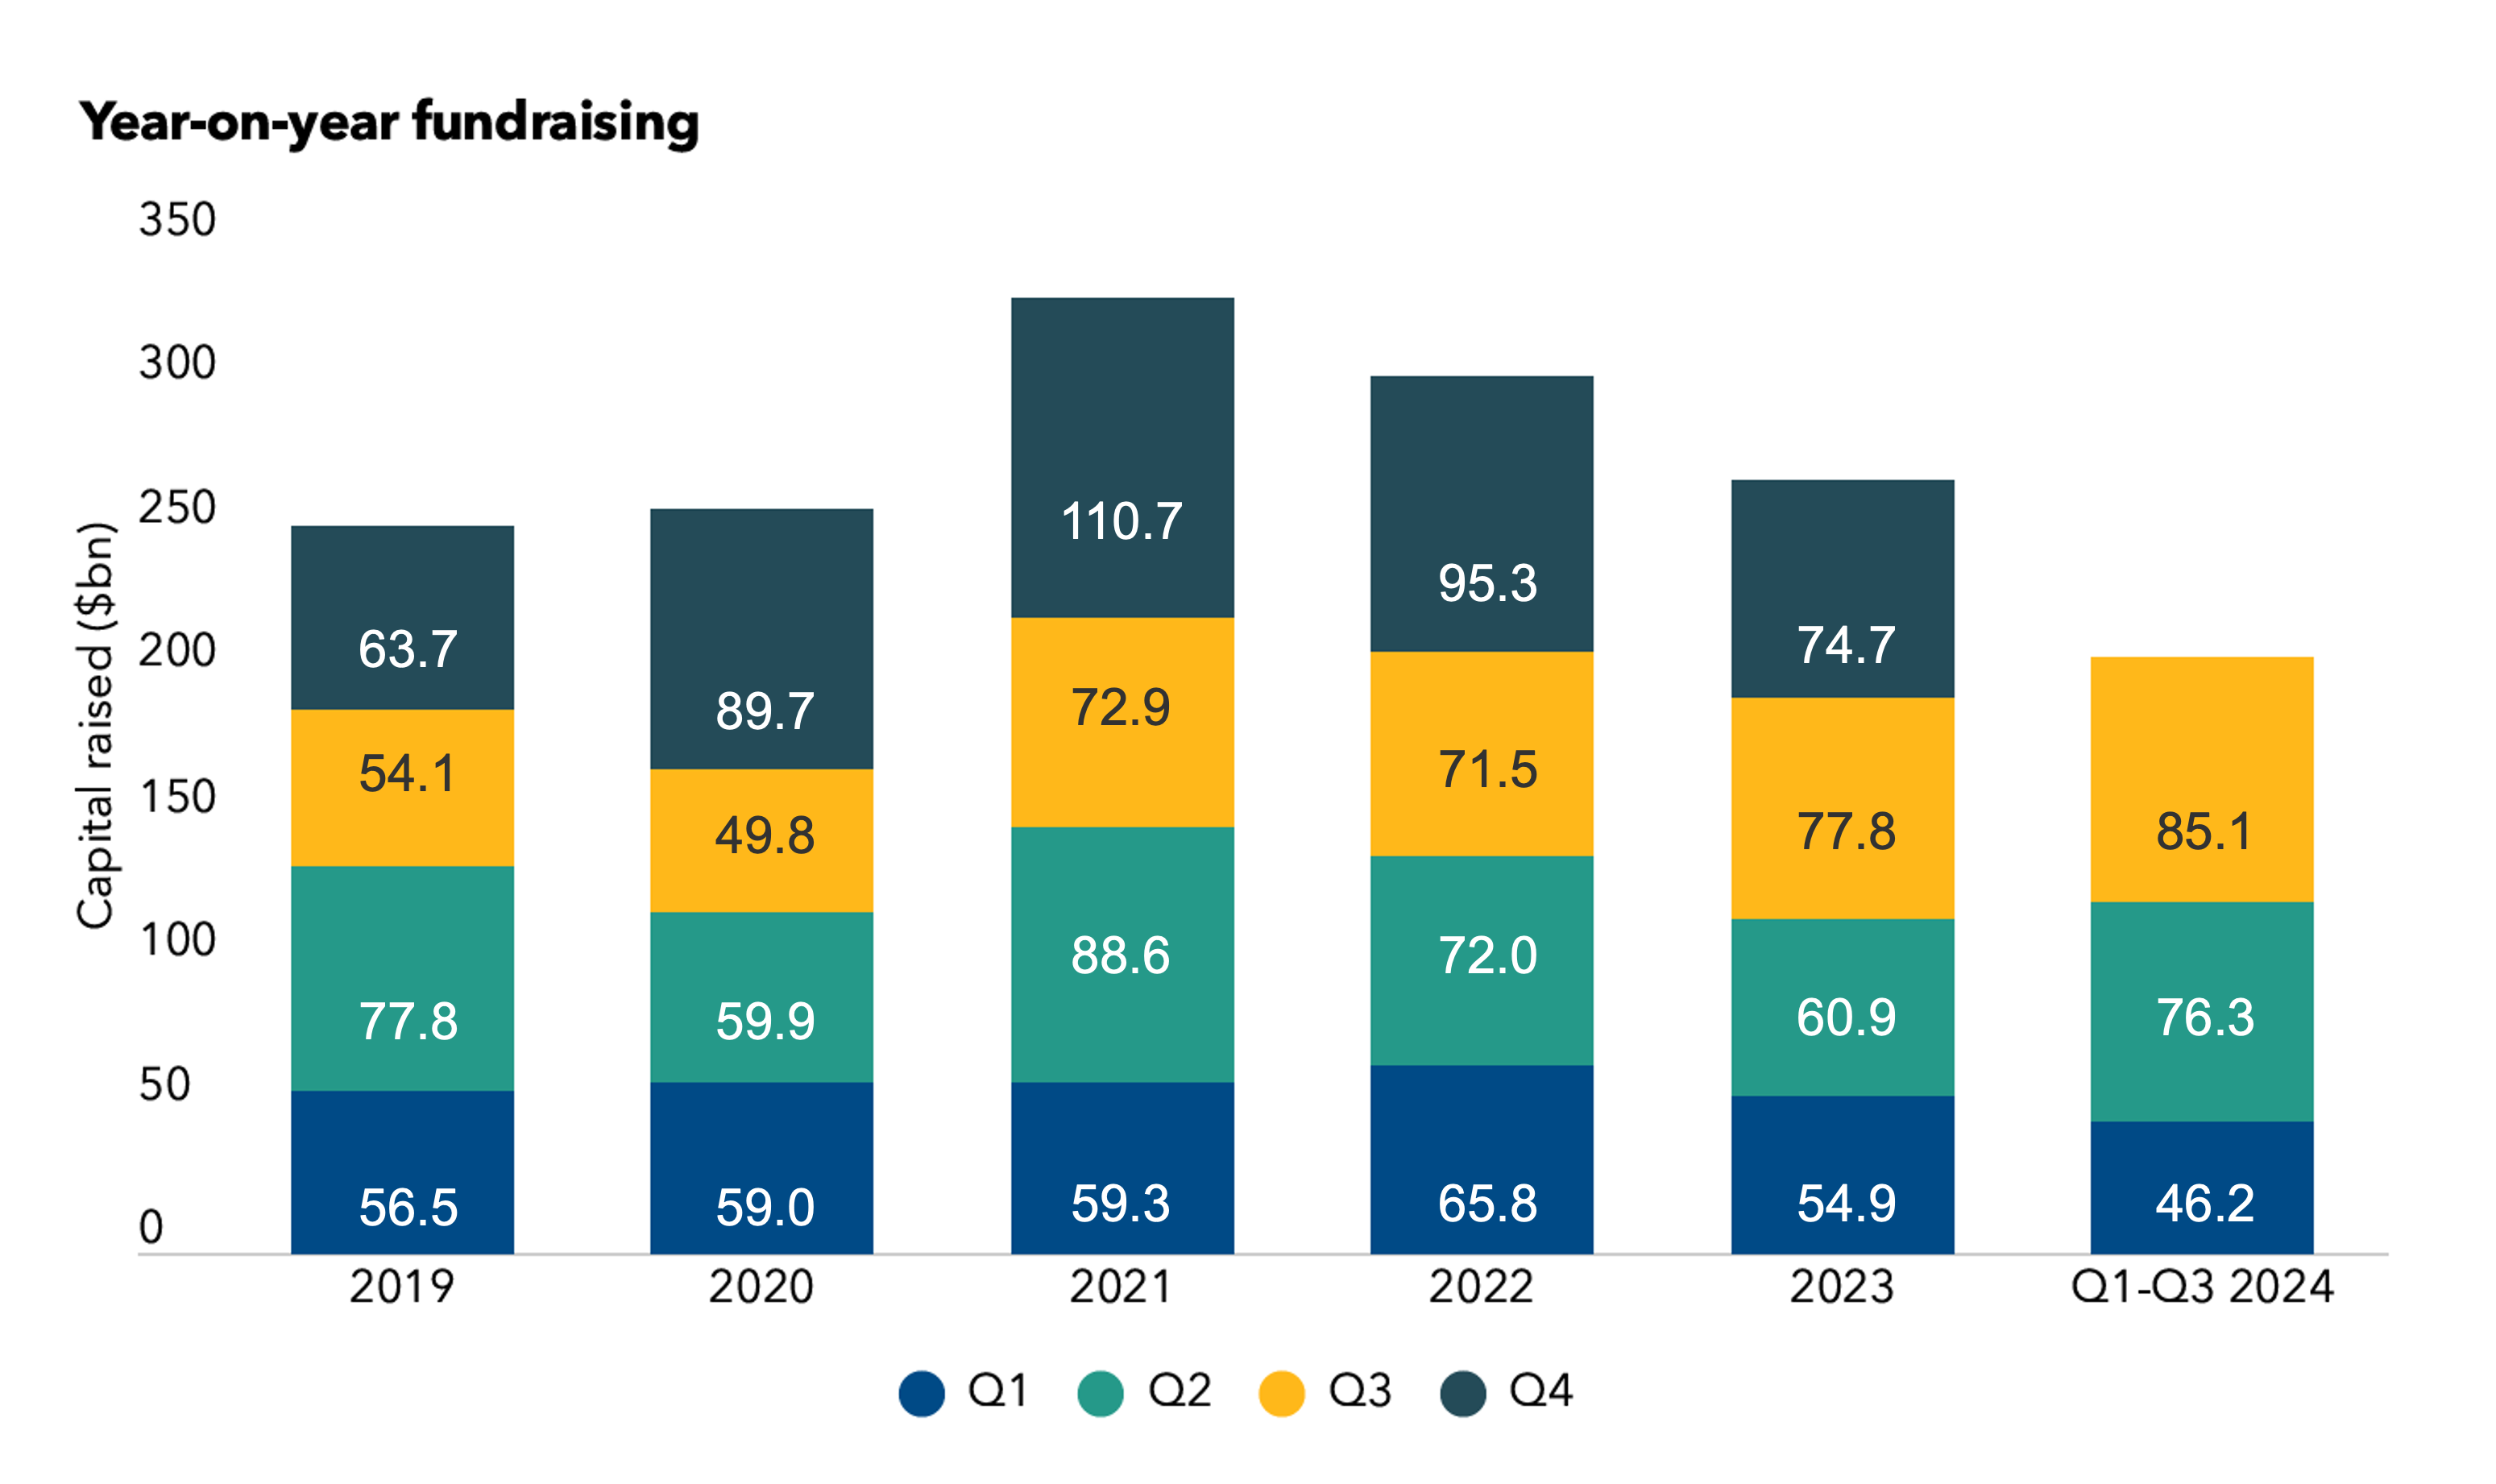
After a tough first quarter, private debt fundraising has picked up the pace through the rest of 2024 to end Q3 slightly ahead of the equivalent period in 2023 – see a selection of charts here. Q3 saw a total of $85.1 billion raised, the largest Q3 total in our sample. The total to the end of September reached $207.6 billion, up from $193.6 billion in the same period of 2023.
The recovery in private debt fundraising has been heavily driven by the popularity of senior debt funds, which make up a huge 65 percent of capital raised in 2024 so far. A more typical proportion has been around 40 percent in the past five years. Subordinated and mezzanine funds have been the main casualty, making up just 16 percent of funds raised while distressed debt is also down at just 11 percent.
For several years the industry has been trending towards larger funds and 2024 is no exception, with the average vehicle size for the year well above the $1 billion mark at $1.18 billion. This has been driven by some very large fund closes in 2024. Four vehicles have closed on more than $10 billion, led by ICG’s Senior Debt Partners Fund V on $17 billion.
North America continues to dominate in terms of capital raised – it is set to end the year well above $100 billion. However, Europe has seen a rebound in activity following a difficult start to the year, with $56.7 billion raised so far.
The number of funds reaching their targets has fallen during 2024, with the highest number of funds failing to reach their targets since 2020 when the impact of covid-19 was being felt on fundraising. More than one-third of funds have closed above target however, well above the level seen in 2020, as larger managers benefit from significant oversubscriptions to their funds.
A huge majority of fundraising is for corporate private credit, which has risen to 85 percent in 2024. Real estate has historically been the second most popular sector, and remains so, but has fallen off drastically as the sector is hit by challenging market conditions.




Latest news

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…

LevFin Issuance Slows Across Products in August; DCM Remains a Bright Spot
The leveraged capital markets business continued to decelerate from just about every aspect, even for August standards. Overall issuance (including…