


No-one should expect a sudden 2008-style surge, but economic headwinds are expected to eventually translate to a promising opportunity set.
Non-performing loans have been one of the hottest topics in the private debt space ever since the 2008 financial crisis led to an unprecedented movement of bad debts off bank balance sheets. While the market has calmed in the years since, recent developments may see a resurgence in the NPL sector over the next few years.
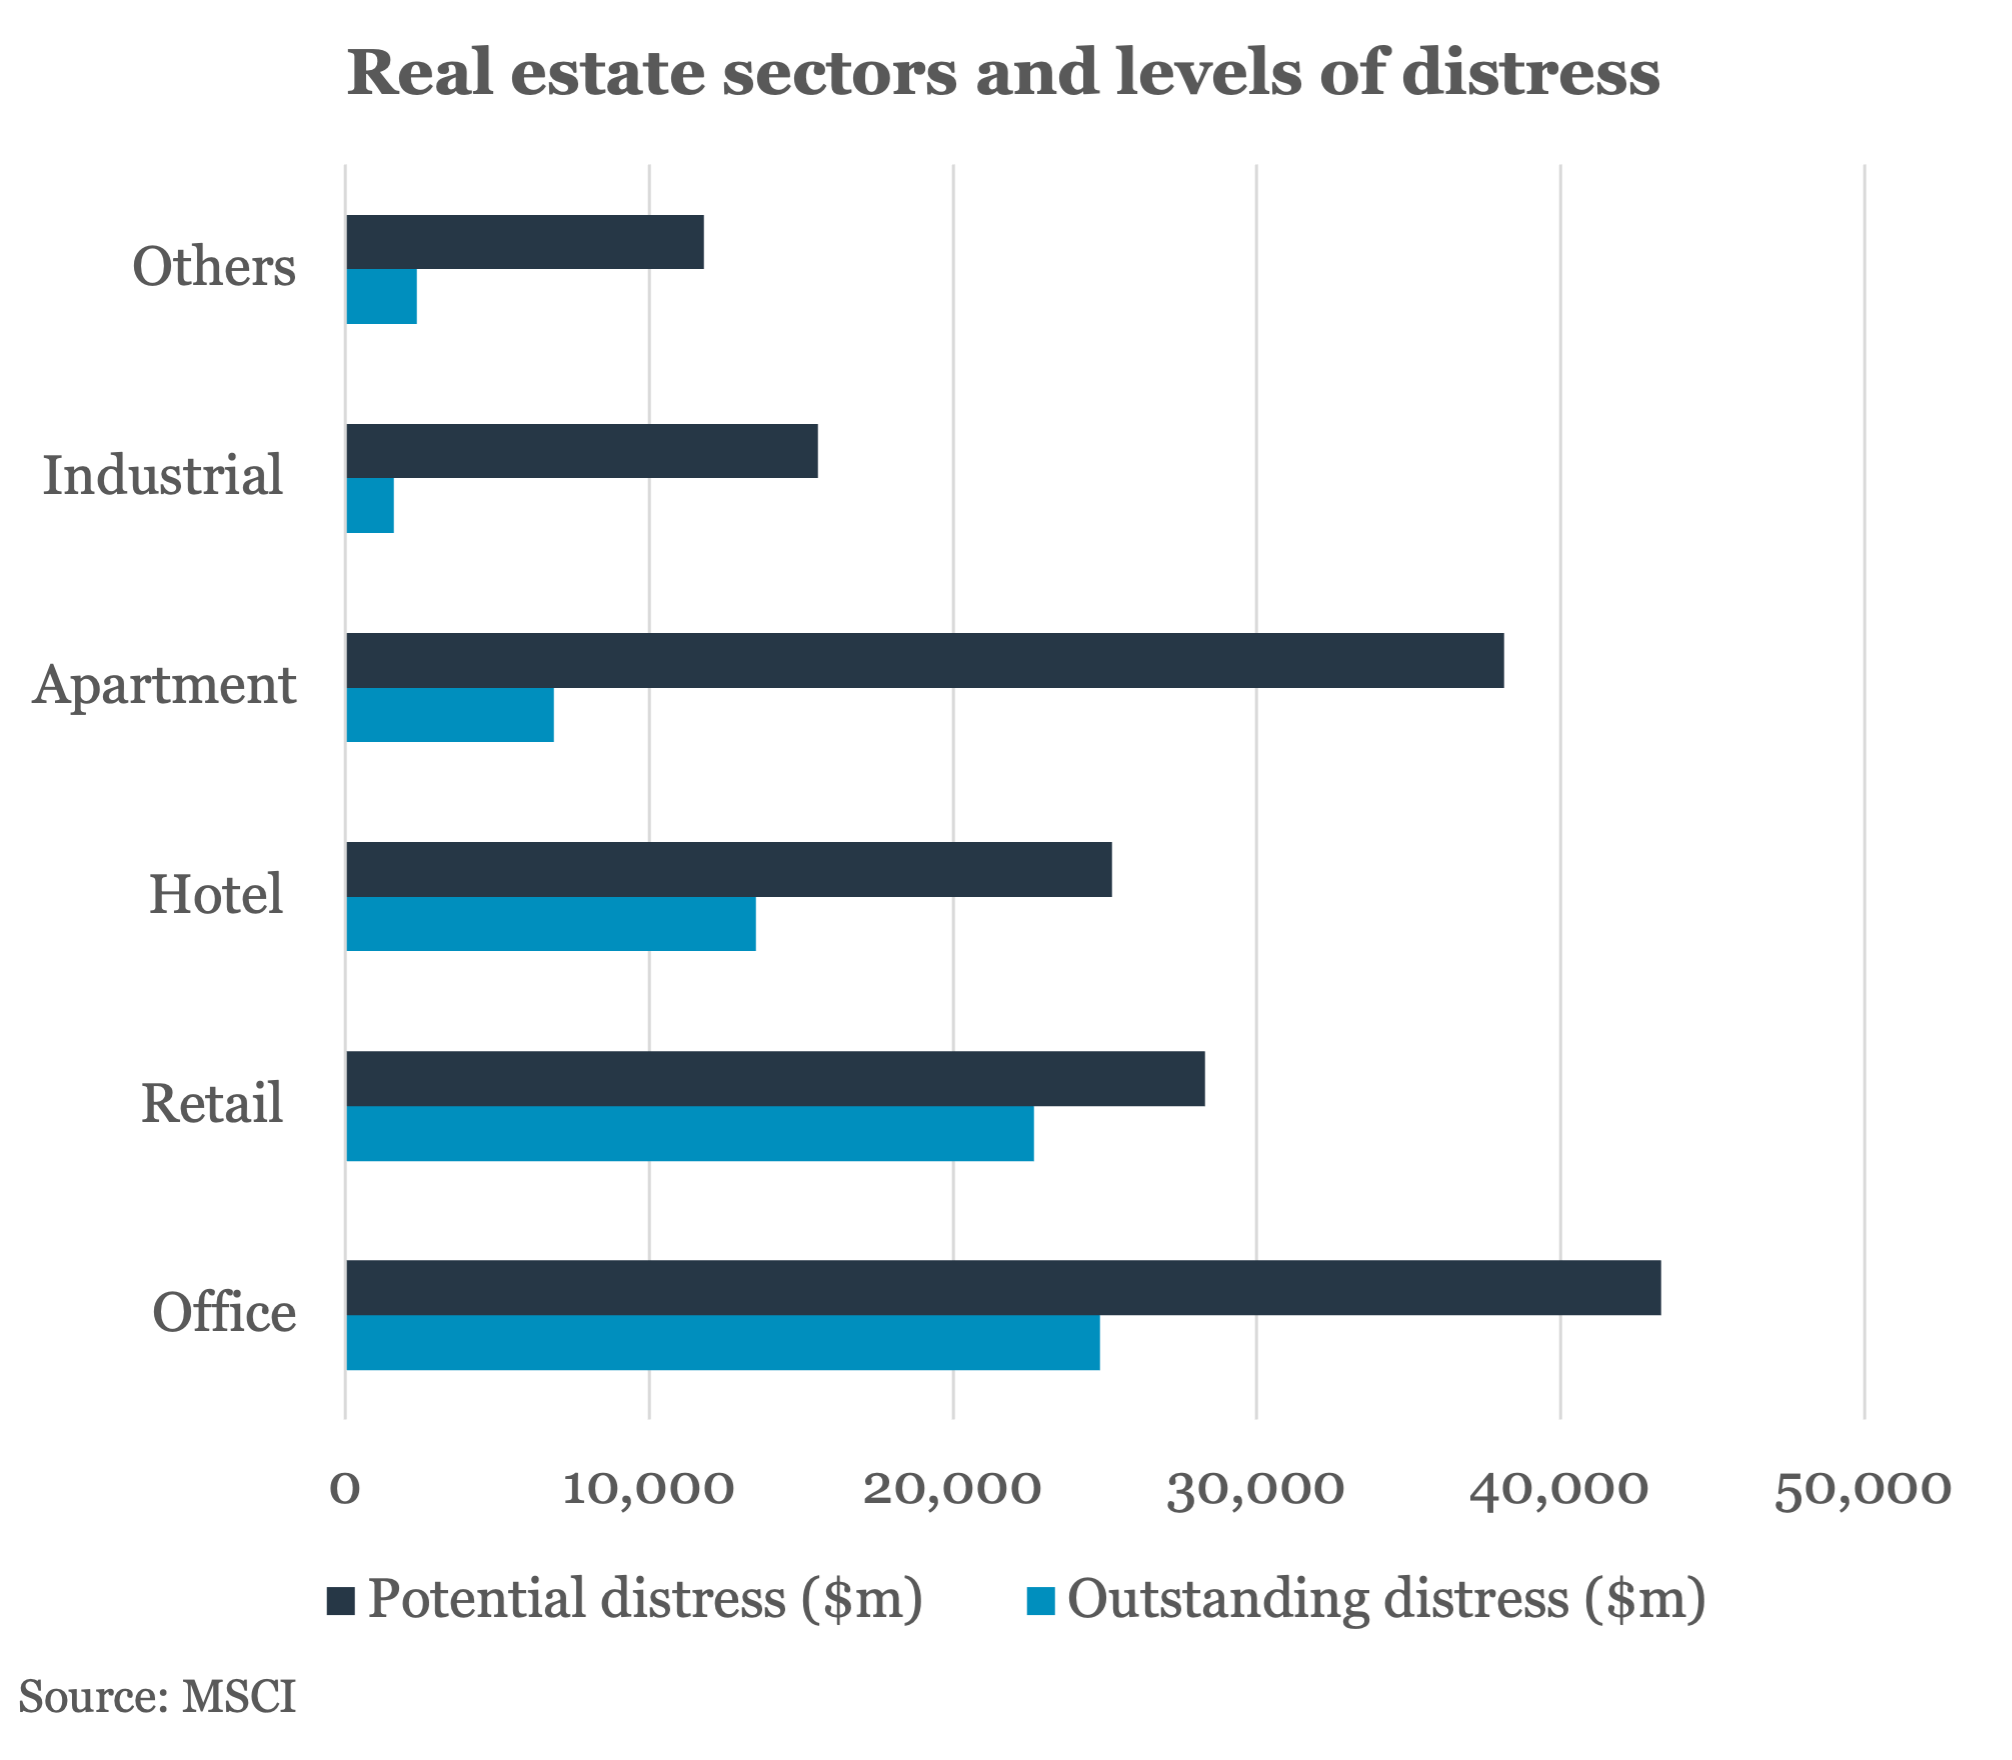
In the real estate market especially (see chart), delinquencies are expected to trend up rapidly in a v-shaped curve as debtors face increased pressures from the end of covid measures as well as inflation and much higher interest rates. Though market observers do not expect the surge to be anything like what was seen in 2008, it is likely to present a significant opportunity set for NPL investors in the coming years.
The US residential mortgage market is huge at around $12 trillion. Even if delinquencies only increased by 30 basis points, that’s still a very large increase in the opportunity set for buyers of NPLs.
However, it may take some time before the effects of current macroeconomic headwinds fully feed through into the market, says Jeffrey Thuringer, partner and head of business investments at NPL specialist Hyland Hill Investment Partners.
“The NPL sales market takes time to develop, and we currently see that development underway,” says Thuringer. “The illiquid credit markets can be slow to fully reflect changes in economic conditions; they tend to be less responsive to rising interest rates, as debt can be either fixed or subject to interest rate hedges. Indeed, during the last cycle, CMBS defaults did not peak at 10.34 percent until 2012.”
Thuringer also mentions that there has not been a high inflation, high interest rate cycle since the 1970s, meaning very few investment professionals operating in the market today have experience
of working in this kind of environment, which is leading to further market uncertainty.
However, while it is expected the market will see a resurgence in NPLs, very different conditions to those in the wake of the GFC mean that experienced, specialist investors are likely to dominate and there will be fewer new entrants.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
