


As we moved from 50 fundraisers to 100 in our annual ranking, investor appetite for private debt has soared to new record levels.
This year, we published the PDI 100 ranking of private debt’s top fundraisers over a five-year period. Having started with the PDI 30, we progressed to the PDI 50 before making a decision that this year we would be able to justify doubling the size of our list.
This is testament to the growing scale of the asset class. In years gone by, the fundraising totals of those outside the top 50 would not have been sufficient to lend their inclusion much credibility. That’s far from the case now.
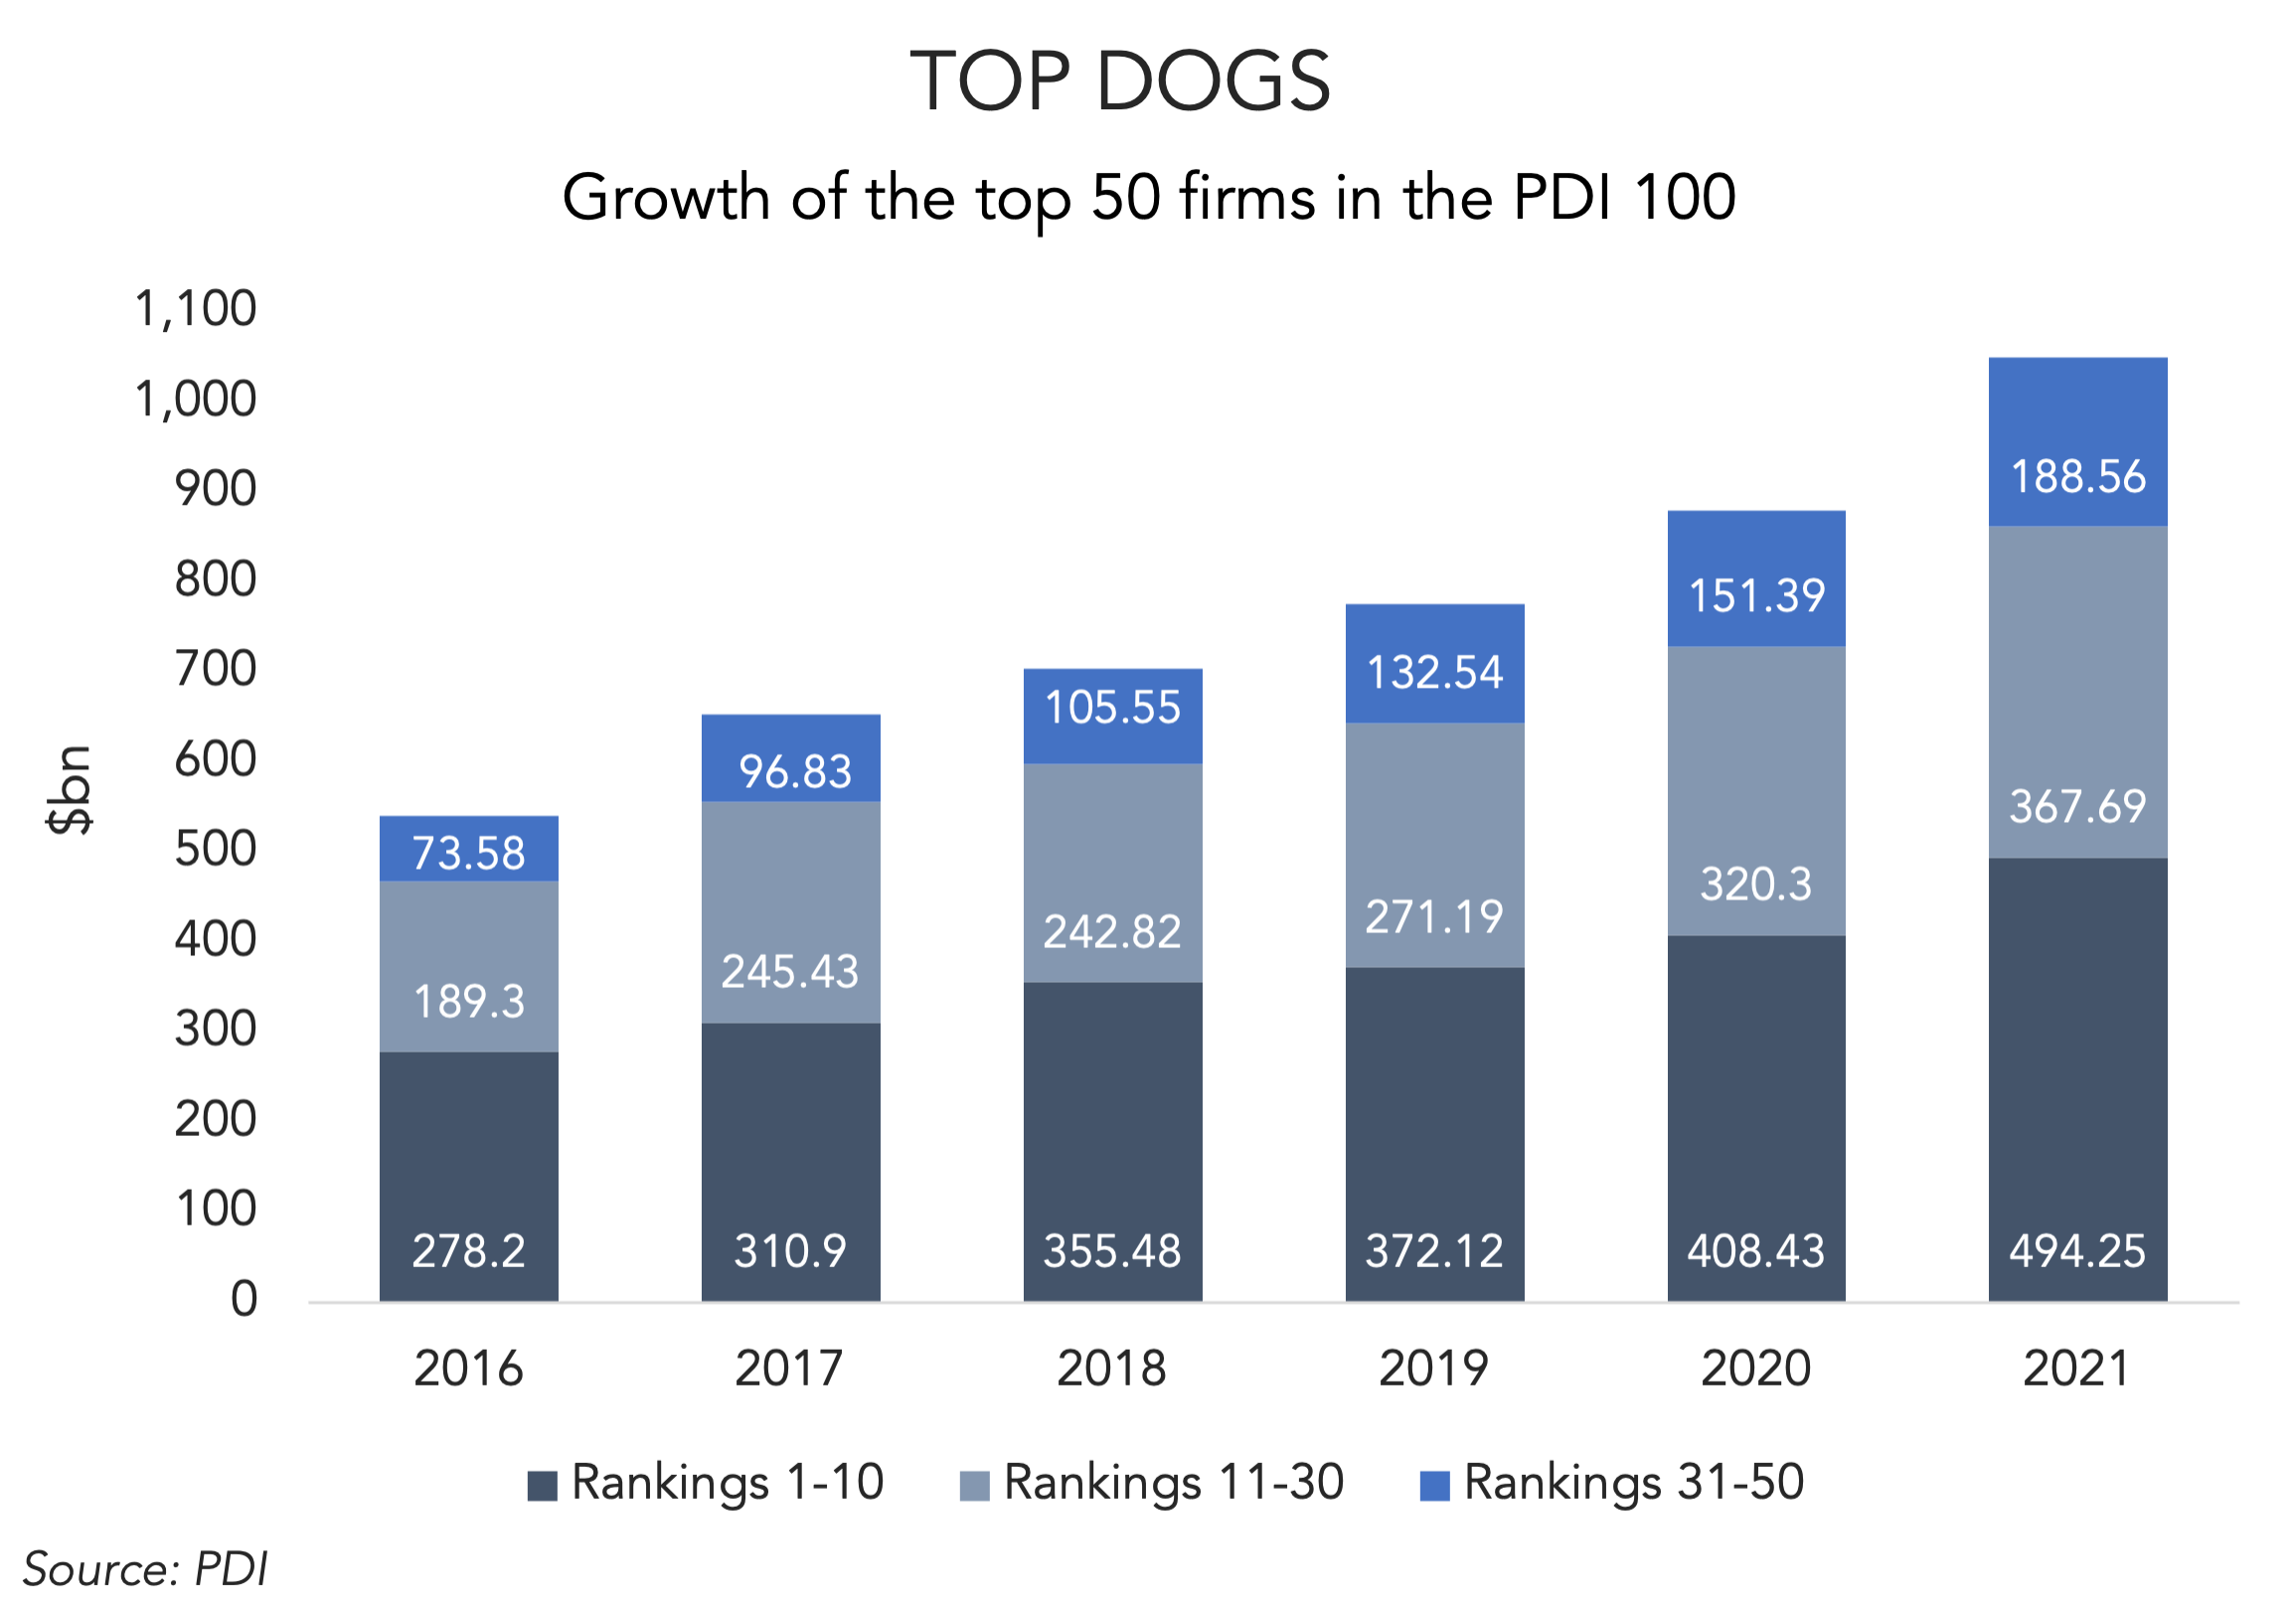
The capital raised overall this time around is approximately $1.3 trillion, with more than $1 trillion accounted for by the top 50. This is a ground-breaking figure which has been achieved despite the covid-induced difficulties which fundraisers have faced since the spring of 2020. The initial assumption was that investors would be very hesitant to make new commitments when they couldn’t meet managers face to face.
But their appetite for the asset class does not appear to have eased in the slightest, and this year’s trillion-busting total is well in excess of the $880 billion figure recorded at this time last year. Indeed, every successive year of our ranking has seen a steady increase in capital inflows. In our first PDI 30 ranking nine years ago, the total raised was a relatively modest $322 billion. In more recent years we saw the total climb to $700 billion in 2018 and $775 billion in 2019.
For the next 12 months, the fundraising outlook looks set fair. A more inflationary environment brings with it potential concerns for some areas of investment and opportunities for others. But overall, the appetite for private debt remains as strong as ever. New records look likely to be set in 2022.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
