


A surprising number of private markets managers don’t offer a break to their funds’ earliest investors.
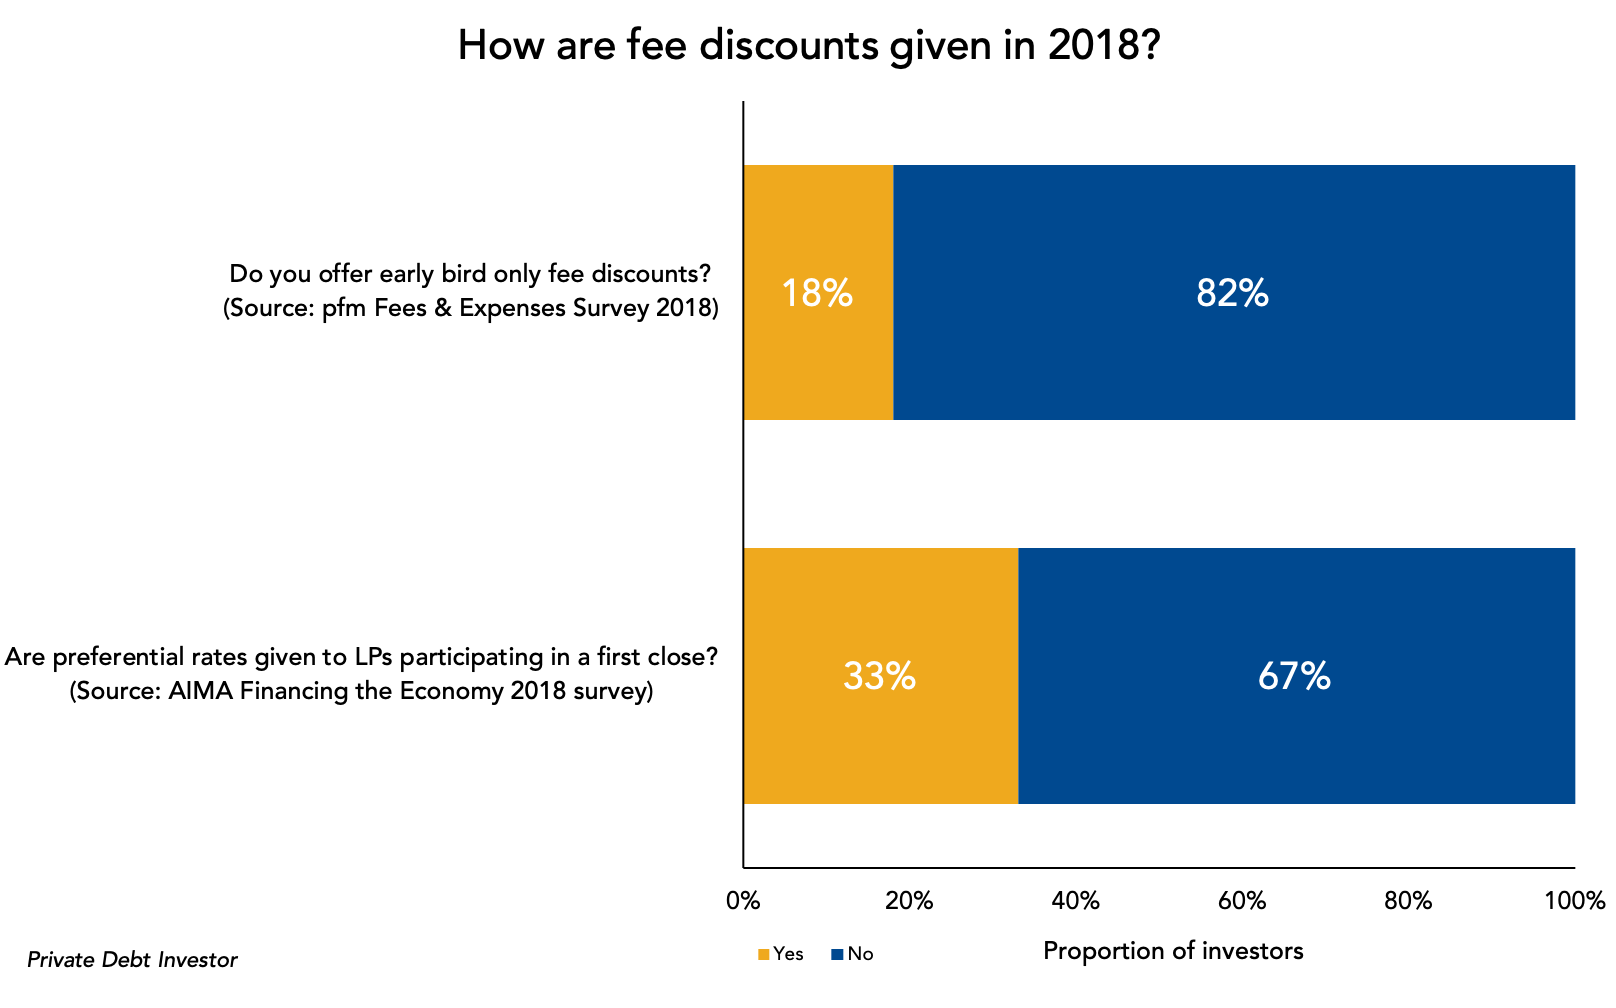
Private fund managers seem reticent to offer early-bird management fee discounts, according to two new surveys, closing a potential avenue to differentiate themselves as fundraising slows down.
Private Debt Investor sister publication pfm found in a fees-and-expenses survey that 33 percent of respondents offered discounts to limited partners participating in first closes. Those firms participating in the survey tilted heavily toward private equity firms, with 81 percent of respondents identifying themselves as an equity-based strategy or part of a diversified platform.
On Tuesday, a separate survey from the Alternative Investment Management Association showed that 18 percent of private credit managers offer discounts to LPs that take part in a vehicle’s initial closing. Those answering the survey’s queries were explicitly private debt managers.
LPs have told PDI and said in surveys that fees aren’t necessarily top of mind; often track record and firm personnel are among the most important factors. But in an era where fundraising is slowing down, or at least reverting to the mean – managers raised $159.26 billion in the first three quarters of 2017, compared to just $88.57 billion in the first nine months of 2018 – managers might think of simple measures that could sway LPs.




Latest news

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Reading the Board
The story changes depending on which numbers you’re counting.
Private Credit Defaults 101: Scrambling for Par
Seve Ballesteros won four majors in the 1980s despite being, by his own admission, one of the wildest drivers of the golf ball on tour.