


The biggest question isn’t around whether LPs want more GP relationships. The question is, is this good for first-time managers?
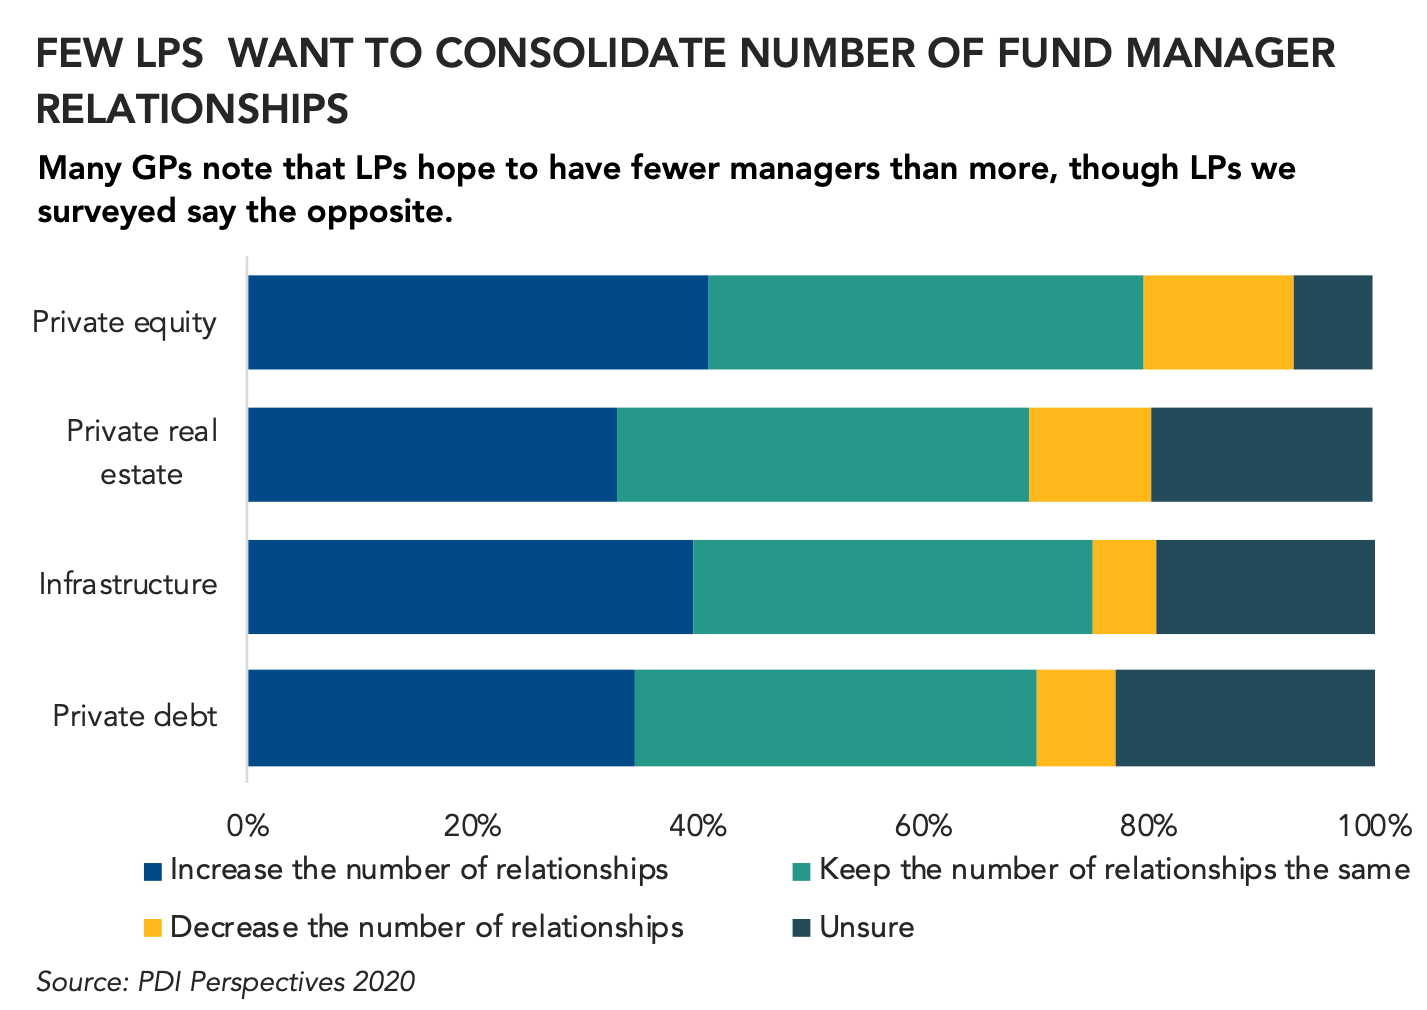
In a data set that could be rather friendly to first-time managers, almost five times as many investors want to increase the number of GPs they work with than reduce that figure, according to PDI Perspectives 2020, our LP survey.
Some 34 percent of investors said they hope to build out their credit portfolio with more managers, compared with 7 percent saying the opposite. High-profile partnerships among large pension funds, like those that the Texas Teachers’ Retirement System holds with KKR and Apollo Global Management, have been examples of LPs consolidating their GP relationships.
Not all LPs carry the heft of the Lone Star State’s TRS, though, and smaller pension funds may not have the capacity to write a check large enough to encompass multiple strategies. In addition, smaller LPs and late comers to the asset class are still building out their portfolio, as shown in many of the public pension allocation plans.
Elsewhere in our survey, half of managers showed a willingness to invest in first-time funds, either through a defined allocation or opportunistically, and some had plans to do allocate to maiden vehicles in the future. Despite the well-documented inflow of capital to private debt, there may just be room for more at the table.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
