


New GPs face a tough task to attract investor interest, but there are ways of maximising prospects.
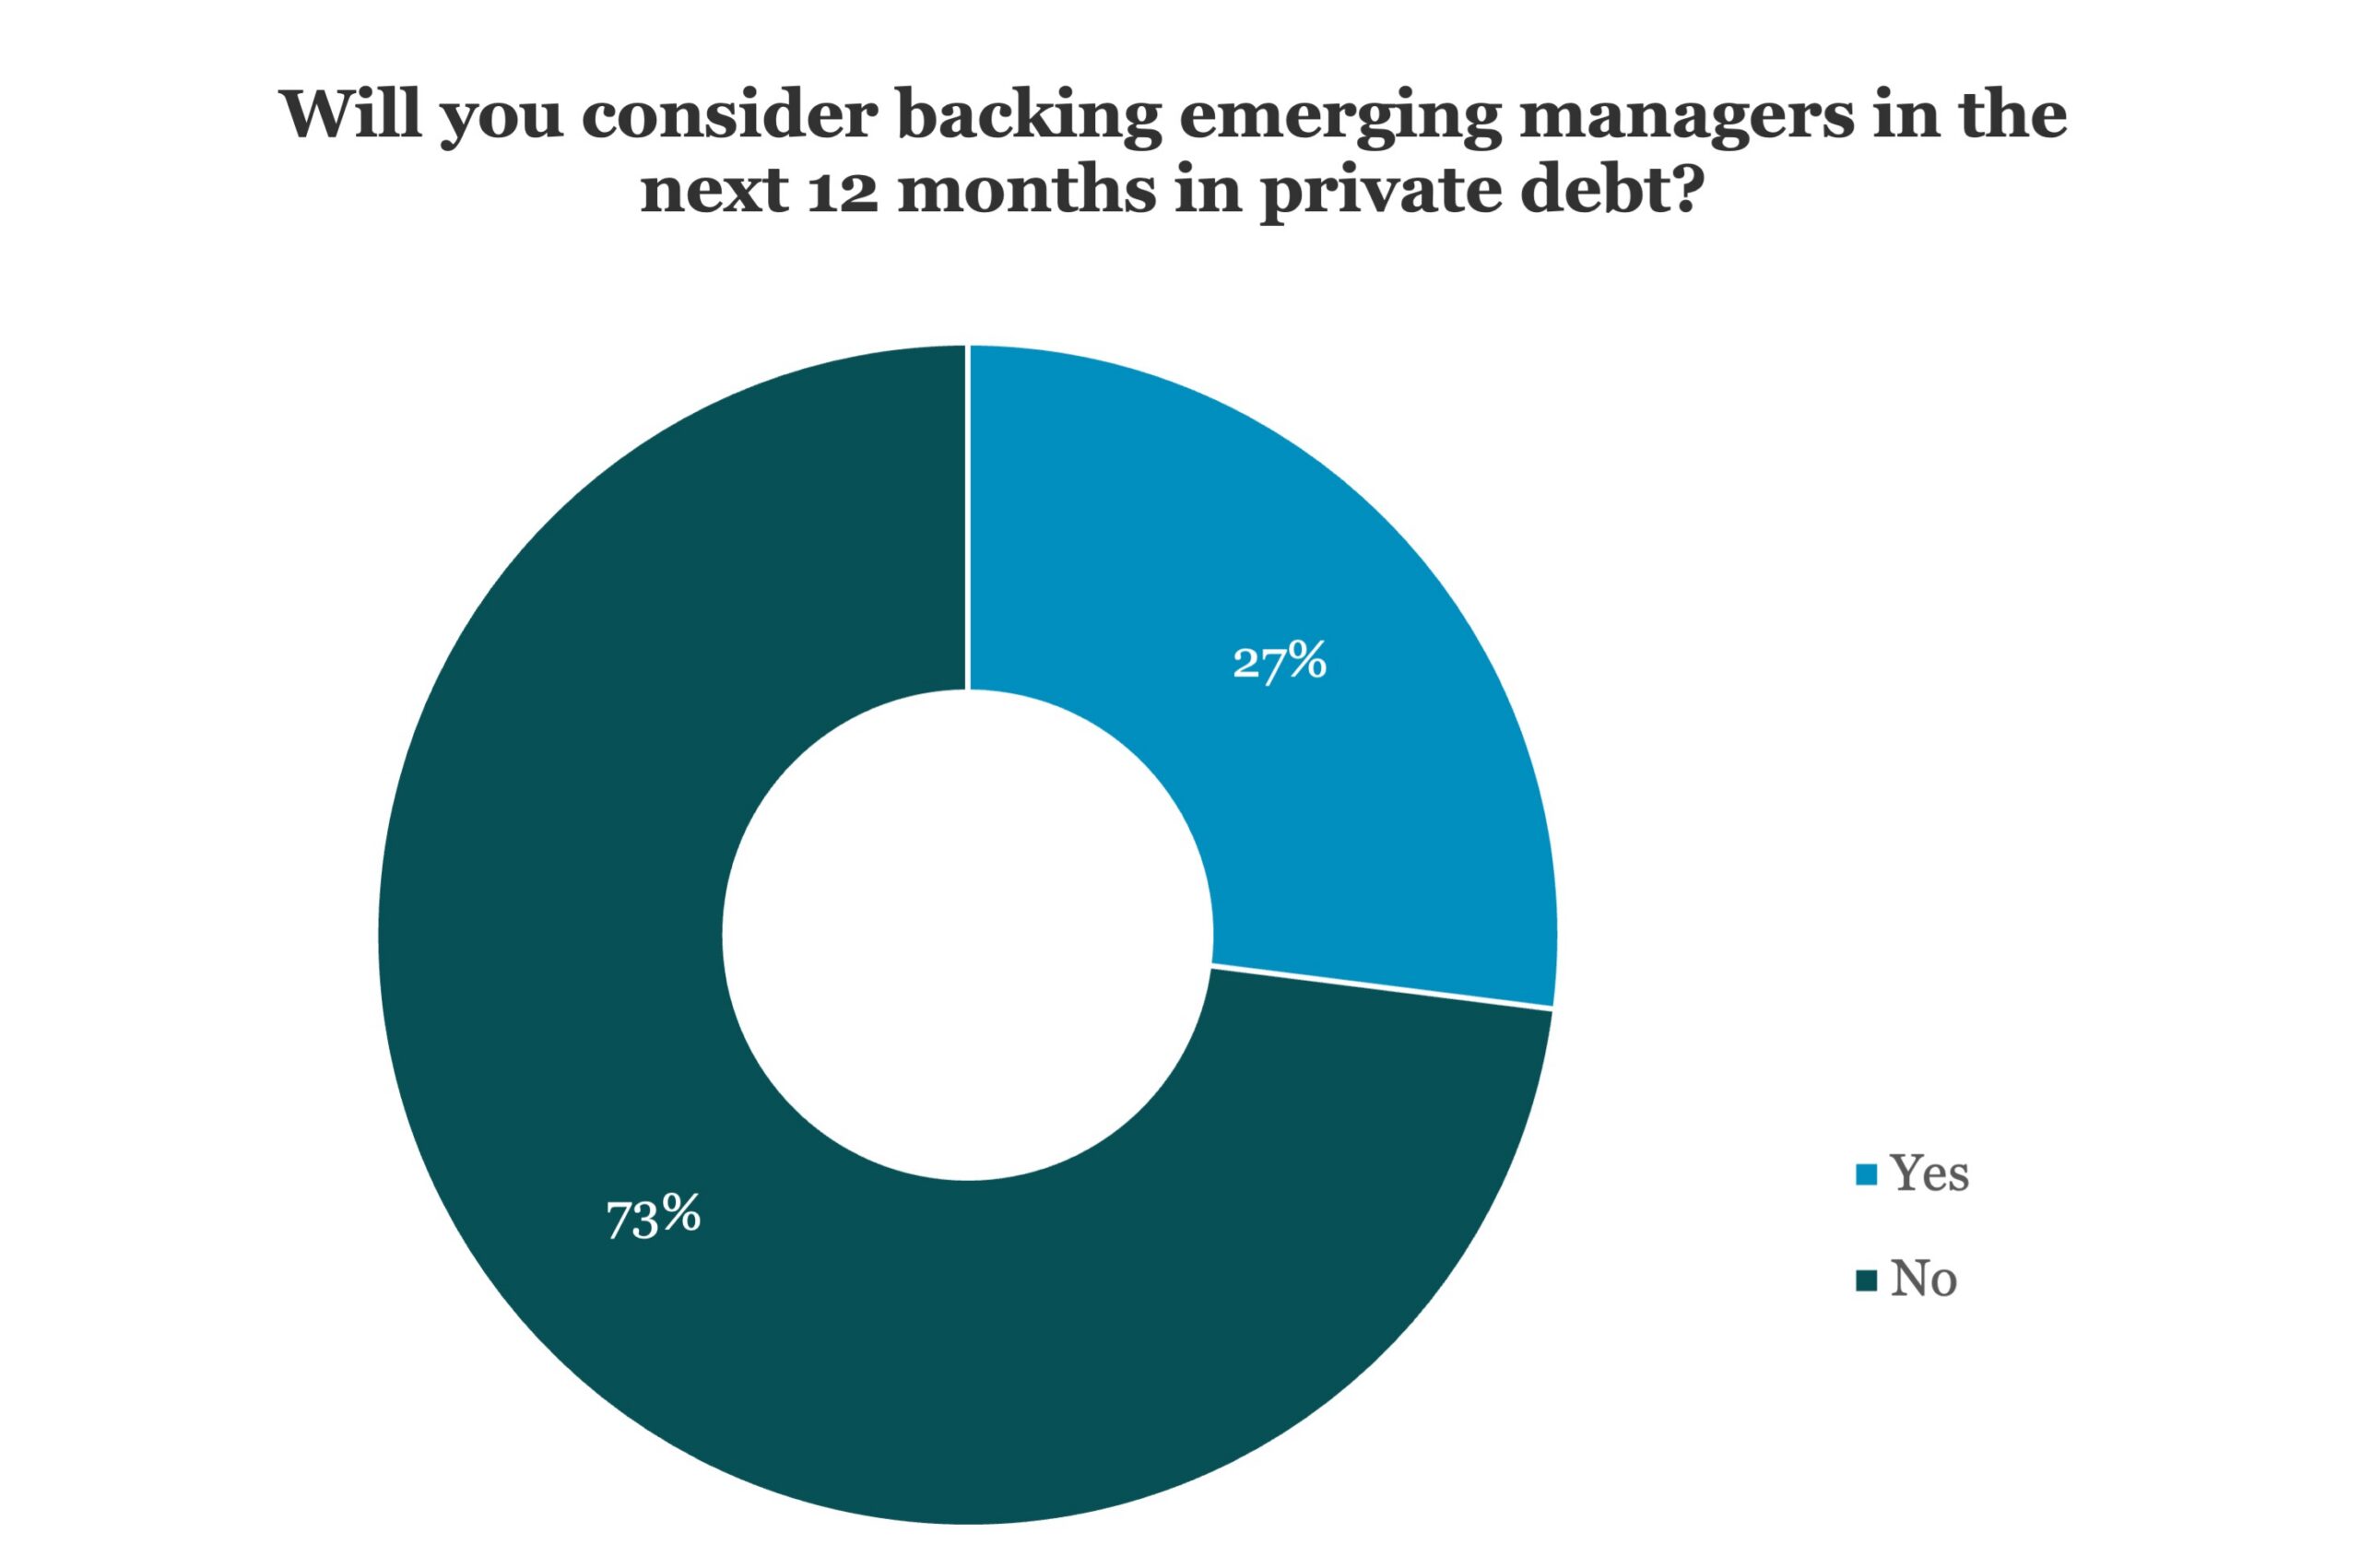
It feels somewhat Scrooge-like to point it out at this time of year but, for emerging managers, goodwill appears to be in short supply. In our LP Perspectives study – to be published early next year – we found 73 percent of investors saying they would not consider backing emerging managers in the next 12 months.
In a way, this is not too surprising. After all, private debt has developed a reputation as an asset class where the biggest managers attract a vastly disproportionate amount of overall capital allocation. Those new to the market might be forgiven for giving up even before they hit the fundraising trail.
But for those with a thick skin who decide to press ahead, panellists at our New York Forum earlier this year had some words of advice. One is to be careful how you market yourself – you may want to create a sense of uniqueness to give an allocator a reason to make room for you, but at the same time you should avoid placing yourself too far outside the comfort zone.
There is a benefit to forming relationships with allocators as early as possible. Many have a very fixed allocation schedule – meaning they know (possibly years in advance) which managers they are happy to reinvest in, when those managers are coming back to market and with who they will be making co-investments. To wedge yourself into the mix as an emerging manager requires determination and persistence – possibly offering the allocator research and thought leadership on your target market, just to catch their interest if nothing else.
Given the challenges associated with traditional fundraising for debut funds, a more realistic option is likely to be raising funds on a deal-by-deal basis in the formative period. Once transactions have been completed, managers can take a proactive stance with allocators by demonstrating how they have solved problems for borrowers that others couldn’t.
There is much talk around the maturity of corporate lending allocations and how this is prompting investors to take a more broad-minded approach to their strategic choices within the asset class. This should provide some encouragement for emerging managers despite the stern challenges they will no doubt face in forging a place for themselves in the market.




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…