


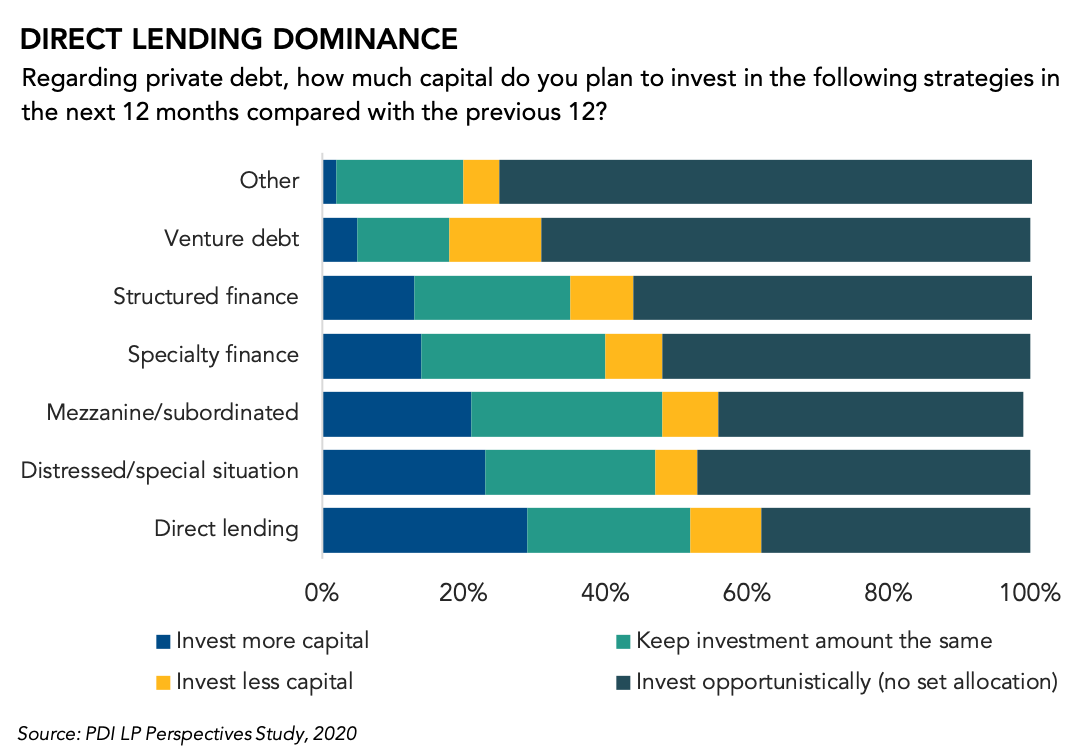
A plurality of LPs plan on committing more to the strategy than any other credit product, our annual investor poll found.
More covenant headroom, wider credit spreads and a mountain of capital: that’s how LPs view not just for the upper mid-market or the broadly syndicated market, but all segments of mid-market finance.
Even so, they continue to embrace the strategy, as our annual LP survey, PDI Perspectives 2020, found once again. When asked about an array of credit strategies and investment plans in the coming year, a plurality of respondents said they plan to deploy more capital into direct lending.
As we come to the end of the market cycle, direct lenders are sitting in a prime position. When credit markets freeze up, spreads will gap out and documents will become tighter. It’s what is being done now though that gives some pause.
The appeal of the strategy, most closely associated with senior debt, is clear. It’s a yield play, comes with the inherent protection of being first in the repayment pecking order and an illiquidity premium makes up for the non-tradeable nature of the position.
Multiple European LPs at our PDI Capital Structure Forum in London voiced scepticism of the strategy’s risk-adjusted return. Investors may get additional yield, but the question comes in whether the risks are worth that additional premium; for some the answer was no.



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.