


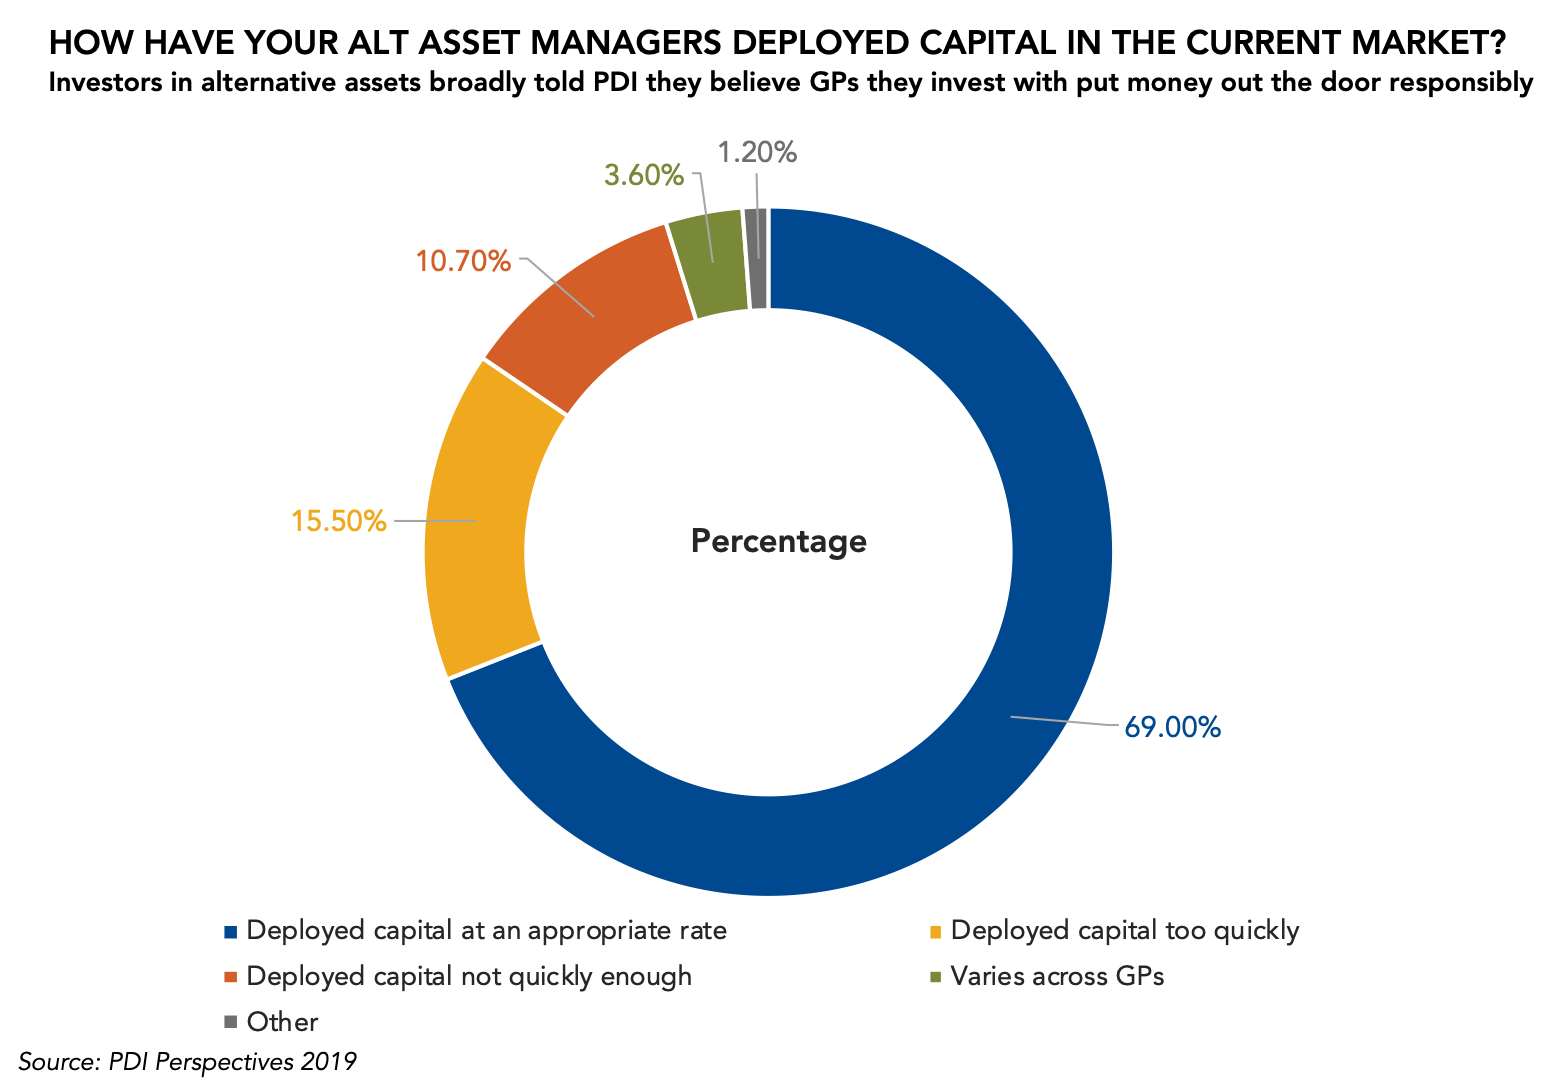
Despite heated discussion around perceived recklessness, most LPs are satisfied with how GPs have managed their capital.
Much has been made of the large number of covenant-lite loans, cases of egregious EBITDA addbacks and other such exuberant late-cycle activity.
But at least by one metric, limited partners are largely happy with how the alternative asset firms they invest with have deployed capital. In our year-end survey of investors, PDI Perspectives 2019, 69 percent of LPs said the managers they have committed money to have put it out the door at a reasonable pace given the current market conditions.
The datapoint is a vote of confidence that LPs believe they have chosen the right managers. Of course, the ultimate test will come once the cycle turns – how many loans will go into default, and what will recoveries be on rather permissive credit agreements? How many buyouts will go kaput, and will private equity funds put more money into portfolio companies?
But the seeds are sown now for what managers will reap in the next downturn, and the fact that LPs are largely happy with their GPs capital deployment pace now is a vote of confidence for how managers’ funds might do once choppier waters arrive.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
