


Looking back on capital accumulation in recent years, investor anticipation of distressed debt opportunities grew – sometimes without reason.
With distress a major talking point again, here are a few observations from a glance at our fundraising data:
Waiting for the wave: Much of the recent history of distressed debt fundraising has been about anticipating demand that never came. This reached its apotheosis in 2020 when a huge amount of dry powder was still waiting to be deployed from the peak fundraising years of 2017 ($82 billion) and 2019 ($68 billion). In the event, distress – and its close relative dislocation – proved to be a short-lived phenomenon. Barely had even small proportion of capital found a home before market confidence recovered and M&A activity hit boom levels in the second half of the year. Since then, distressed debt fundraising has remained at normalised levels.
Oaktree leads the way: Distressed and special situations specialist Oaktree Capital Management closed the biggest fund between 2019 and 2022 as its Opportunities Fund XI racked up an impressive $16 billion. This was more or less twice the amount raised by the second-largest fund, Lone Star’s $8.2 billion Fund XI. Some distressed funds have shown an ability to be significantly oversubscribed, with Ares Management’s Special Opportunities Fund II raising more than $7 billion versus a target of $4 billion; and Fortress Investment Group’s Credit Opportunities Fund V Expansion vehicle collecting $7 billion compared with a $3 billion target.
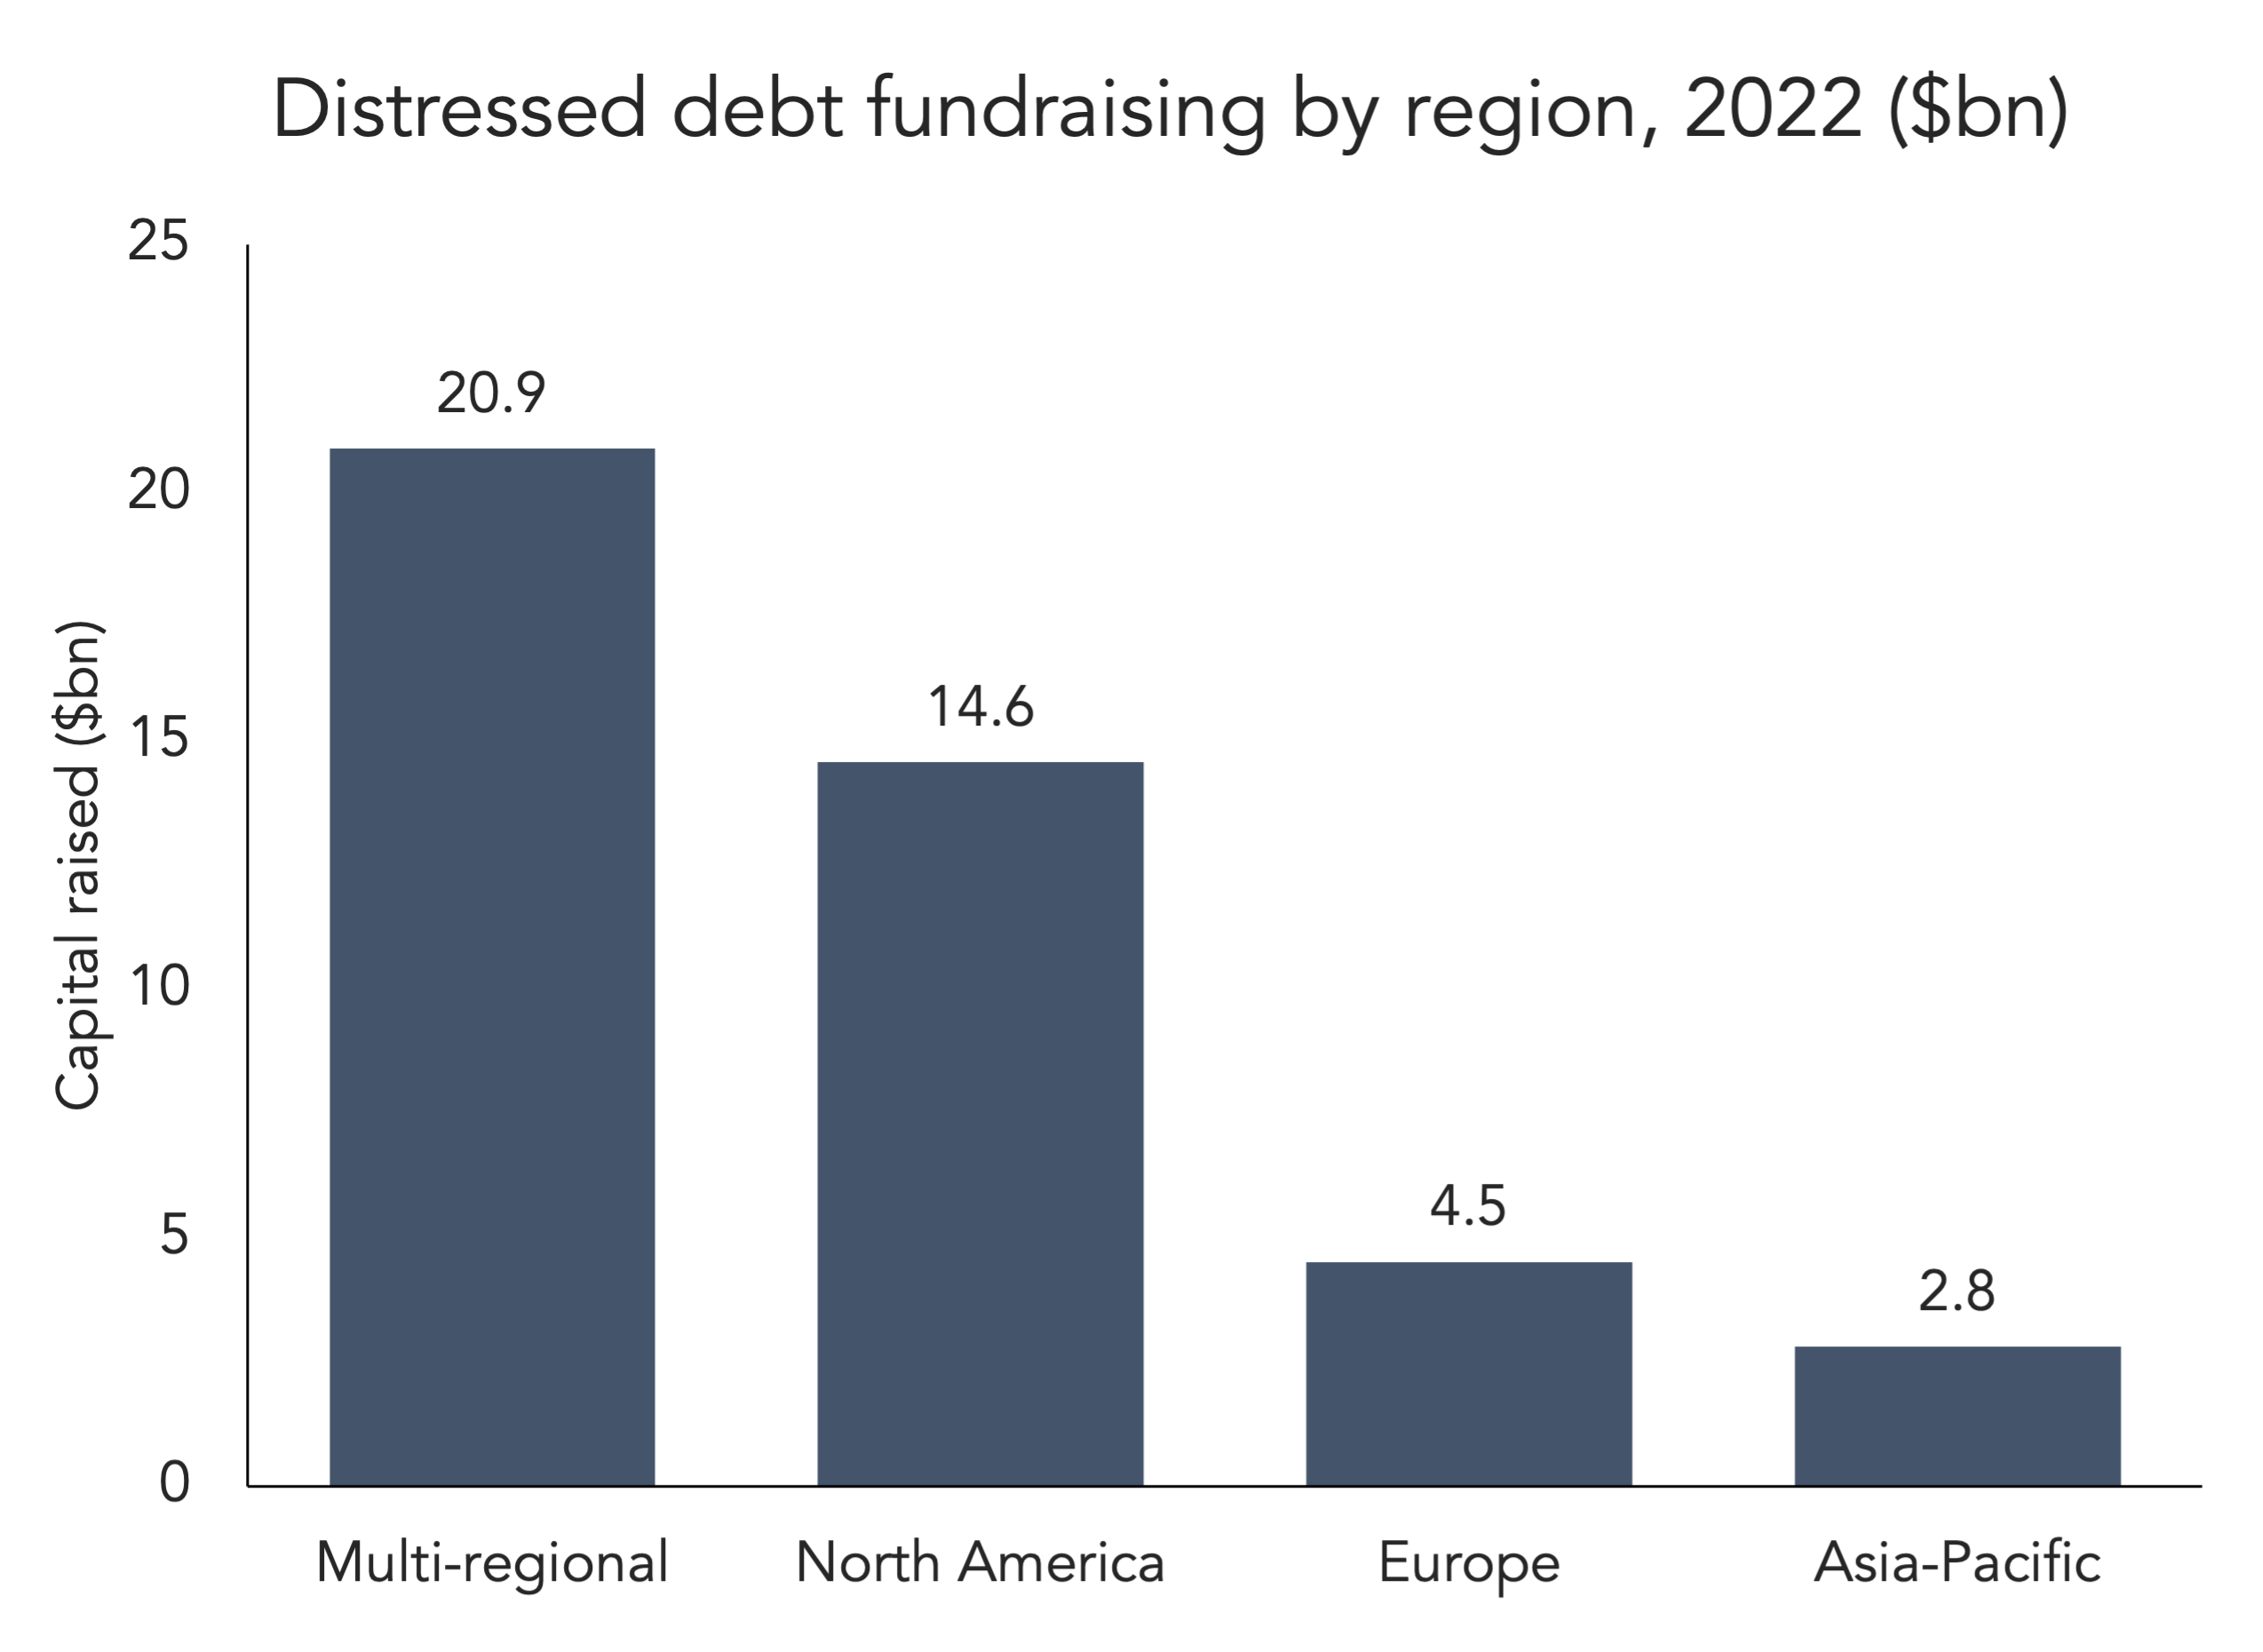
An uneven dispersion: Our data (see chart above) shows that, out of almost $43 billion raised for distressed debt last year, multi-regional and North American-focused strategies accounted for around $35 billion of the total. While Asia Pacific in general remains a relatively nascent region for private debt, the surprising finding here is that Europe accounted for only $4.5 billion. The explanation for this is not immediately obvious. Faced with economic difficulties and geopolitical strains, it seems likely that Europe will provide more than its fair share of distressed and special situations opportunities over the coming years. Perhaps this will be better reflected in the fundraising figures for the current year.
(Past performance is no guarantee of future results.)



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…