


After a brief period of change, deals are starting to look very similar to how they did pre-covid.
“It’s amazing how quickly the snap-back has happened,” said Richard Olson, a London-based managing director at investment bank Lincoln International, reflecting on how private debt deal terms have quickly reverted to the market standard that was seen prior to the global health crisis.
Private Debt Investor spoke with Olson following the publication by Lincoln’s portfolio valuations and opinions practice of its Q4 2020 valuations data focused on more than 260 private companies in the EU and the UK. The report found mid-market arrangement fees and equity cushions were back to pre-covid levels last month, while leverage was slightly reduced and margins increased.
“LPs are increasingly comfortable with the impact of covid,” Olson reflects. “Partly this is down to QE, with the buying of credits having supported the market. In addition, we have vaccination programmes being rolled out and infections easing, along with greater clarity on which sectors to avoid.”
Olson said there is a “risk on” approach, particularly in relation to add-on acquisitions but – while incremental leverage is being made available for these opportunities – managers are “not exceeding the level of risk in the original underwriting”.
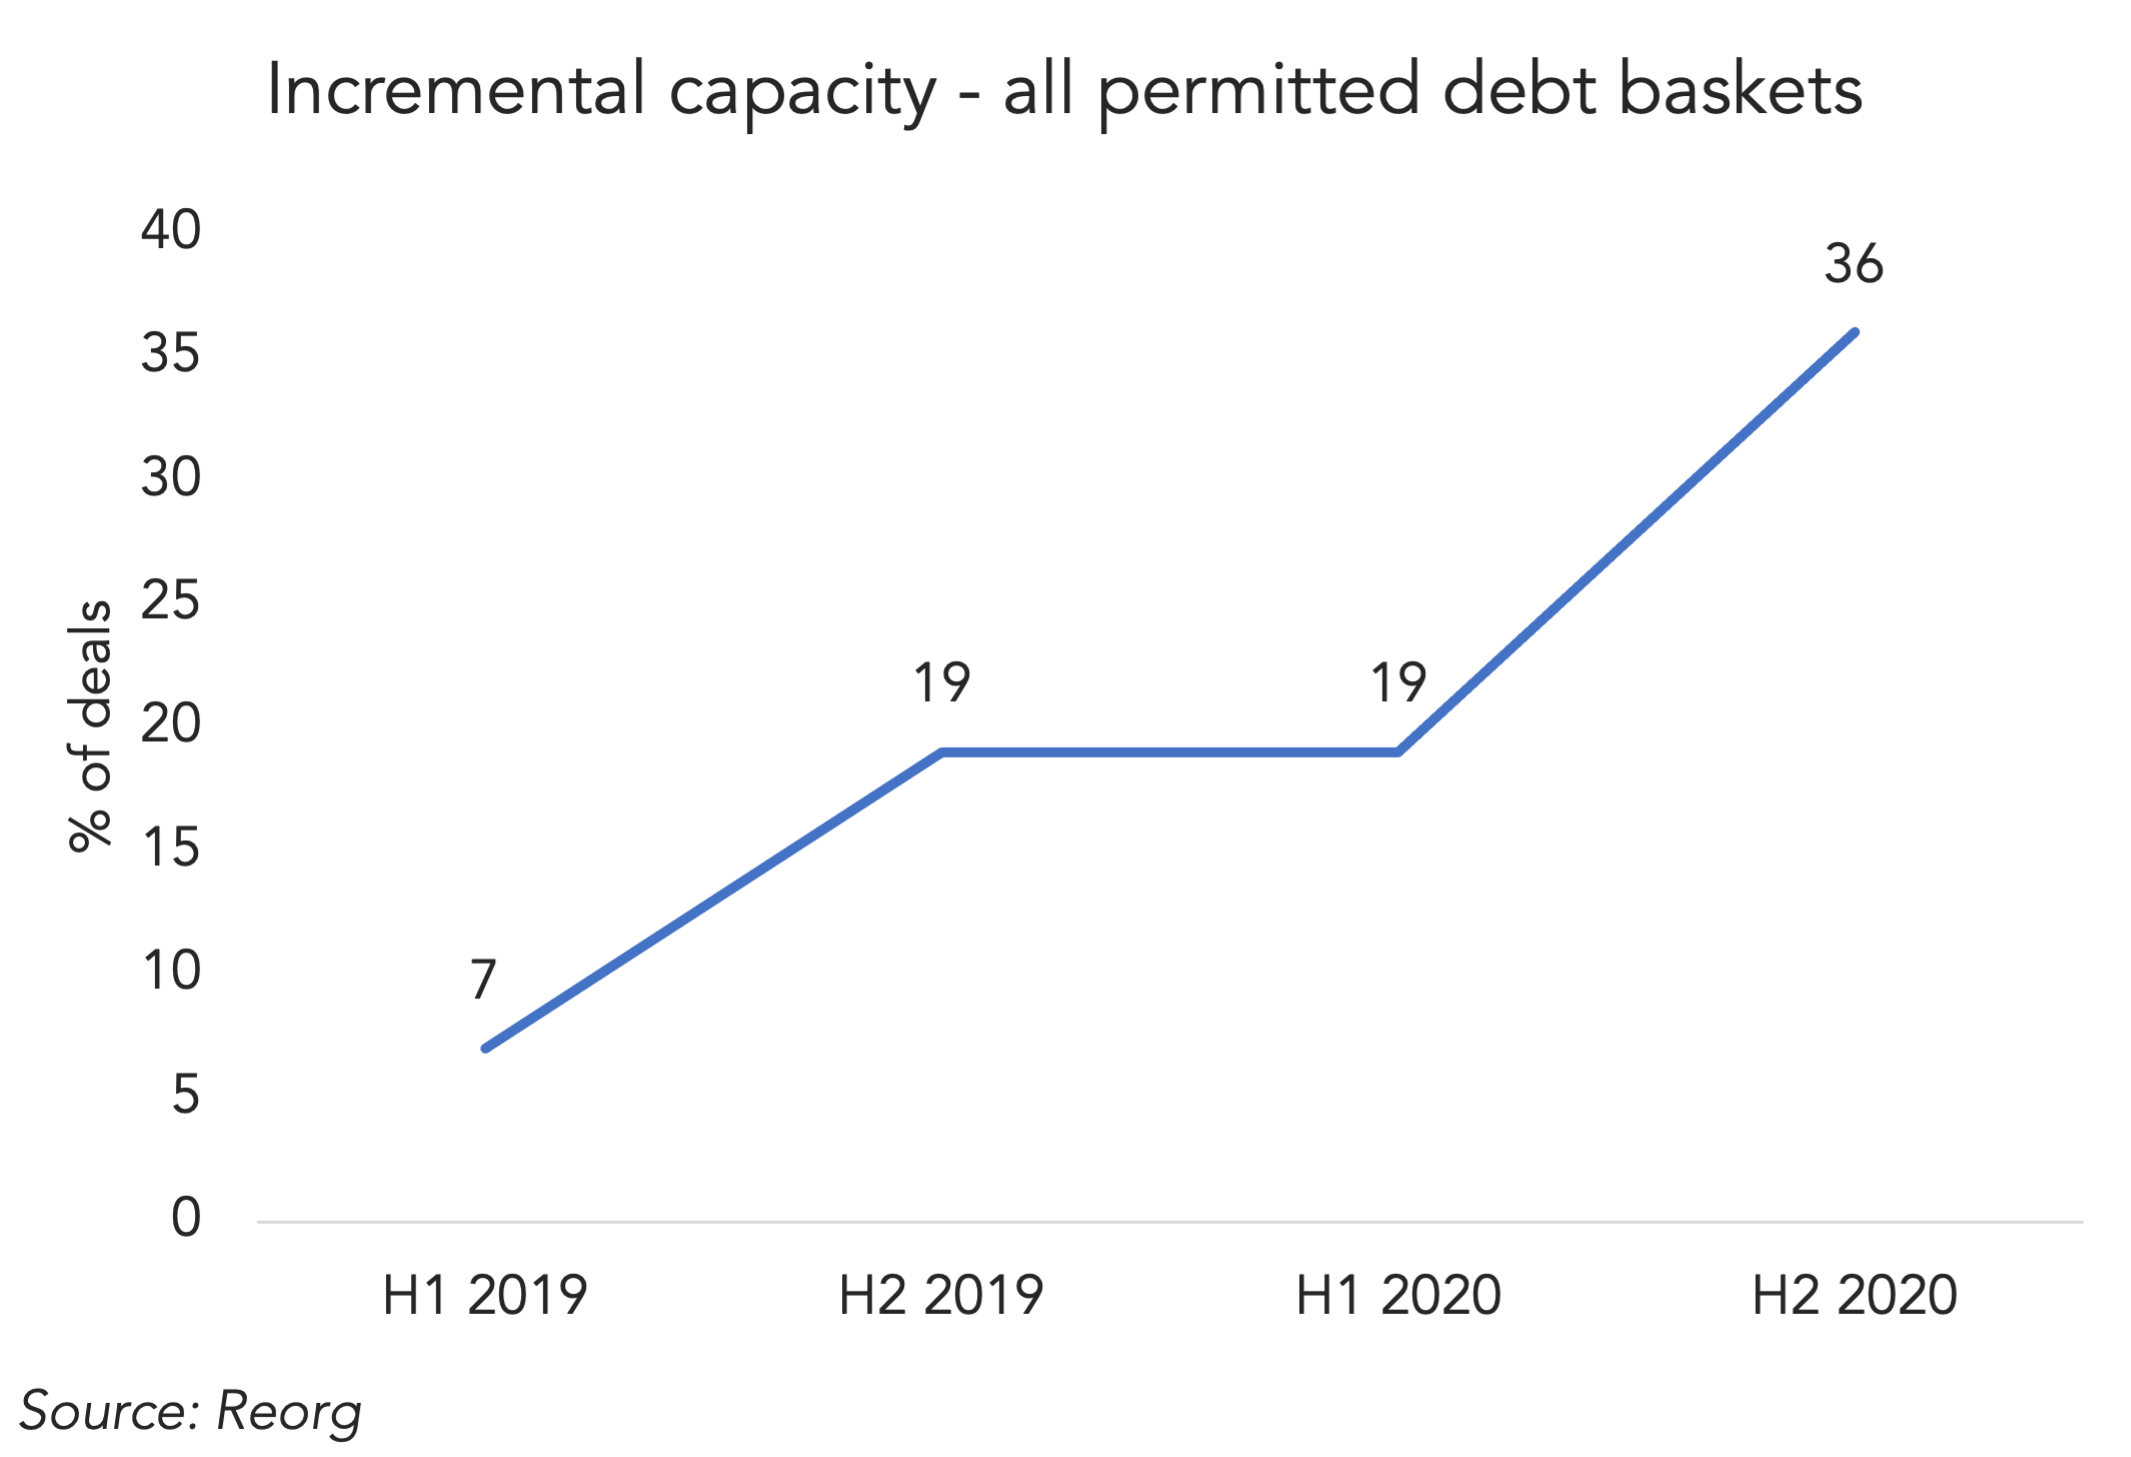
In keeping with the theme of “back to normal”, terms for new deals are once again looking decidedly borrower-friendly – having briefly moved in lenders’ favour when covid-19 first broke out in the early months of last year. The chart above shows a further increase last year in the number of European deals allowing capacity under any permitted debt basket to be used for the incurrence of incremental debt – as with many other deal term features, allowing borrowers greater flexibility than they have had before.
It may be that, in the wake of covid-19, many in the private debt market were expecting a “new normal” to take hold. In some ways – such as the way due diligence is conducted – that does indeed appear to be the case. But when it comes to deal terms, they are starting to have a very familiar look to them.
(Past performance is no guarantee of future results.)




Latest news

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Reading the Board
The story changes depending on which numbers you’re counting.
Private Credit Defaults 101: Different Numbers, Different Stories
In Season 2 of Billions, Bobby Axelrod takes his lawyer Orrin Bach to an empty Yonkers racetrack in the dead of night.