


It’s one of the most undeveloped private debt regions but demand is there from consumers, SMEs and infrastructure projects.
Unlike peers in the US, Latin American institutional investors are under-allocated to alternative assets – but demand is there and so are the opportunities. Challenges, however, include regulation and macroeconomic factors.
A January report by S&P Global predicts a $35 billion pipeline for structured credit issuance in 2025, up from $31 billion in 2024 due to demand for financing among corporates, the gap in financing available for non-bank financial institutions that serve consumers and SMEs and the region’s significant infrastructure needs.
The main LPs in Latin America are developed countries’ insurance companies, pension funds and other asset managers that typically do not have dedicated private credit teams, according to Juan Pablo Raffetto, head of Latin America infrastructure and project finance at MetLife Investment Management.
“We see higher demand for the OECD/investment grade-rated countries in the region, and particularly, infrastructure debt given the long duration, essential, defensive nature of these assets,” he says.
Within that sub-segment, Raffetto says MetLife has seen strong demand for ESG-related assets, particularly renewable energy, and transition assets such as water desalination. He adds that there is also demand for digital assets such as data centres and fibre infrastructure.
The most active LPs in the region for alternative assets are located in Brazil, Mexico, Chile, Colombia, Argentina and Peru, according to Juan Luis Rivera, managing partner and head of liquid strategies, investor relations, at Patria Investments.
He adds that Latin American LPs are generally under-allocated to alternative assets, saying they may have a 5-10 percent target allocation, but their portfolios are anywhere from 3-5 percent short of those goals. Only 2 percent of private debt LPs are located in Latin America, according to Private Debt Investor’s August 2024 Investor Report.
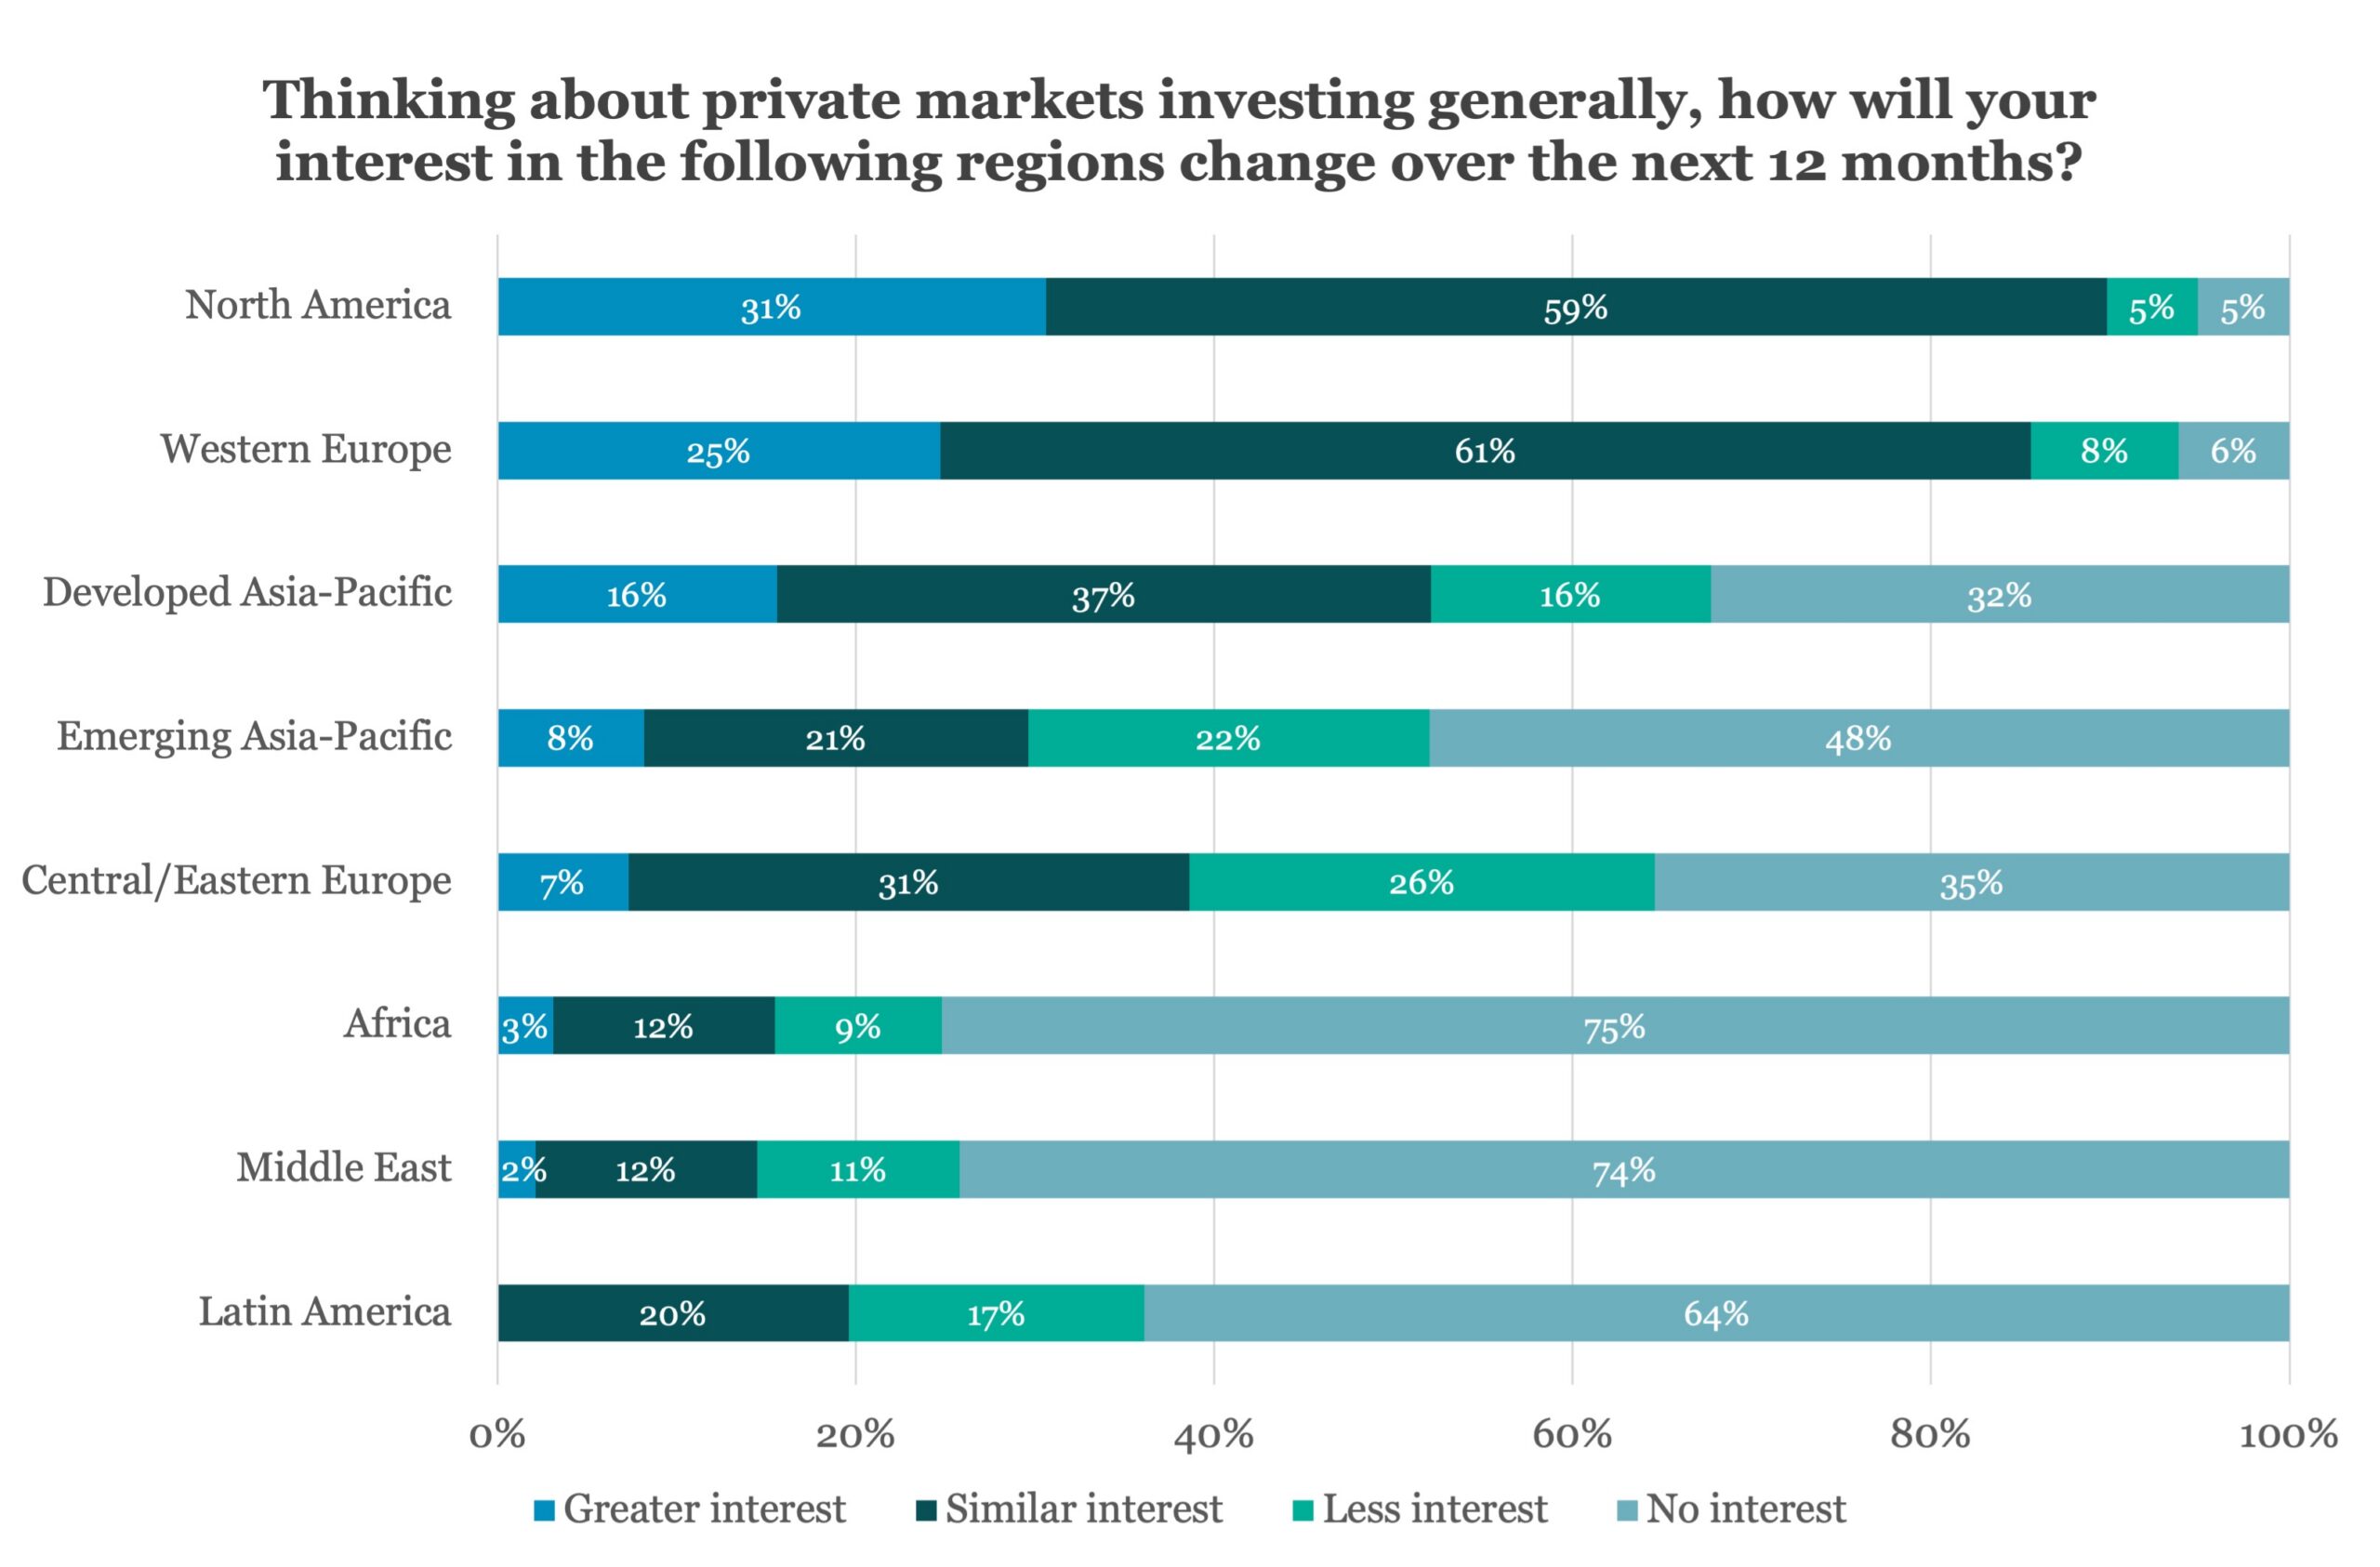
In our Perspectives report, we did not find much evidence of LPs in general looking to ramp up their Latin America allocations (see chart) – but the potential in the region appears to be growing.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
