Does size matter?
Ask managers, and they’ll say yes.
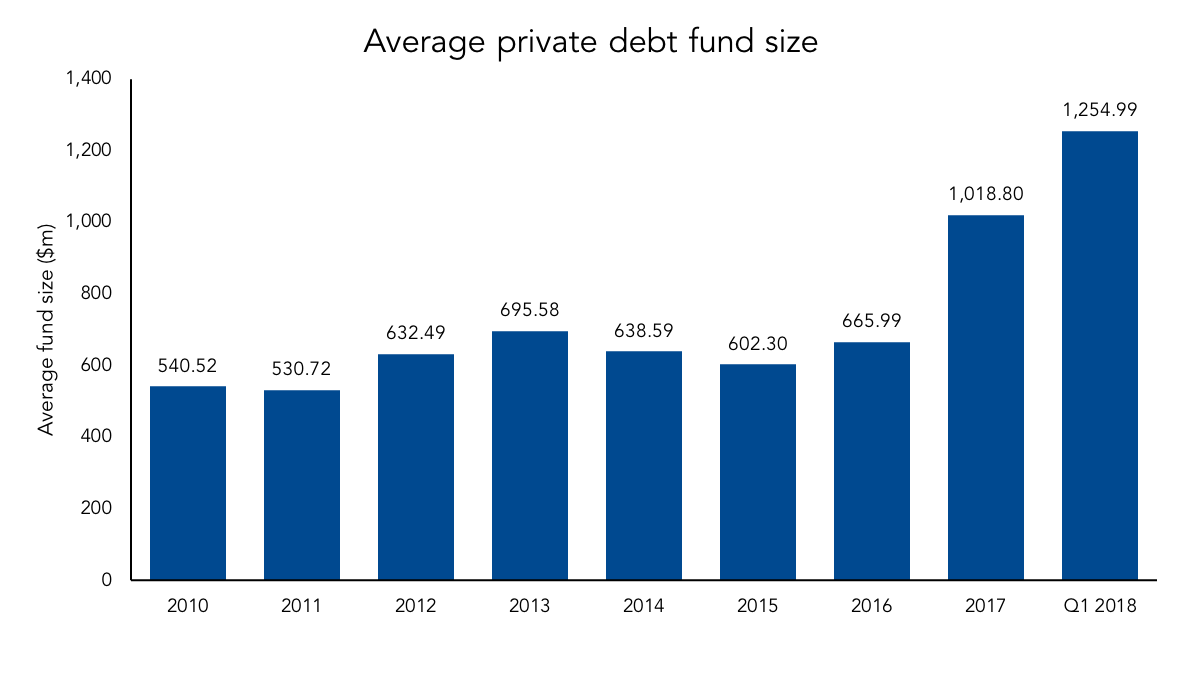
The rush toward credit continues; as the asset class keeps growing, the average fund size has grown with it. In the first quarter of the year, the average private debt fund size stood at $1.25 billion, larger than last year’s four-quarter average of $1.02 billion and almost double 2016’s $665.99 million.
That the size of the average private credit vehicle keeps increasing isn’t surprising, but the speed with which it has shot up is still impressive. The quarter’s largest close by far was GSO Capital Solution Fund III’s $7 billion close, which easily surpassed the $6.5 billion target.
While the GSO fund may have skewed the quarter’s curve slightly, such totals are no longer as surprising as they may have previously been. Two other notable mega-funds raised last year were HPS Investment Partners’ HPS Specialty Loan Fund 2016, which raised $4.5 billion in equity commitments, and Intermediate Capital Group’s €5.2 billion ($6.56 billion) ICG Senior Debt Partners III.
As the average fund size keeps increasing, so too does the total raised for the asset class. The total raised for the first quarter stood at $35.14 billion, which is larger than the $31.19 billion raised the same time last year.
Both anecdotally and empirically, the dry powder keeps piling up, which gives rise to a central question: are managers raising money because they can or because they have the pipeline to deploy the capital?
Certainly, there are two sides to that debate. On the one hand, managers want capital on hand when credit markets seize up and it becomes a lender’s market, the so-called “patient capital”; on the other hand, why lock up limited partner money if the deals aren’t there? A happy medium certainly exists somewhere.
Private debt fundraising can’t go gangbusters forever though. Eventually the music will stop, and the managers that used this fundraising bonanza wisely will benefit.




Latest news
Fitch Ratings’ U.S. Private Credit Default Rate Rose to 6.3% in August 2026
Fitch Ratings recorded a U.S. Private Credit Default Rate (PCDR) of 6.3% for the trailing 12 months (TTM) ended August 2026, up from 6.1% in July 2026 and a record high.