


The boom in senior debt fundraising subsided somewhat in the first quarter of the year, while North America remained the dominant region.
Fundraising in Q1 2022 continued the very gradual downward trend of the past six years, according to Private Debt Investor data. However, given that additional funds will likely be discovered and added to the total during the rest of the year, fundraising may well sit a little higher come the Q2 report.
The number of funds raised continued to be low and the last quarter offers a limited data pool to examine. Once again, large funds are dominating and have the potential to skew the data.
While senior debt dominated the landscape in 2021, in Q1 2022 it dropped closer to previous levels, slightly ahead of subordinated debt fundraising, while distressed debt continued to fall back. A single large fund of funds represented 10 percent of the market, showing how the limited number of data points is making it difficult to discern trends from the first quarter.
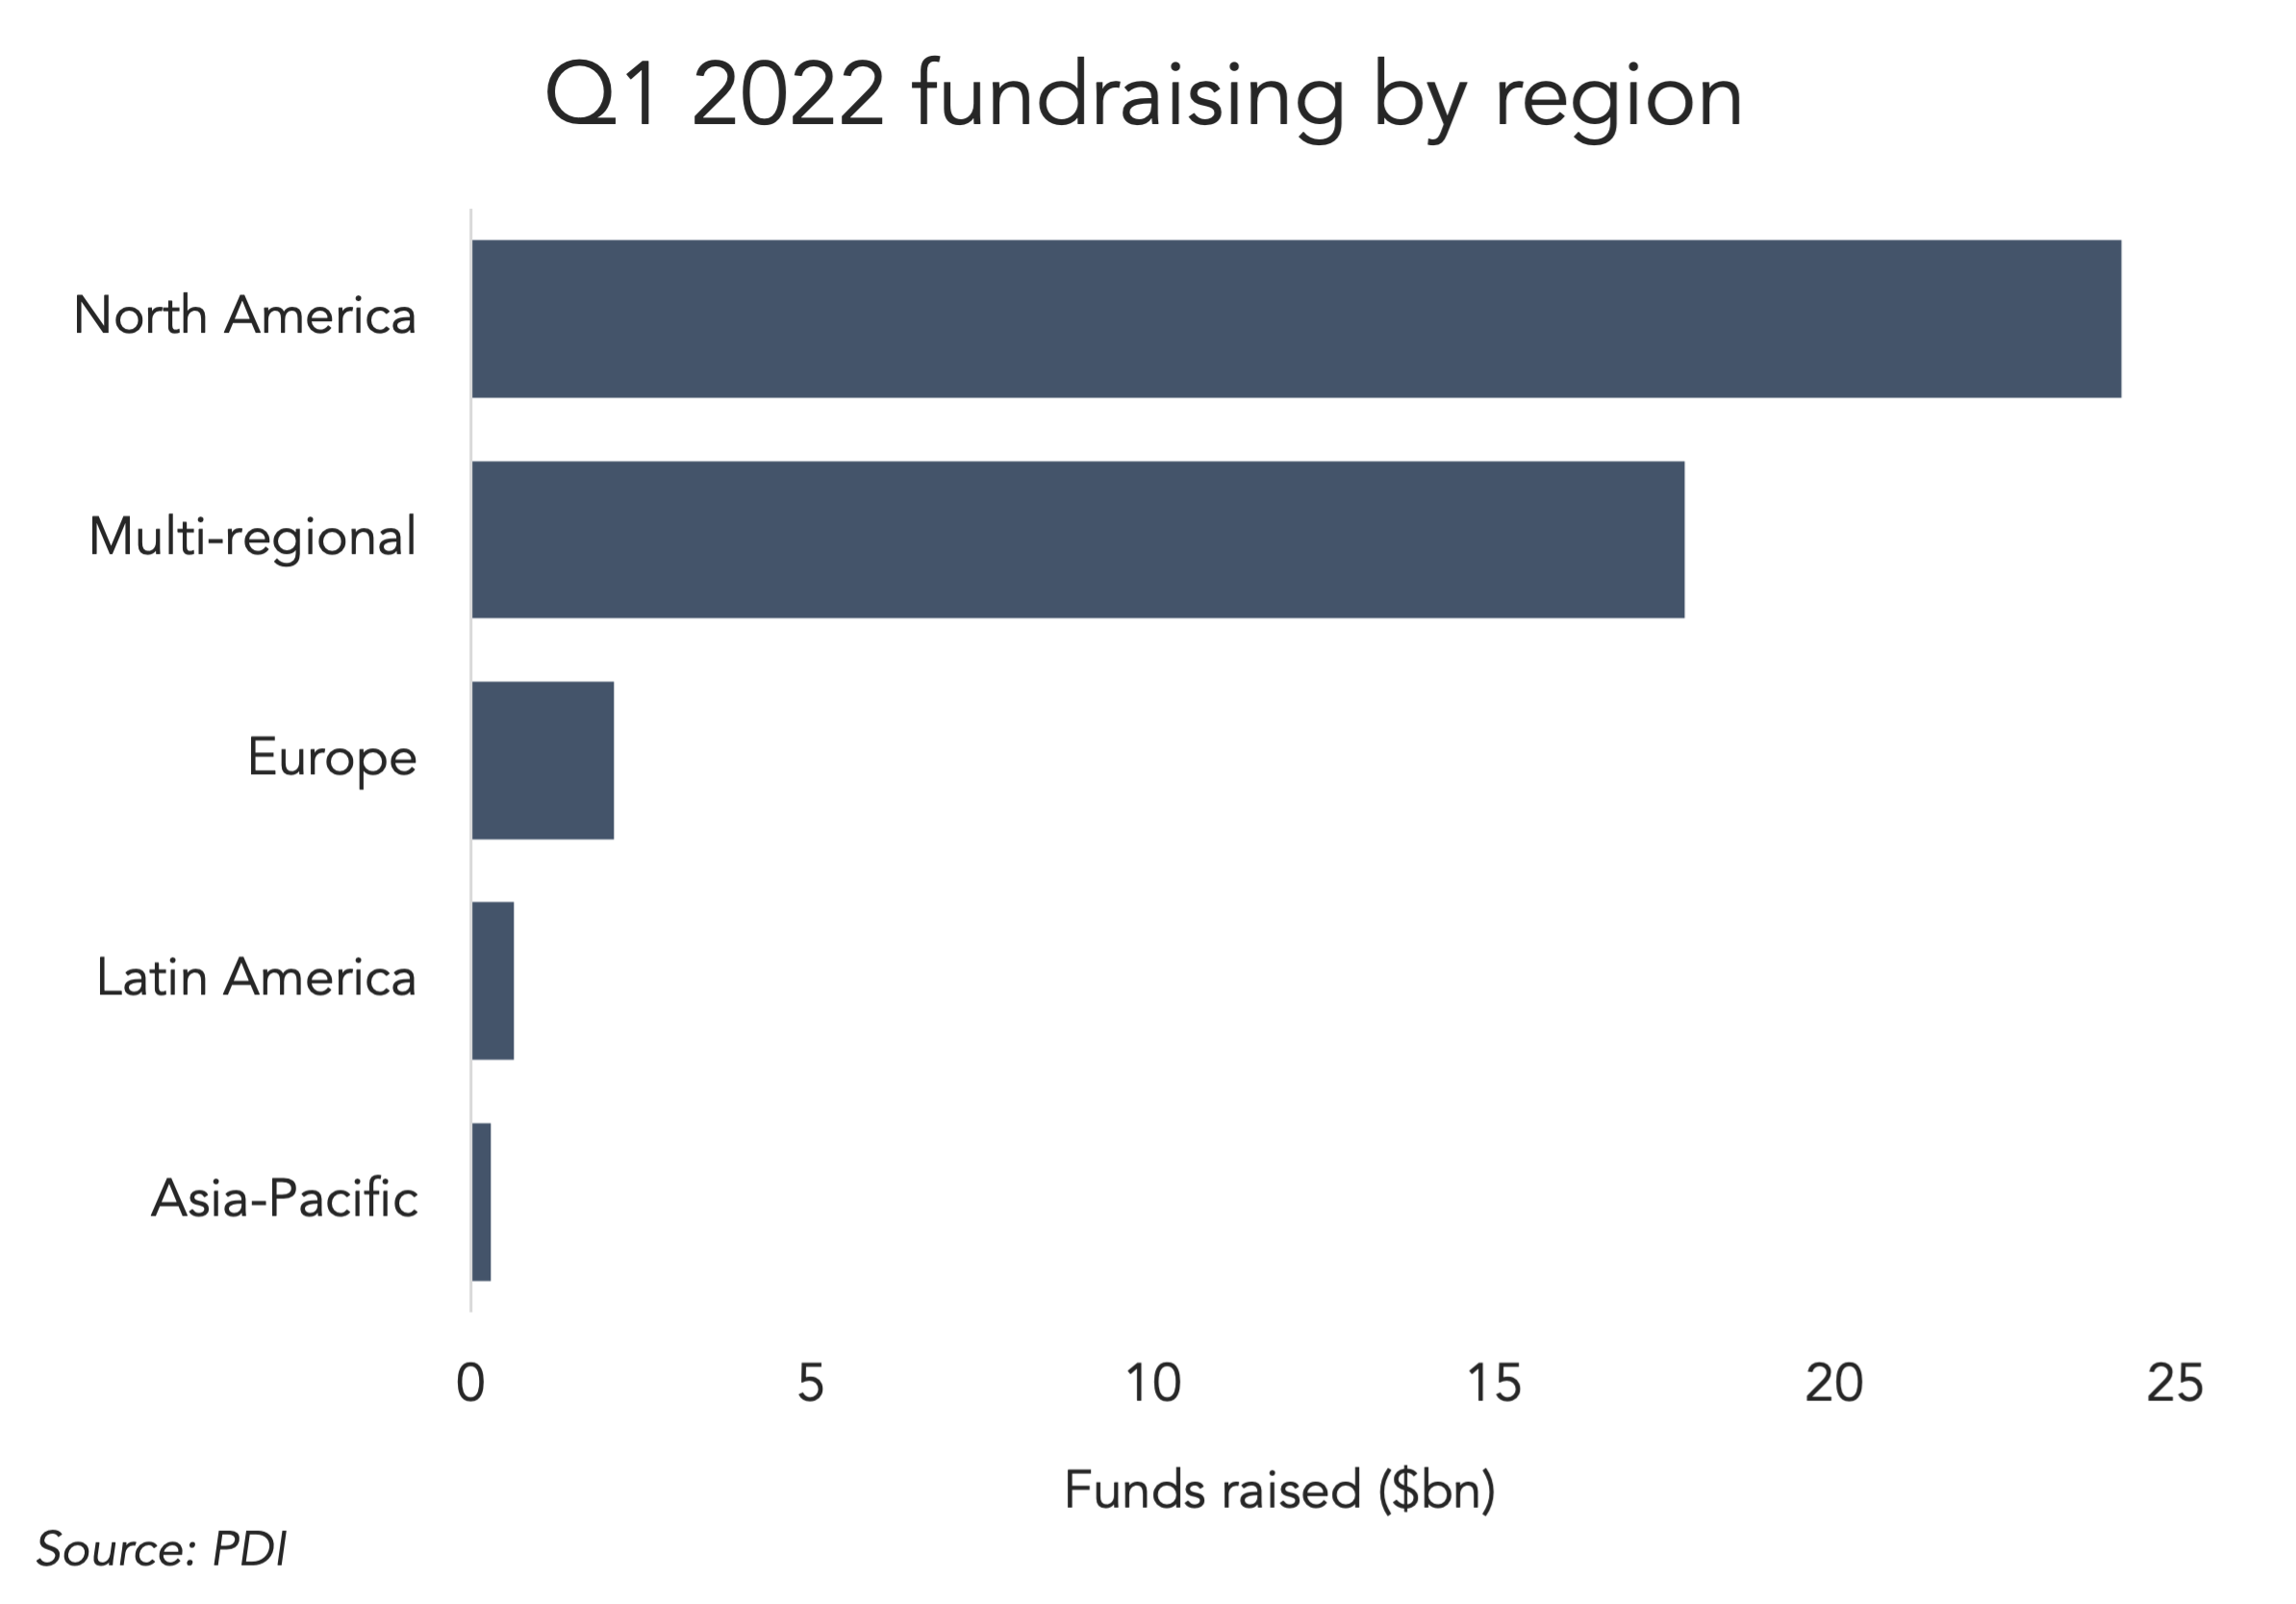
As usual, North America is by far the largest fundraising market globally (see chart above). Noteworthy in Q1 2022 is the very low figure for Europe. Again, the small number of funds that closed in the quarter make it difficult to understand what is going on the market – we would expect European fundraising to start catching up a little later in the year.
The number of funds seeking capital indicated that there were plenty of managers on the road in Europe, so we can expect fundraising to pick up in the coming quarters as some of those funds reach a final close. However, North America is still set to take the lion’s share of capital, with significantly more fundraising activity than the rest of the world.
Asia-Pacific has a lot of funds raising presently and almost $20 billion targeted. It remains to be seen if this will translate into an uptick in alternative credit activity in the region.
(Past performance is no guarantee of future results.)



Latest news
Number of smaller funds dwindles
Analysis of fund-close data found that vehicles valued at under $250m have seen a rapid decline since 2024.While PEI Private…

US Private Credit Transparency Highlights Uneven BDC Performance
Credit performance across business development company (BDC) portfolios remains uneven, although reported losses and non-accruals were broadly stable quarter over quarter, according to Fitch Ratings’ Private Credit Transparency Monitor for 2Q26.