


Aided by support schemes, many businesses have been protected from the worst effects of the pandemic. But what happens when the support comes to an end?
“While we are not out of the woods, we have seen a large number of loans return to performing credits, and we expect that trend to continue for the foreseeable future.” These were the cheering words of Stephen Boyko, co-chair of law firm Proskauer’s private credit group, responding to the findings of the firm’s latest Private Credit Default Index.
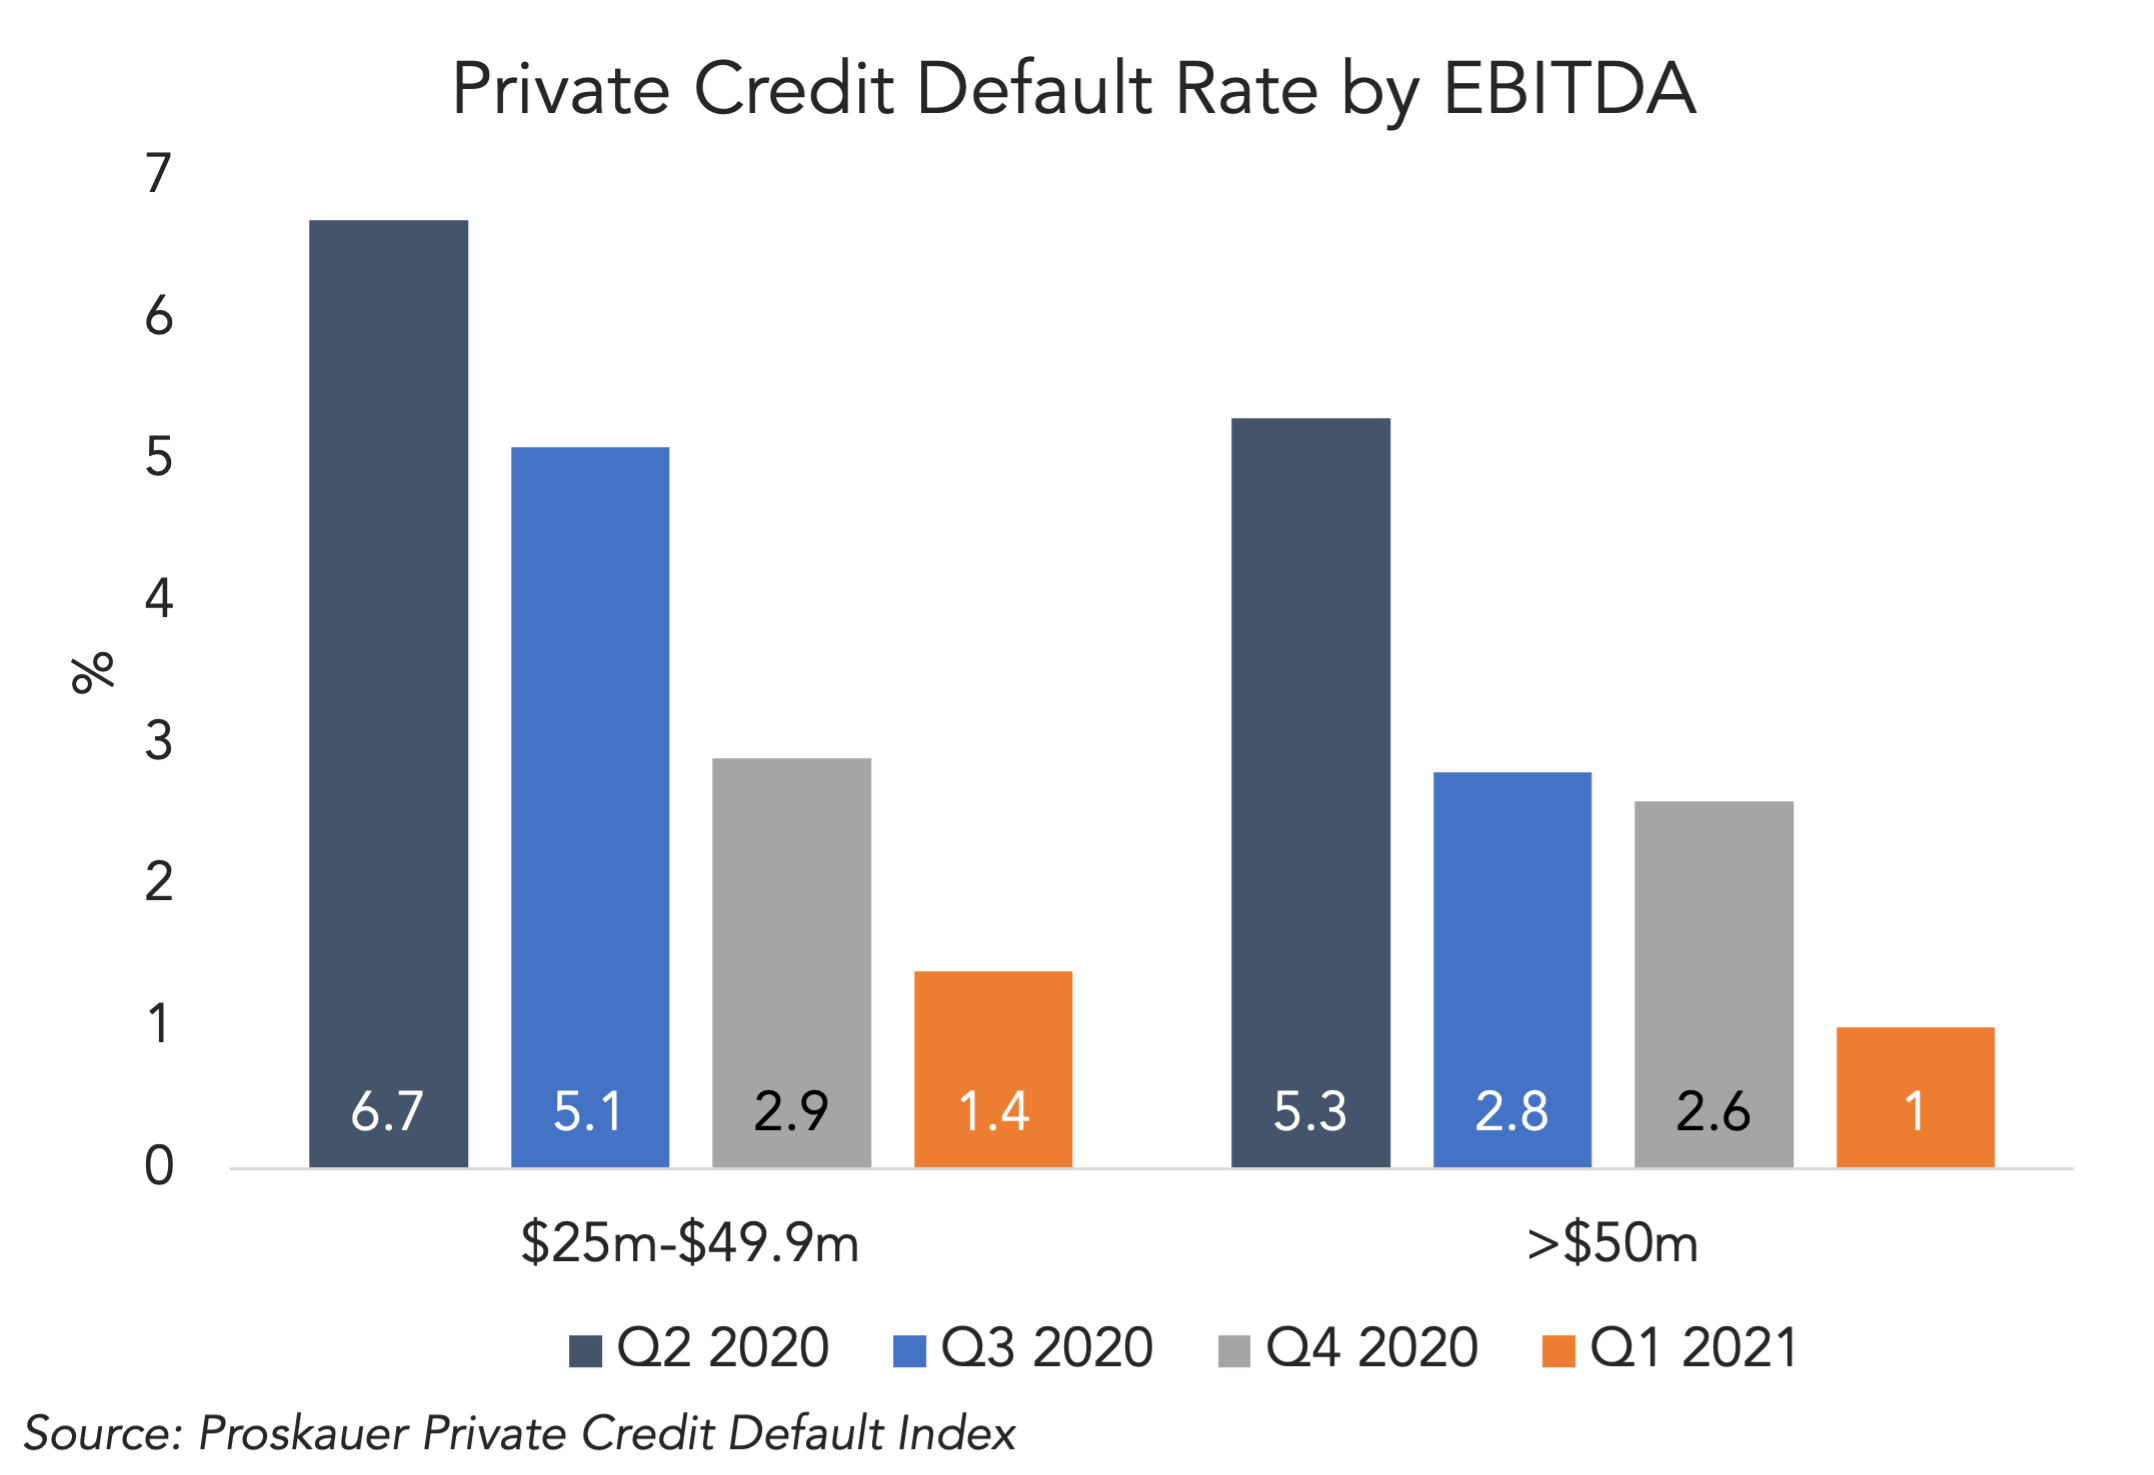
Looking at the figures from Q1 2021, Boyko appears to have good reason for optimism. The index, which tracks the default rates of senior secured and unitranche loans, saw the rate shoot up to 8.1 percent in the second quarter of last year, but the following two quarters saw it move back down towards more normal levels – 4.2 percent in Q3 and 3.6 percent in Q4. The first quarter of this year saw the rate fall further to 2.4 percent overall and just 1.0 percent for companies with EBITDA of more than $50 million (see chart above).
It seems clear, for now at least, that any imagined parallels with the global financial crisis can be put to one side. The pandemic has presented challenges to businesses, as the Q2 2020 figures make clear, but nothing on the scale of what happened in 2009.
A major difference this time around, as has been well documented, is the support schemes that have come to the rescue of many companies in need. While these schemes have been invaluable, and undoubtedly have provided a template for future crises, they are also finite. And when the life support system is switched off, what happens then?
A study out this week from corporate and fiduciary services firm Ocorian found that nearly half (47 percent) of capital market investors with direct lending strategies said they were lacking confidence in their ability to manage loss recoveries “which could have serious implications if default rates rise as pandemic-driven government support schemes are withdrawn”. Perhaps it’s worth reminding ourselves of Boyko’s comment about not being out of the woods just yet.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
