


Many private markets managers expect rapid growth in the coming years, but some of those optimistic firms may find themselves being bought – just ask some BDC managers.
One of the marquee stories in the finance world post-global financial crisis has been the rise of alternative assets.
Private equity, an already well-established asset class, has grown by leaps and bounds. Private credit has come into its own, earning plaudits from limited partners in the form of ever-larger fund commitments and specific portfolio allocations for private debt.
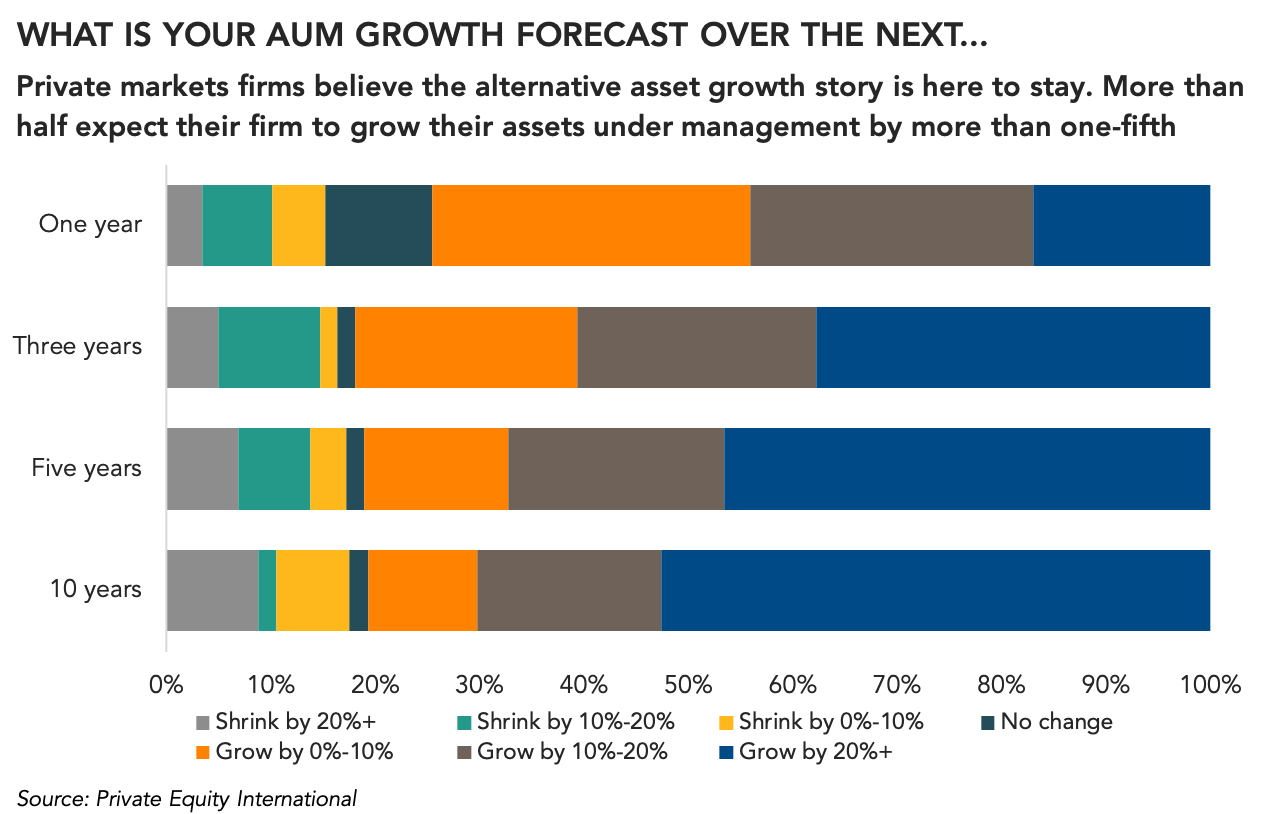
So, it’s not a surprise that a survey of private fund chief financial officers – of which private debt firms were the largest respondents by primary strategy type – found most respondents expecting to grow.
The study, conducted by sister publication Private Equity International in partnership with RBC, showed two-thirds of survey participants expecting to grow by more than 10 percent over the next five years. It also showed more than half anticipating growth of more than 20 percent over the next decade.
In the private debt and private equity worlds, these expectations play out against the consolidation of the asset classes, particularly for credit managers in the business development company world.
In just the past few years, Ares Capital Corporation acquired American Capital. Oaktree Capital Management acquired Fifth Street Asset Management’s BDCs. Barings externalised Triangle Capital’s management contract. Alcentra Capital Corporation and Medley Capital Corporation are both up for sale.
In a world where the smaller or subpar managers may get gobbled up by the larger or more successful managers, some of those firms expecting to experience rapid growth may find themselves under new ownership.
Each firm should believe in their product and the opportunity set they offer, though each asset manager will have to answer the fundamental question they ask when lending or buying a company: what market void is this business filling and does it have a reason to exist?




Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…