


The sector is continuing to grow in popularity, evidenced by recent strategic moves from the likes of SoftBank and BlackRock.
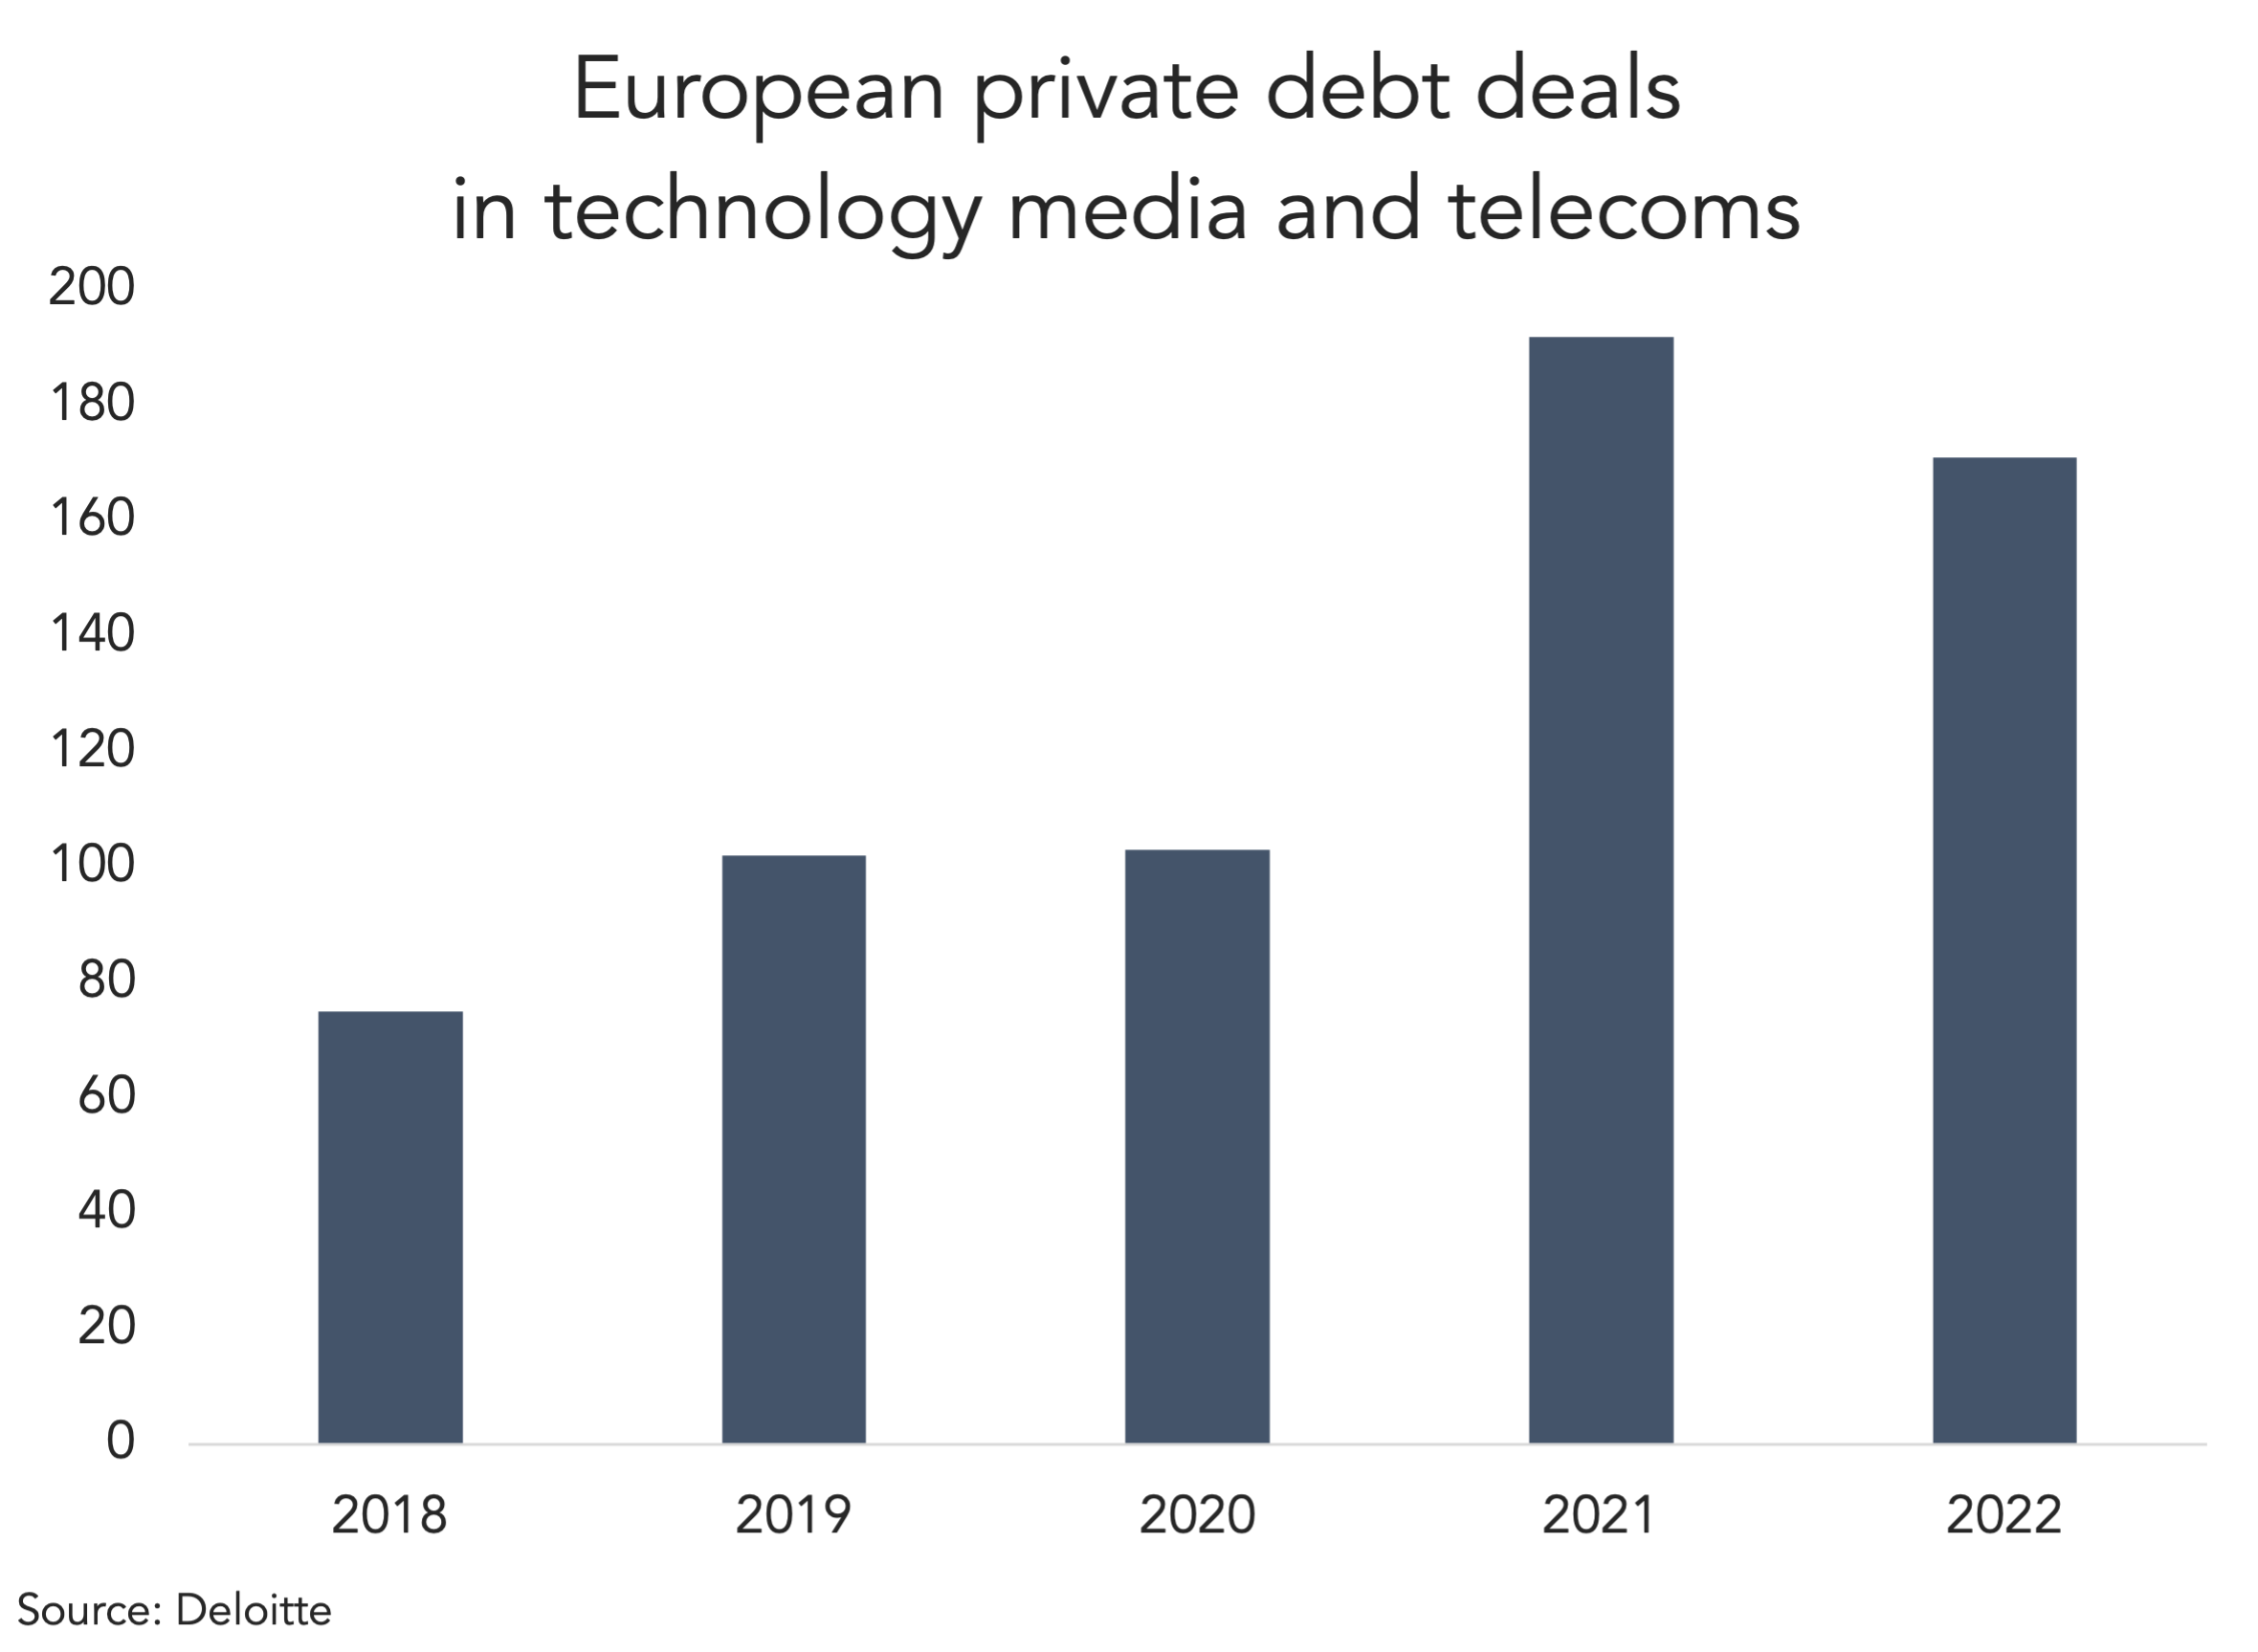
The technology sector has proved to be one of the most popular and resilient for private credit lenders ever since the covid-19 pandemic, and the trend shows little sign of letting up. According to deal data from Deloitte, private debt fund investments in technology, media and telecoms businesses accounted for nearly 23 percent of all European deal activity in 2022. This was the third year running that the sector has been the most popular in Deloitte’s analysis.
For private debt lenders, the opportunity set is likely to grow in the wake of the collapse of Silicon Valley Bank and many firms are now thought to be looking at how they can fill a funding gap in the technology market.
In May, Bloomberg reported that Japan’s SoftBank is considering launching a private credit strategy focused on late-stage tech startups. According to Bloomberg, the fund would look to offer debt and debt-like structured financing to provide liquidity for technology startups, with a returns target in the mid-teens.
SoftBank already specialises in investing in the technology sector but has suffered losses on its equity investments through underperformance in firms such as office sharing firm WeWork and ride-hailing business Didi Global. Credit could be a way for SoftBank to continue backing the technology sector but at a lower risk level than with equity exposure.
A further development came on 8 June when global investment manager BlackRock announced it had entered an agreement to acquire European growth lending specialist Kreos Capital. London-headquartered Kreos has been providing venture lending to companies in the technology and healthcare sectors for more than 20 years and is currently raising its seventh-generation fund, which is thought to have already secured more than €1 billion.
Stephan Caron, managing director and head of European middle market private debt at BlackRock, told PDI that the deal allows it to bring in an experienced team in this area of investing.
(Past performance is no guarantee of future results.)




Latest news

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…

LevFin Issuance Slows Across Products in August; DCM Remains a Bright Spot
The leveraged capital markets business continued to decelerate from just about every aspect, even for August standards. Overall issuance (including…