


Initial wariness over subscription finance has given way to acceptance – at least when it comes to brand-name GPs.
“Leverage is a sensitive topic for LPs,” says Carolina Espinal, managing director at HarbourVest Partners. But while skepticism was rife in the early days of the subscription finance market, when limited partners feared that the facilities were being used to manipulate optics and boost internal rates of return, there is now a broad consensus that the advantages in terms of treasury management outweigh any initial concerns.
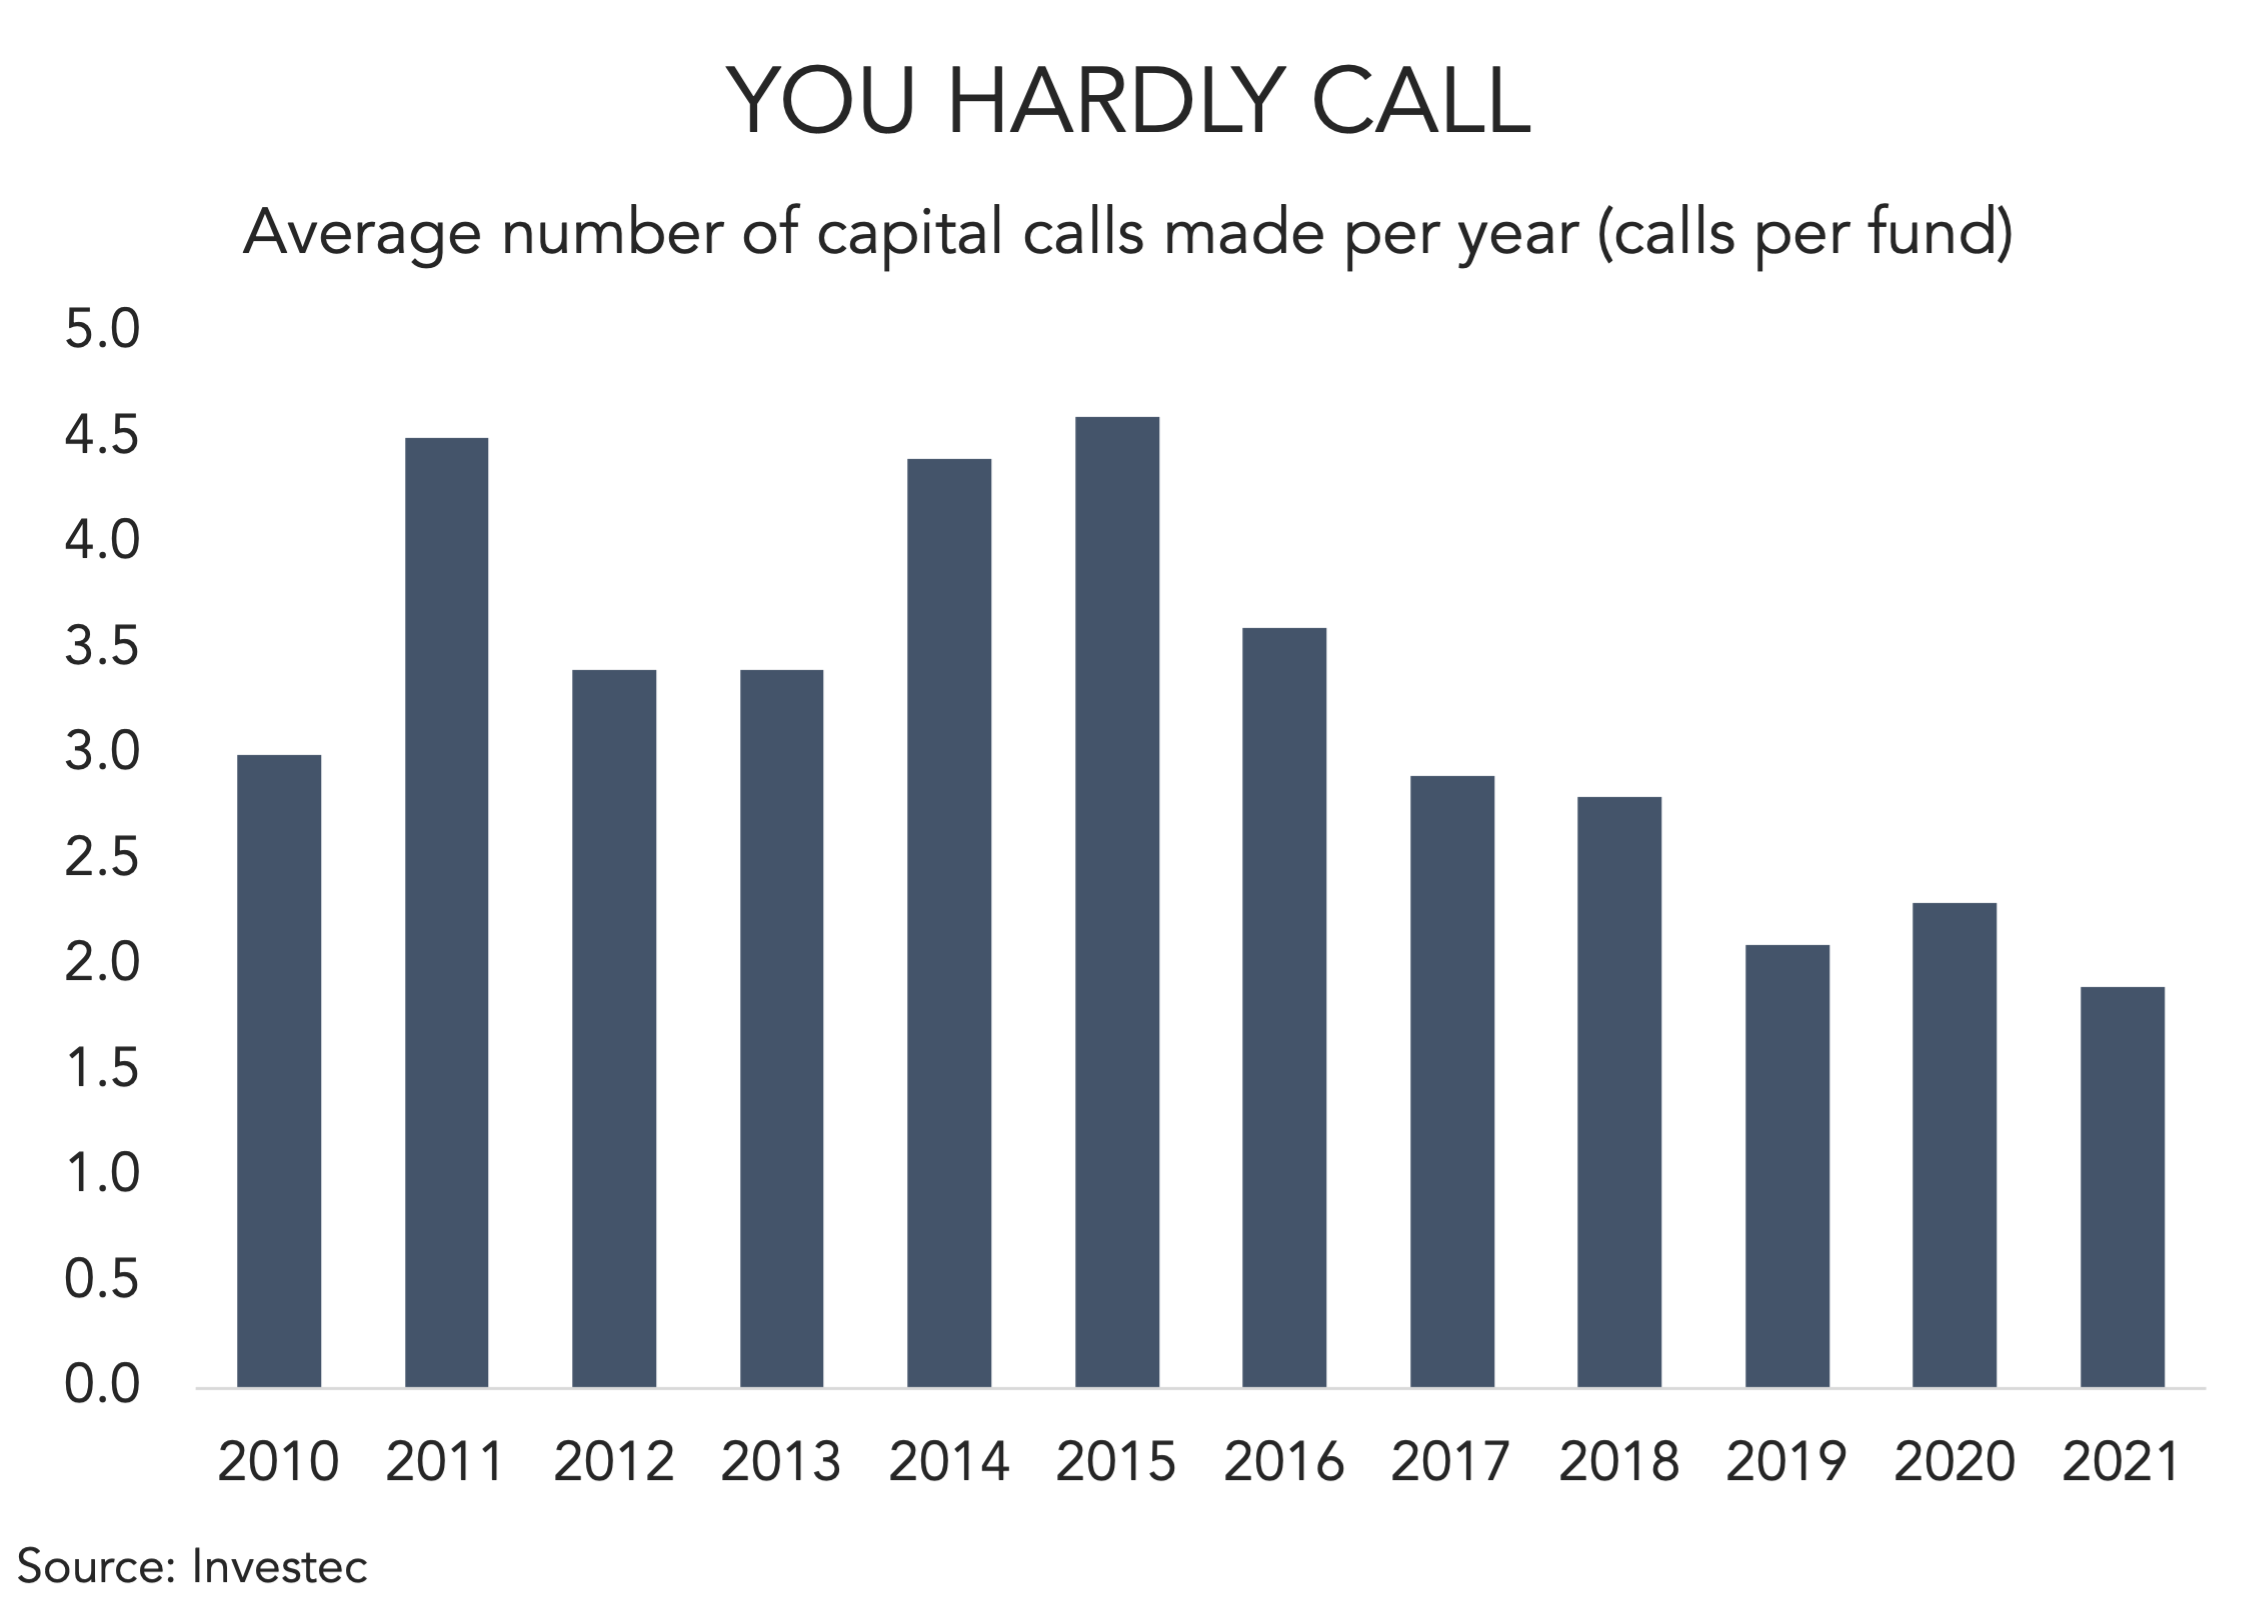
A recent Investec survey showed that the frequency with which GPs are calling down capital from LPs has continued to fall, from an average of 2.3 times per annum in 2020 to a 10-year low of 1.9 times last year (see chart), alleviating pressure on back-office functions. It is also now considered best practice to report IRRs both with and without the facility, so investors have clarity on the impact of the line.
Nonetheless, LPs will sometimes seek to curtail LTVs and, more commonly, duration. “I have seen side letters where LPs are saying that although the LPA allows the GP to borrow for 24 months at 30 percent, they want the facility to be cleared down every 12 months,” says Ian Wiese, head of secondaries at Investec.
Typically, however, LPs will not object to the use of a subscription facility if the justification is strong and well communicated. “If you are a blue-chip GP which has demonstrated performance time and again, LPs will have no problem,” Weise explains. “Pushback only really arises when you have an underperforming GP suddenly using excessive lines in order to change the picture and to cover up performance.”
Weise adds: “Sub lines used to be seen as arbitrage – a tool for enhancing returns – now they are seen as an essential treasury management tool. If there is proper justification and the GP actively communicates that rationale to its LPs, then they will be happy to buy into it.”
(Past performance is no guarantee of future results.)


Latest news
U.S. Leveraged Finance M&A Rebounds as Credit Quality Pressures Emerge in 3Q26
North American leveraged finance gross issuance moderated in 3Q26 as refinancing activity declined and transaction-related financing increased, according to a new Fitch Ratings report.
Is direct lending losing its lustre?
Our Investor Perspectives survey shows asset-backed finance gaining in popularity as LPs reconsider where to allocate their dollars. The importance…