


It’s an area of alternative assets that has retained its popularity with LPs despite the challenges experienced by fundraisers lately.
Last year was notoriously tough on the fundraising trail for alternative asset classes but infrastructure debt managed to buck the trend, with affiliate title Infrastructure Investor’s Debt 30 ranking recording a $10 billion increase in total capital raised for 2023. This was well below the $23 billion increase the previous year, but still represented an impressive vote of investor faith during challenging times.
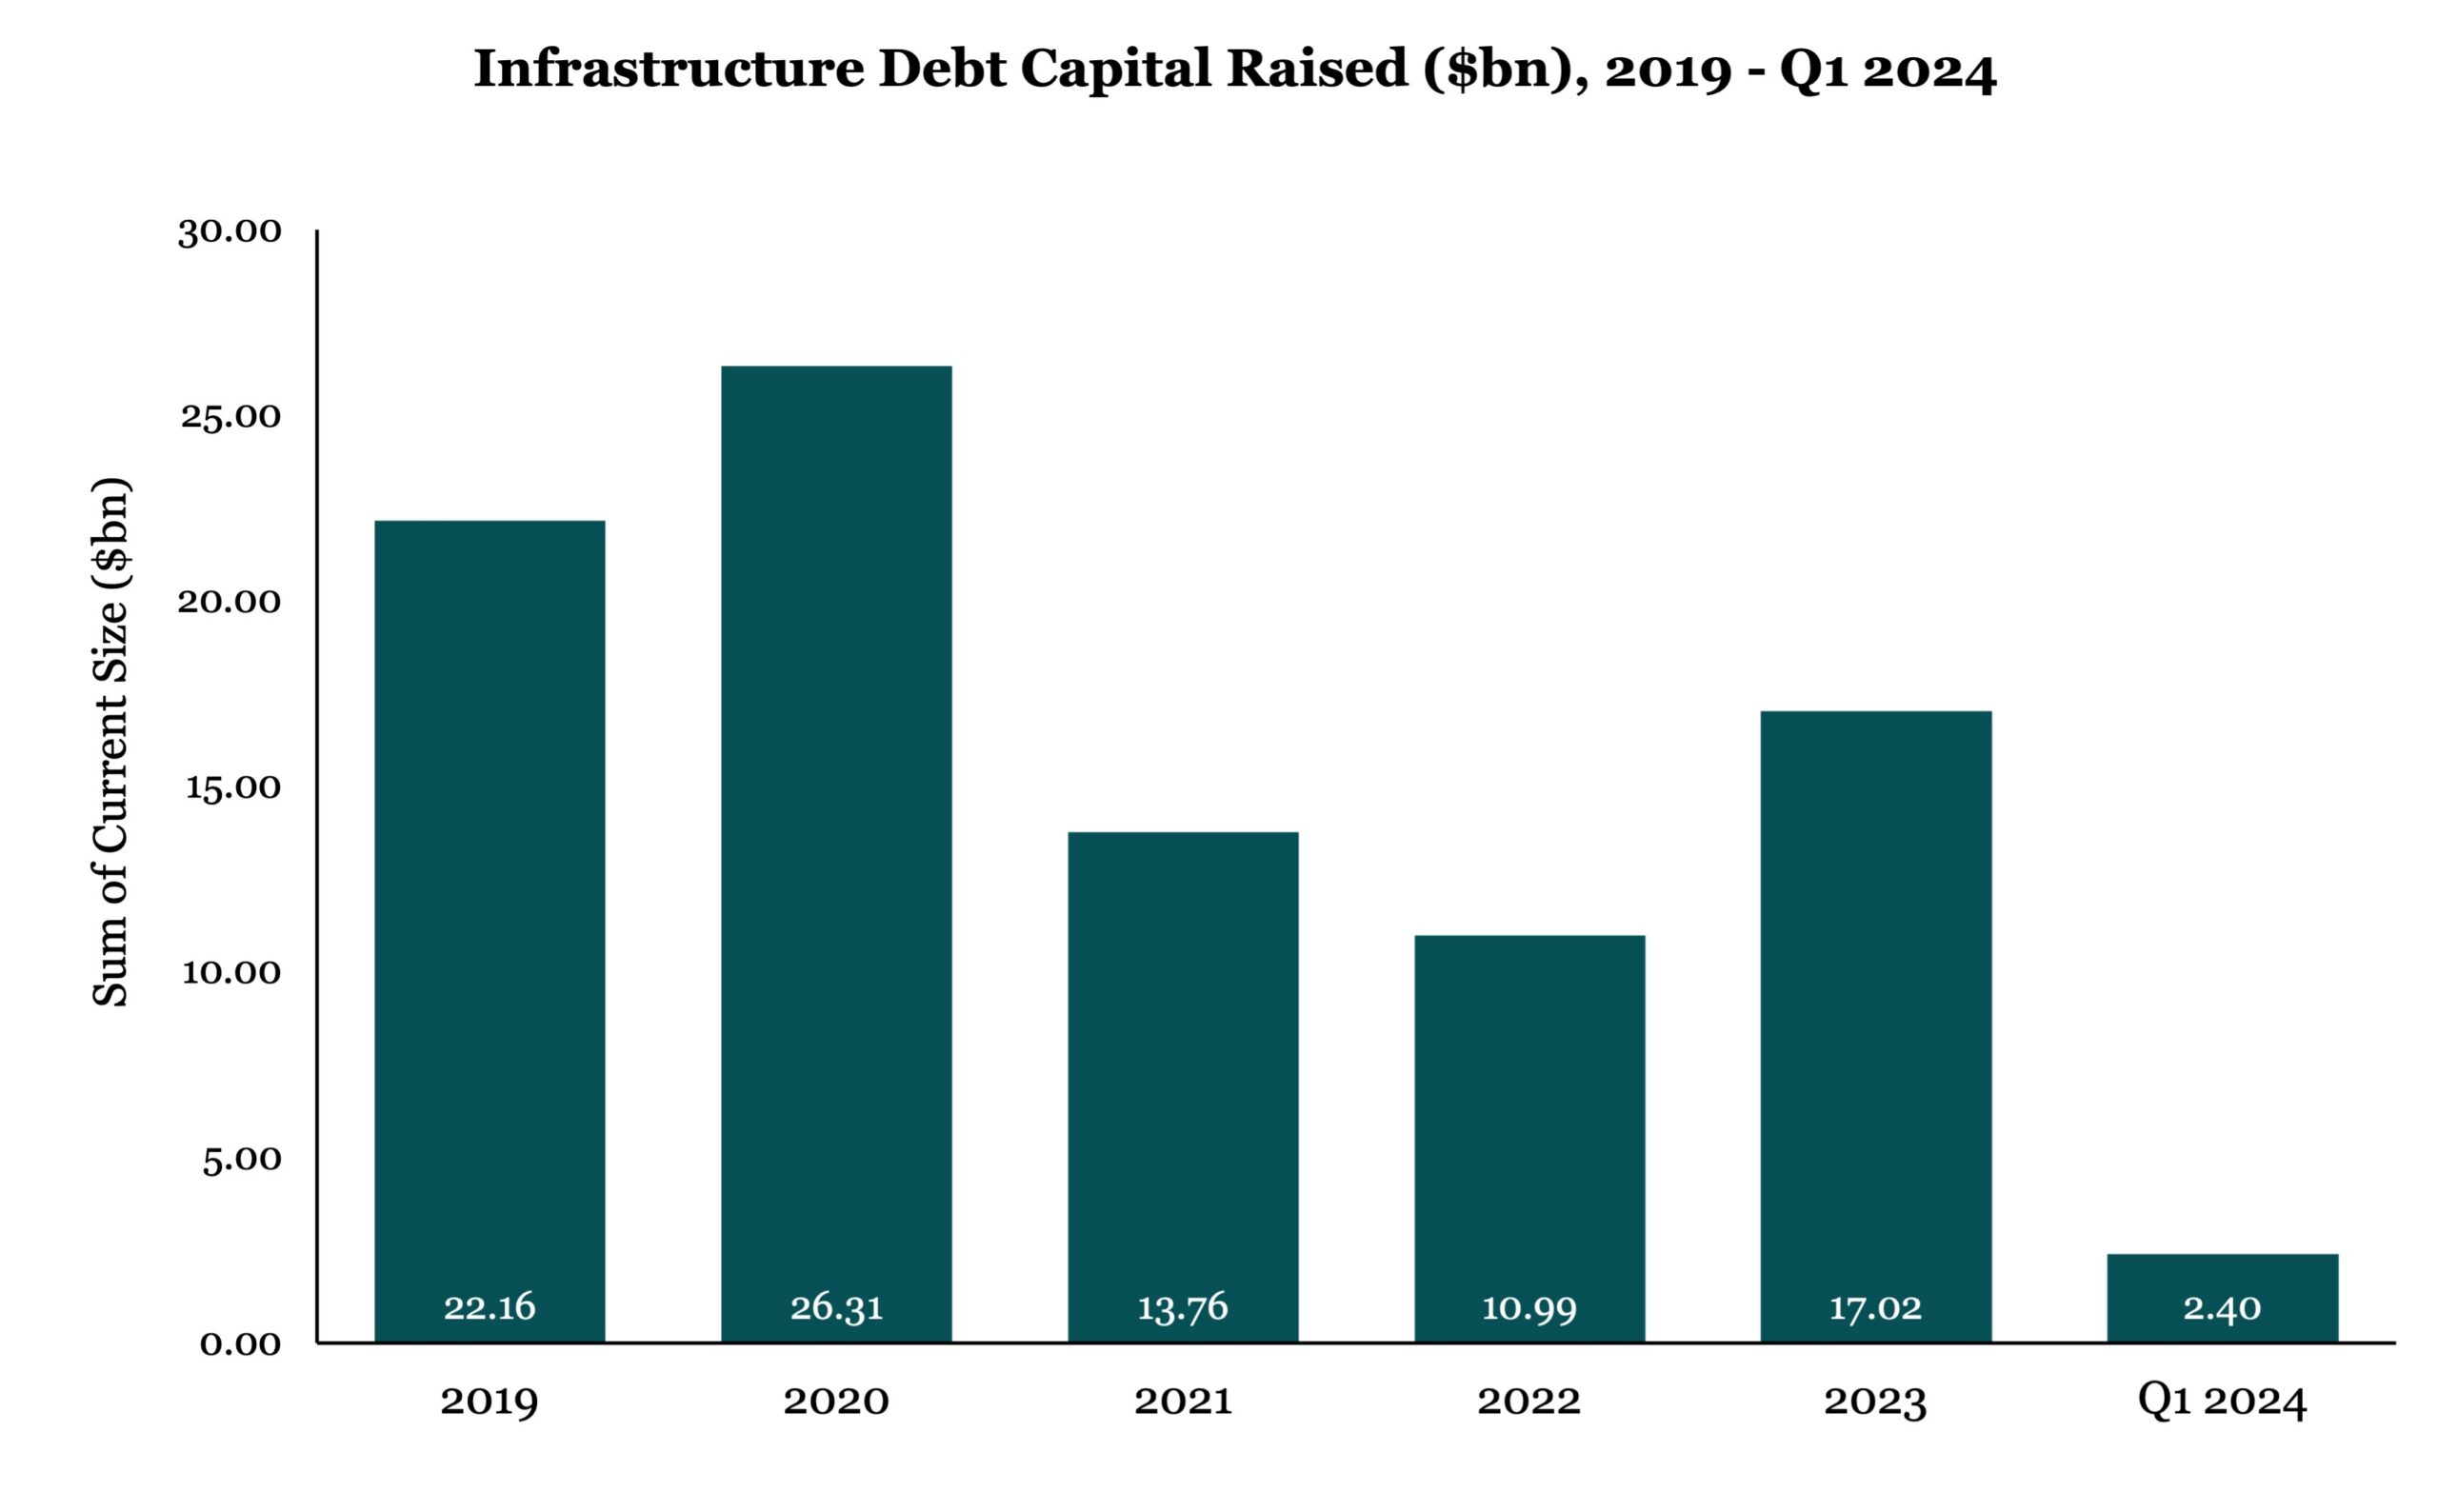
Private Debt Investor’s own fundraising figures also offer some support to the claim that infrastructure debt was a rare bright spot in a tough climate last year. As can be seen from the accompanying chart, the sector saw more than $17 billion of fundraising in 2023 – a higher total than that recorded in each of the prior two years.
Our LP Perspectives survey indicated that 30 percent of respondents planned to lift allocations to infrastructure debt in 2024, with just 4 percent saying they would invest less capital.
Responding to the findings, Jeetu Balchandani, global head of infrastructure debt at BlackRock, said: “There is pent-up demand from a more stagnant 2023 across the industry and the current landscape is exciting. Advances in technology, supportive government policy, an increased rate environment, and energy transition thematics are creating a strong pipeline of opportunities.”
At present, there is particularly strong demand for data centre and renewable energy investment in North America. Some have compared the build out of data centres to the construction of railways in terms of speed of execution and transformation of the infrastructure landscape.
While the view among market participants is that deal flow is currently slower in Europe and Asia-Pacific, partly because the banks are more active competitors in these regions, the data and renewable energy build outs are global phenomena, ensuring that – with a bit of hard work – deals are to be found everywhere.




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…