


2017 was one heck of a fundraising year that saw stratospheric amounts of capital raised. 2018 will be a regular one.
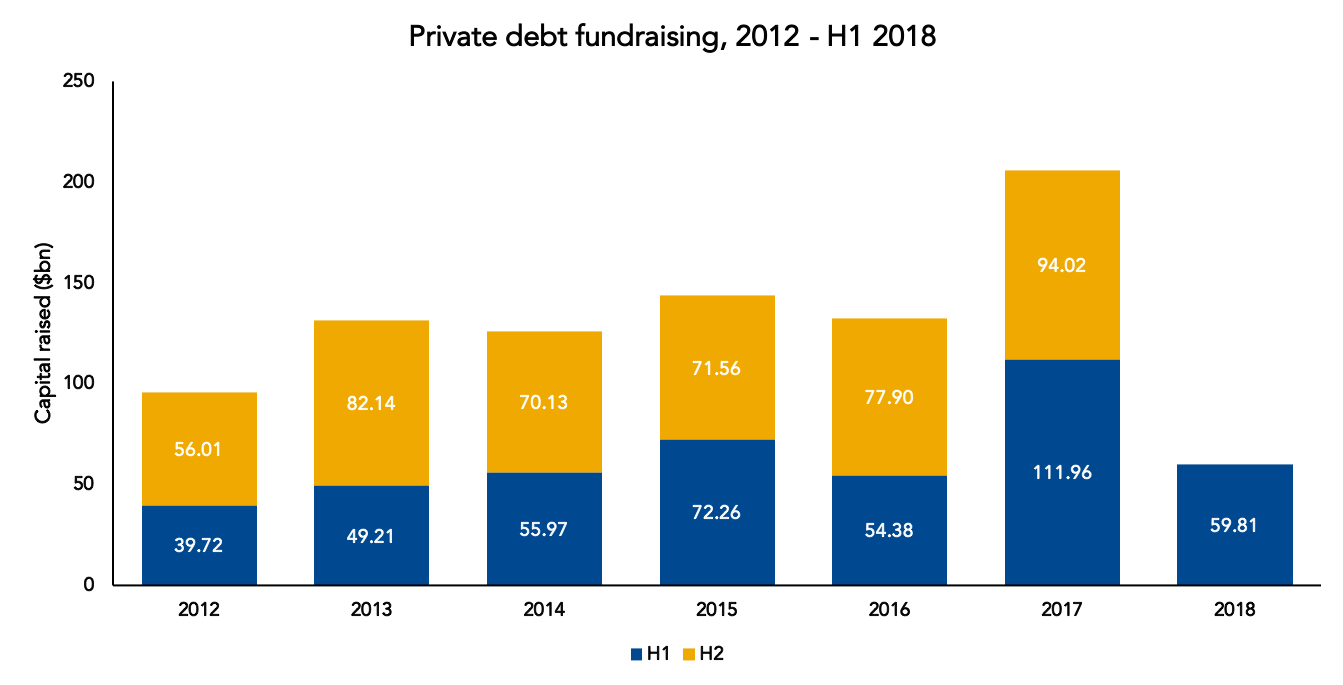
PDI private credit fundraising numbers for the first six months of the year fell by nearly half compared to the same time last year, plummeting from $111.96 billion to $59.81 billion, a seemingly worrying sign.
Though the news won’t make credit managers and their fundraising staff beam with joy, this year’s figures are simply a snapback to a normal fundraising environment; what soars will eventually fall back to earth.
Even when leaving 2017 unaccounted for, the total for H1 2018 is still the second largest figure of the past eight years, behind H1 2015’s $72.26 billion.
What is particularly notable is that the largest funds closed in the first half of 2017 weren’t thrown off by one abnormally large vehicle. Four were north of $4 billion, which consisted of two direct lending funds, one mezzanine vehicle and a multi-strategy fund.
While the headline figure may be not as bad as it seems, there are some ominous signs for smaller credit managers if one digs deeper into the numbers. The two largest funds raised this year accounted for a much larger portion of the total than 2017’s figures, a potential indicator of a smaller number of managers raising even bigger funds.
In 2018, GSO Capital Solutions Fund III wrapped up with more than $7.1 billion in commitments and Broad Street Real Estate Credit Partners III raised $6.7 billion, making up more than one out of every five dollars raised.
Last year, the $4.88 billion Alcentra European Direct Lending Fund II and $4.6 billion Crescent Mezzanine Partners Fund VII were the two largest funds raised in H1 2017, which accounted for not even one out of every 10 dollars raised.
Market sources often tell PDI consolidation is occurring as the industry matures, something that was difficult to notice among last year’s fundraising numbers. Now, we just may be seeing it show up in our fundraising statistics.



Latest news


Information technology topped nonaccruals on a cost basis
Maturities of loans switching to at least partial PIK tends to be longer-dated than Octus’ other stress trackers: nonaccrual and fair value write-down reports.

US Broadly Syndicated Loan CLO Defaults in 3Q26 Driven by Distressed Debt Exchanges
Out of court restructurings drove nearly all default activity within Fitch-rated U.S. broadly syndicated loan (BSL) CLO portfolios in 3Q26, Fitch Ratings says.