


The continent, where the plurality of private debt capital is being sought, highlights both the mature alternative asset markets and the fragmented nature of the European market.
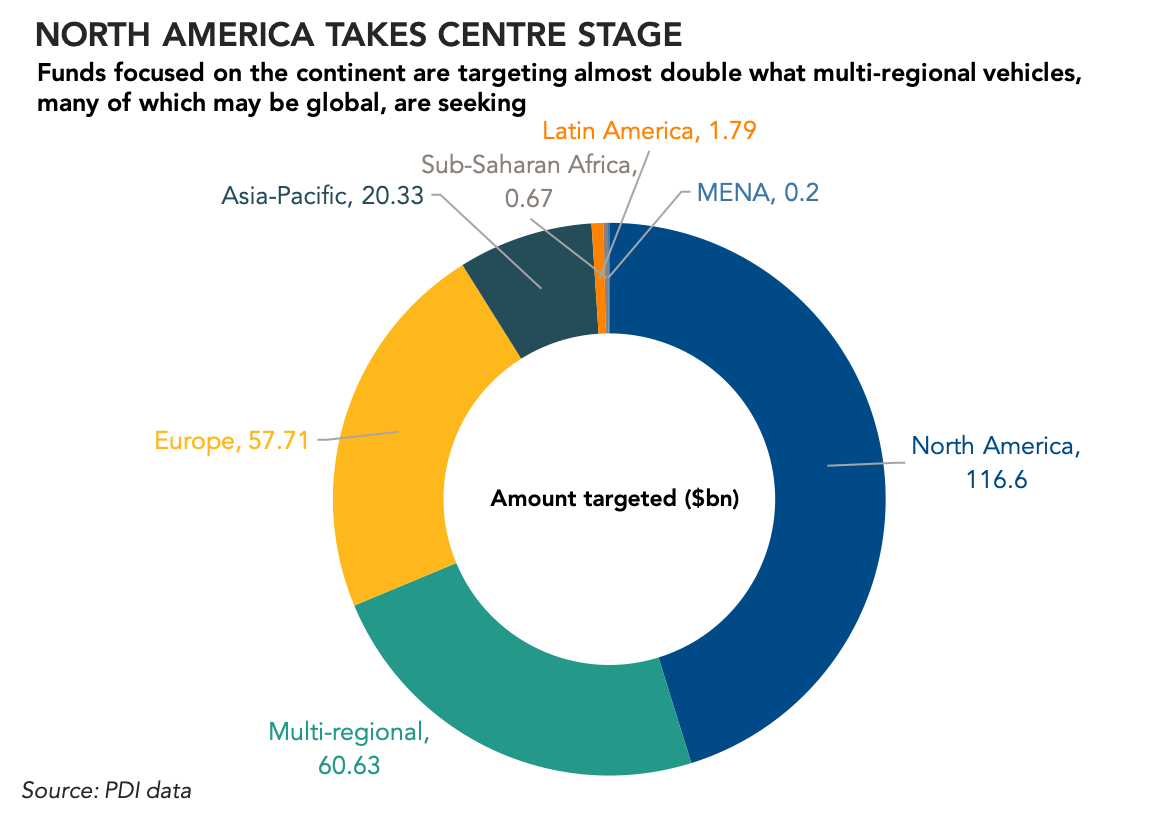
North America has once again stolen the geographic spotlight in private debt; more than 45 percent of the total capital being sought in the private debt world belongs on the continent.
Of the $257.93 billion that in-market private debt funds are looking to raise, North America-focused pools of capital are seeking $116.60 billion. The dominance of the continent highlights two different factors: the dominance of, let’s be honest, the US market, and the concentrated nature of the European private debt market.
The North American private credit markets are years ahead of Europe and even further ahead of the Asia-Pacific region, reflecting a similar dynamic in private equity. North America-focused private equity funds are seeking the most capital as well, according to numbers from sister publication Private Equity International.
That a few firms dominate in Europe can be seen in the total capital being sought there: managers are seeking only $57.71 billion to invest on the continent. Alcentra held a final close on its massive €5.5 billion Alcentra European Direct Lending Fund III in July; without Alcentra’s figure, the European total would have been noticeably lower. A similar dynamic exists with BlueBay Asset Management, which held a close on €6 billion for its latest senior debt fund in February.
It looks like North America is still the place to be for private credit. Perhaps that’s why seven of the 10 most prolific capital raisers – as ranked by our PDI 50 – are based in the US.
Contact: Andrew Hedlund
andrew.h@peimedia.com



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
