


As previously highlighted by Lead Left, and supported by our fundraising data, junior capital strategies are becoming increasingly popular.
In last week’s version of the “Case for Junior Capital”, Lead Left drew attention to some of the positive characteristics of this type of investment in today’s environment including healthy cash/equity percentages, pricing “at or better than” pre-rate hike levels, improved call protection and increased flexibility around PIK toggles.
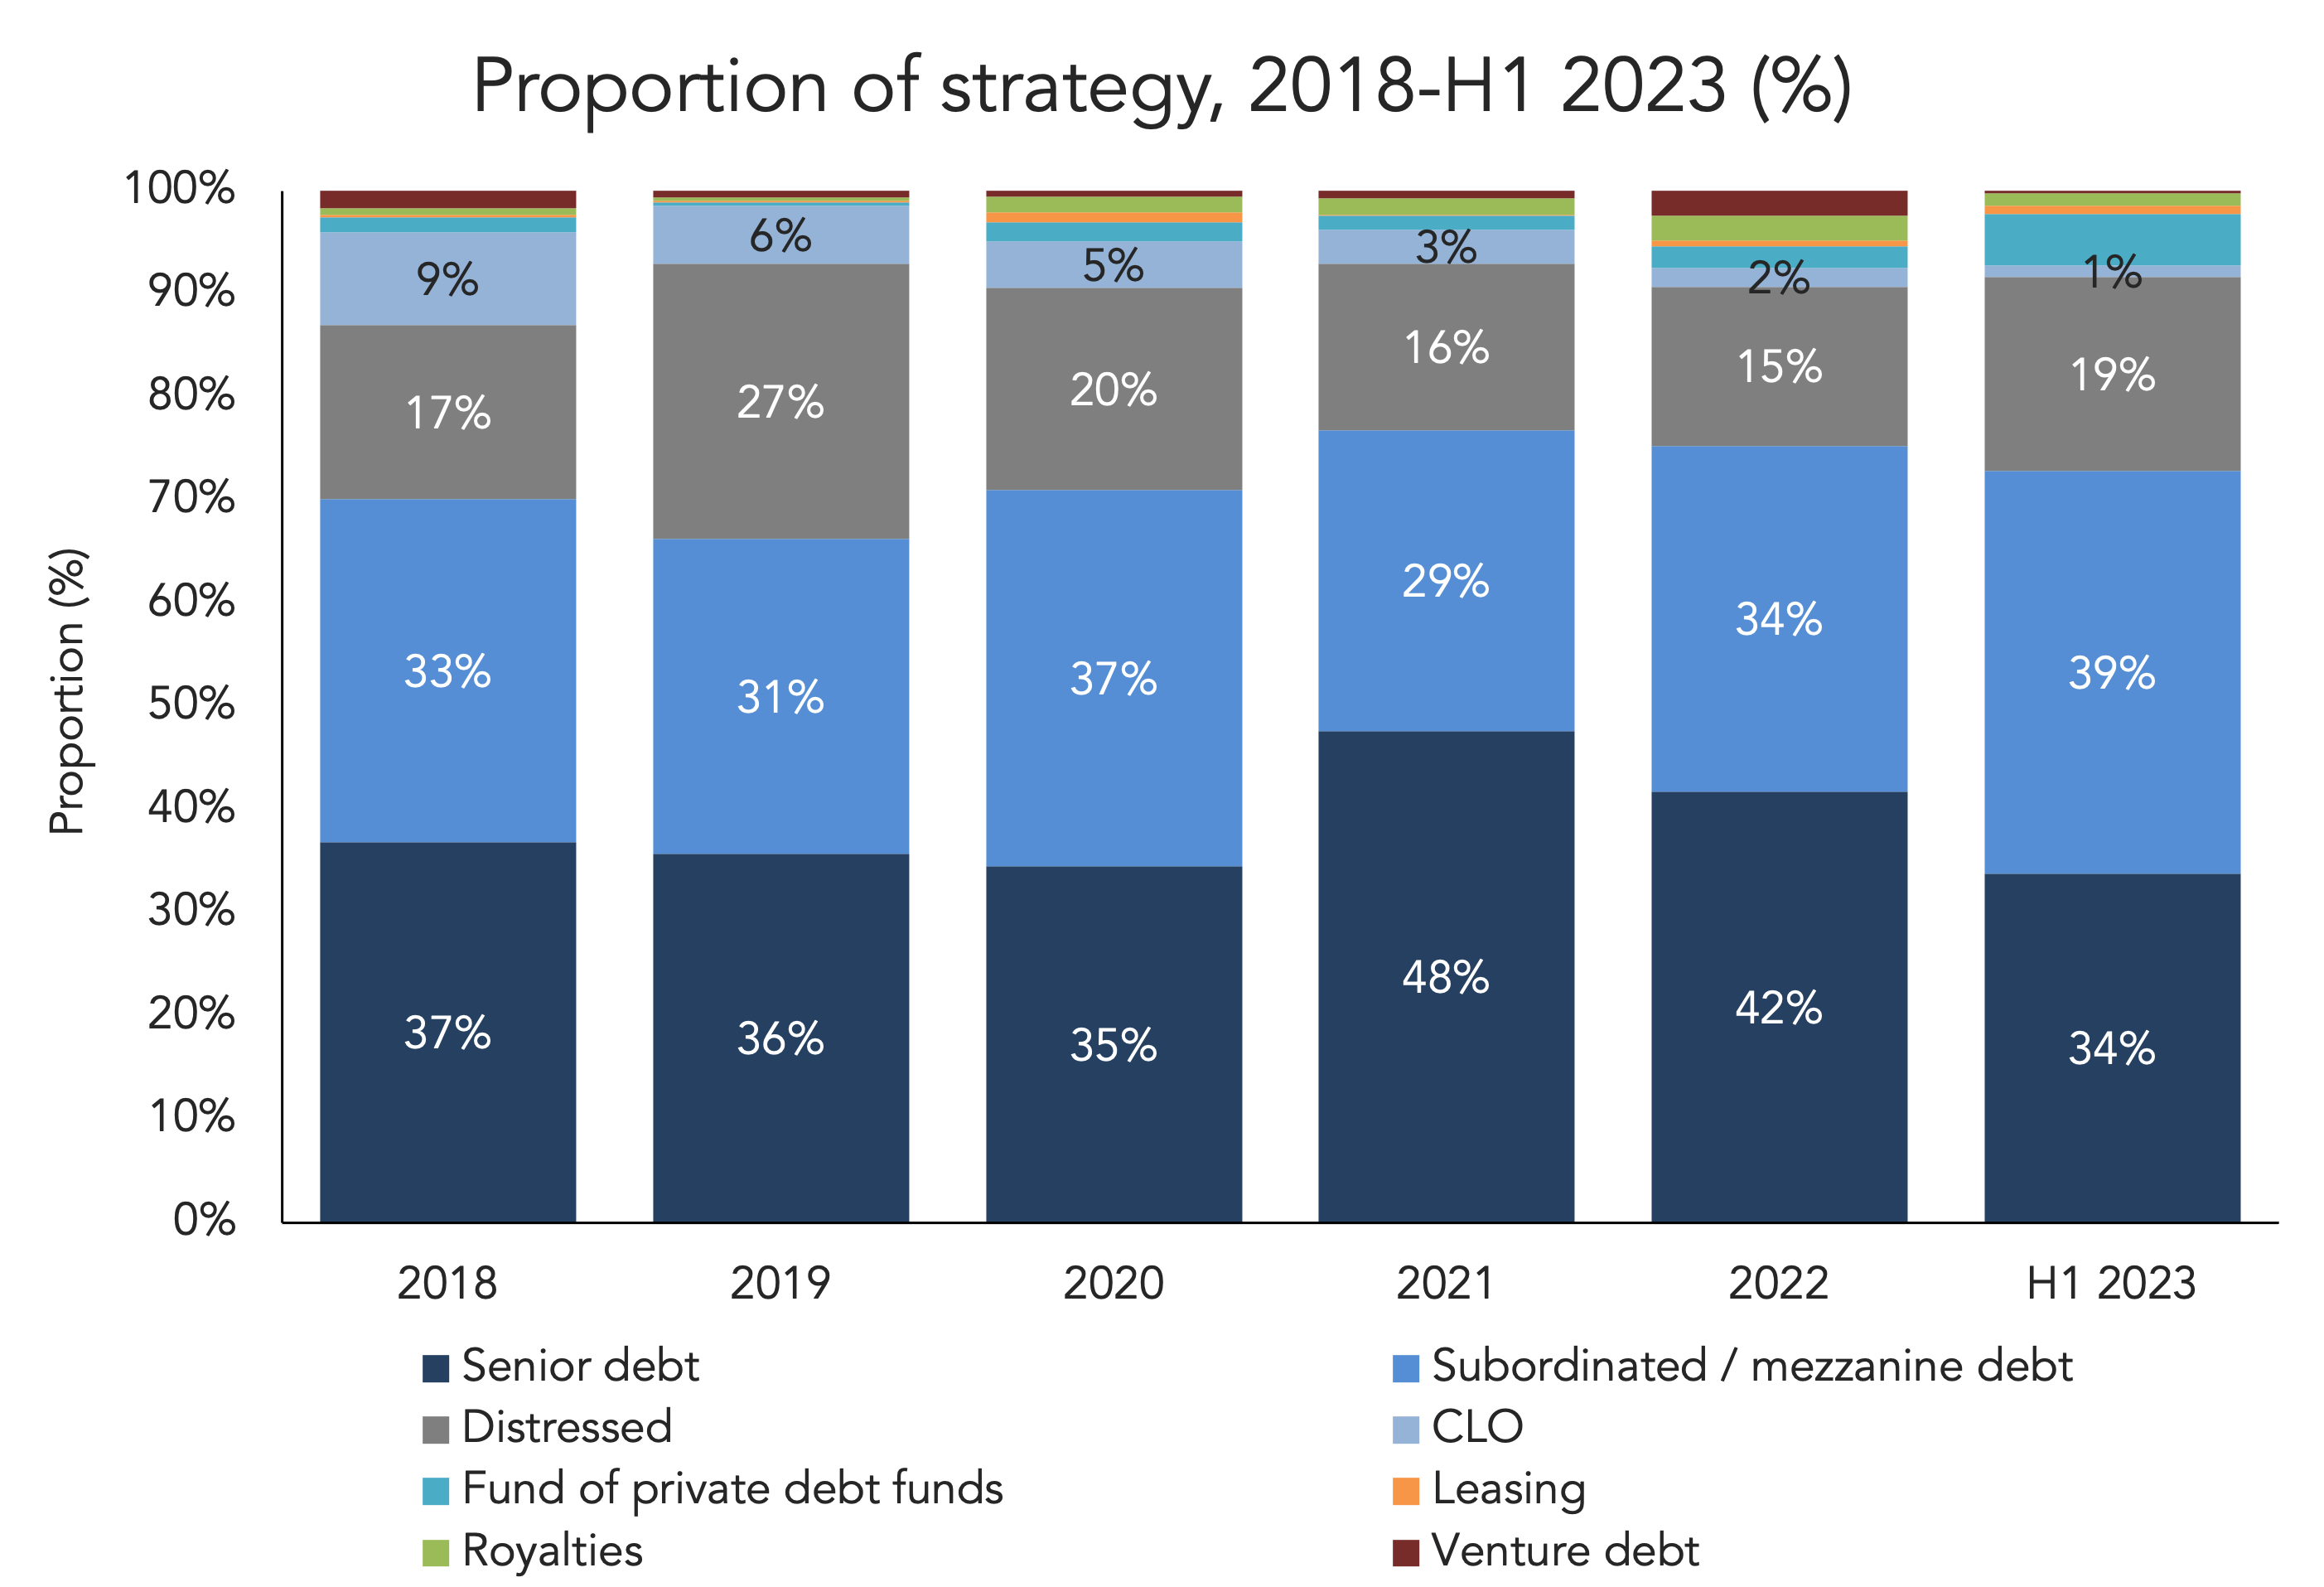
This may help to explain why, in Private Debt Investor’s fundraising figures for the first half of this year, subordinated debt was very much to the fore. The story of recent years has been the dominance of strategies targeting senior debt – peaking at 48 percent of all fundraising in 2021. The first half of this year told a very different story as senior debt slipped to 34 percent of the total, surpassed by the 39 percent accounted for by subordinated and mezzanine debt. This was the highest percentage recorded by the strategy in any year reaching back to 2018 (see chart above).
The figures showed no significant change in investor appetite for distressed fundraising. At 19 percent of the total in the first six months, this was exactly the same proportion that distress has accounted for as an average over the last six years. If there is a wave of distressed opportunity coming, there’s no sign as yet that investors are setting aside significant amounts of capital for it.
Of the strategies that account for smaller capital allocations, it’s notable that funds of funds saw a significant increase in capital raised in the first half of this year, while the challenges facing CLOs saw that market account for just 1 percent of the total – compared with a peak of 9 percent back in 2018.
As noted in this column last week, investor sentiment towards private debt appears to remain very strong despite the subdued H1 numbers. With some of the practical issues facing investors – most notably the denominator effect – appearing to dissipate, a stronger second half of the year can be reasonably anticipated.
(Past performance is no guarantee of future results.)



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.