


Those raising capital for private debt still face challenging conditions despite Q1 have raised hopes of a revival.
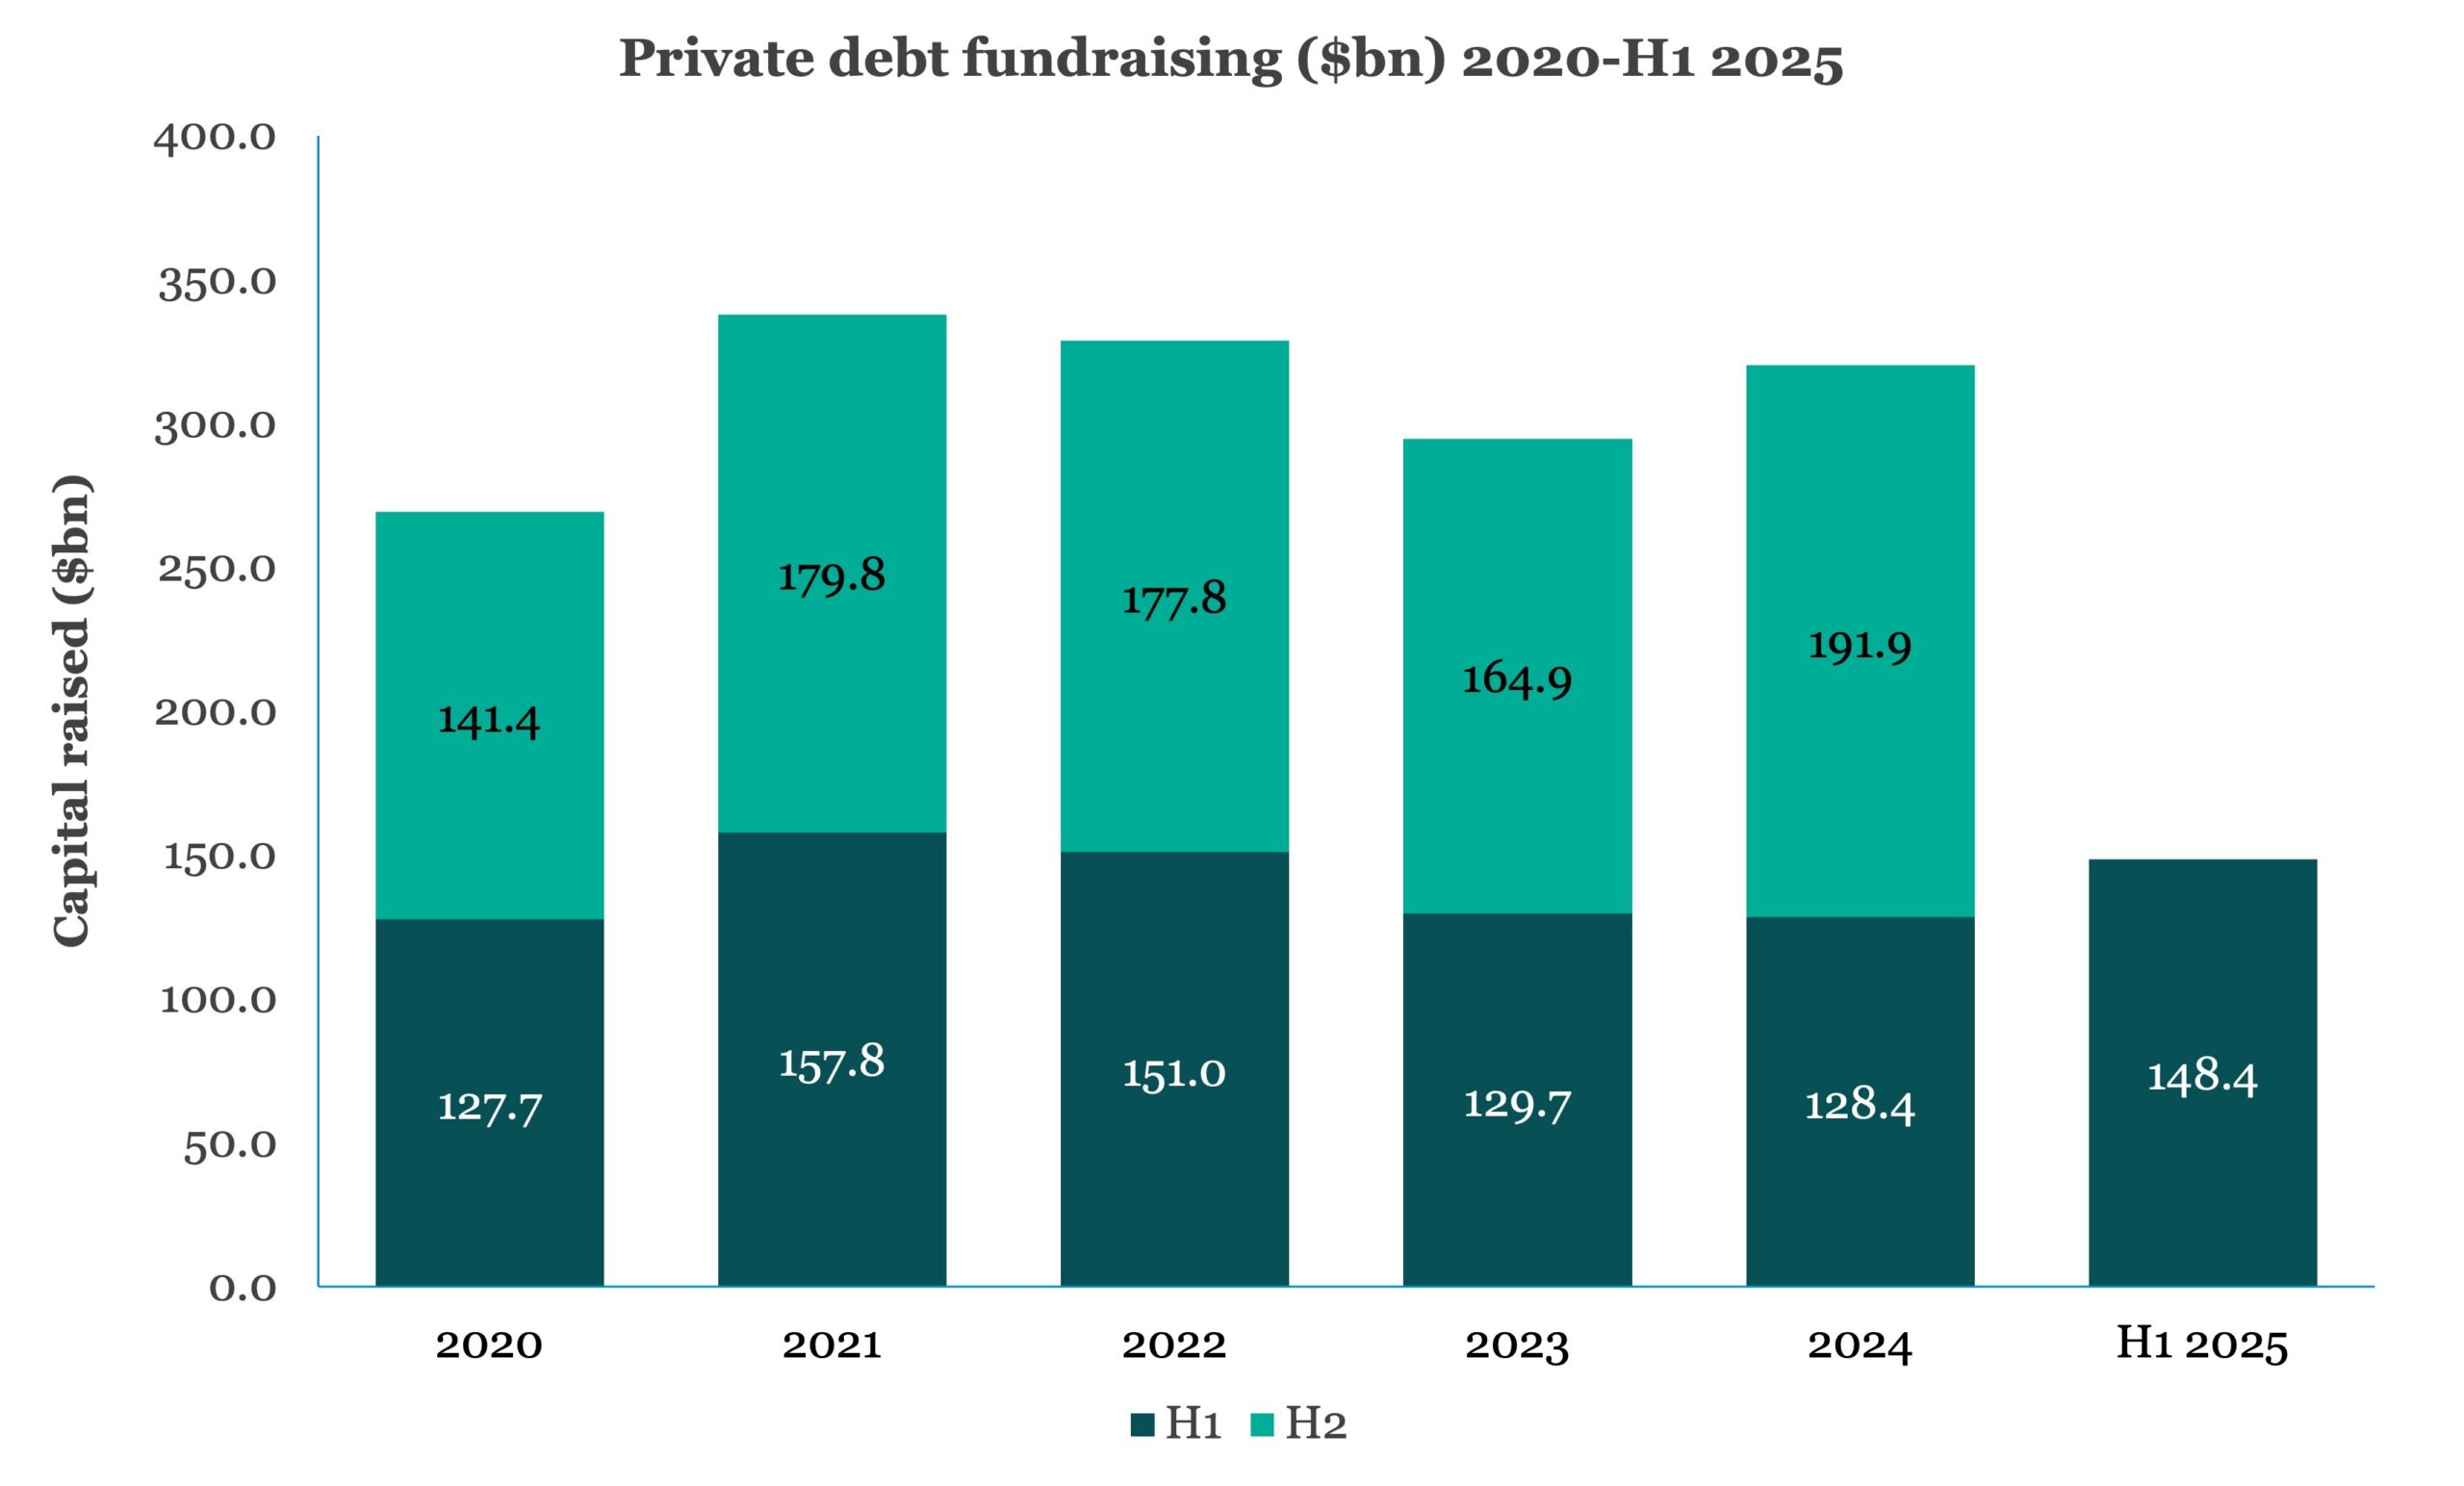
Private debt asset class professionals could be forgiven for scratching their heads when examining the first-half 2025 global private debt fundraising data published by Private Debt Investor.
After all, Q1 was the strongest first quarter on record and raised hopes that a fundraising market which had been subdued since reaching a peak in 2021 might be showing signs of a revival. The caveat was that this quarter included Oaktree’s mammoth $16 billion distressed fund but, even if this fund were removed from the data set, the quarter would still have been very strong.
Then came Q2 – a period which had US tariff volatility as its backdrop – and a virtual reversal of the situation seen in the prior quarter as one of the least productive three months of fundraising in recent times was recorded. After this rollercoaster six months, the first-half total overall was respectable – higher than the H1 totals in 2023 and 2024 but lower than in 2021 and 2022.
Fundraising will likely continue to be something of a puzzle for some time to come. Surveys of investor sentiment consistently show private debt as a popular choice both for those long exposed to the asset class and those entering it for the first time. But practical allocation difficulties persist, such as the lack of capital available to be recycled into private debt from private equity as distribution activity continues to be muted.
Conversations with market sources suggest that indications of a revival in the M&A market are being detected and that that will eventually feed through to improved fundraising for private markets in general. It could be that by the end of this year, and into 2026, the data will be conclusively pointing to better times. Until then, it’s wise to be cautious of false dawns.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…