There are reasons why you might expect esoteric strategies to garner more investor dollars, but it may not be straightforward.
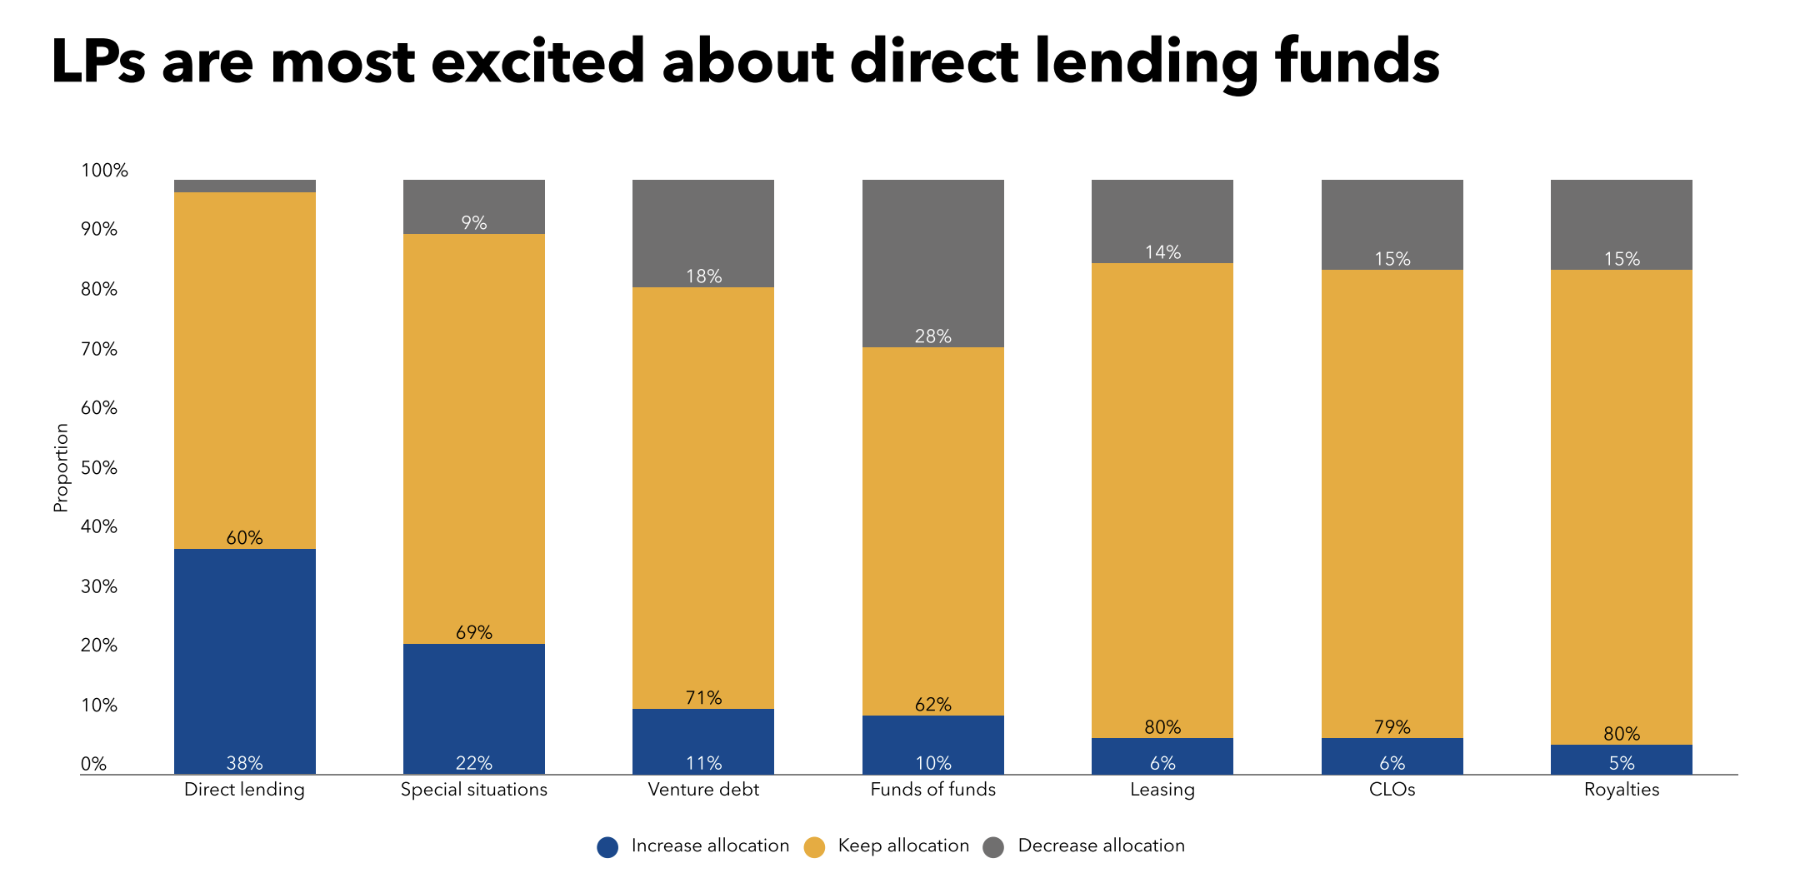
Our Investor Report 2024 shows no obvious change in limited partners’ appetite for different types of private debt strategy. Direct lending has long been in favour and appears to remain so today, when you consider where investors are planning to make their allocations.
On the face of it this is surprising when you take into account the noise around asset-based finance and other types of specialty finance. It was a theme that cropped up in a conversation Private Debt Investor had with Matthias Unser of Yielco, the German fund of funds.
Yielco is now raising its second specialty lending vehicle, with its first such FOF fully allocated. The firm initially found a core group of around 10 to 15 LPs prepared to back the strategy but says it detects increasing interest in the wider LP universe recently.
Because “for the most part they are still quite risk averse”, one of the most interesting and persuasive arguments the likes of Unser can make is that specialty lending is not much riskier – if at all – than direct lending. This flies in the face of the perception that more esoteric strategies necessarily come with more risk.
Unser says that when you combine numerous different speciality strategies – as Yielco does through its funds of funds – the loss rates come out at just over 1 percent (“not much higher than senior direct lending”) while gross IRRs can reach up into the mid-teens: higher than you would expect from direct lending strategies even in today’s higher interest rate world.
“You’re not getting paid only for the risk you’re taking,” says Unser, “you’re mostly getting paid for the complexity or for investing in neglected areas which are not really scalable and where larger capital providers may not be active”.
But even if they can persuade themselves and their boards of specialty finance’s modest risk profile, to expect a new wave of commitments may be far-fetched. One reason is strategic: to suddenly divert significant amounts of capital from one area to another simply doesn’t happen overnight. Another is practical: at the current time, it’s debatable whether there are enough specialty managers to meet demand.



Latest news
Number of smaller funds dwindles
Analysis of fund-close data found that vehicles valued at under $250m have seen a rapid decline since 2024.While PEI Private…

US Private Credit Transparency Highlights Uneven BDC Performance
Credit performance across business development company (BDC) portfolios remains uneven, although reported losses and non-accruals were broadly stable quarter over quarter, according to Fitch Ratings’ Private Credit Transparency Monitor for 2Q26.