


The region is facing an array of headwinds but dealflow held up strongly in the first half of the year.
When you consider all the macroeconomic challenges facing Europe, the fact that the private debt market posted double-digit deal growth in the second quarter of this year is a remarkable testament to the resilience of the market.
Provisional figures from Deloitte’s Q2 Alternative Lender Deal Tracker show that the number of deals done in Europe in H1 2022 rose 16 percent to 395, from 340 a year earlier. For the second quarter alone, there were 216 deals versus 154 recorded in Q2 last year. That’s on top of stellar growth in all the major European markets in the 12 months to March 2022.
The increase in deal volume comes against a backdrop of rising interest rates, inflation hitting levels not seen for decades, supply chains under pressure and energy supplies threatened. Despite all this, Q2 2022 was the busiest second quarter on record, according to Deloitte, as credit funds stepped into a gap left by public markets and banks currently retrenching from corporate lending.
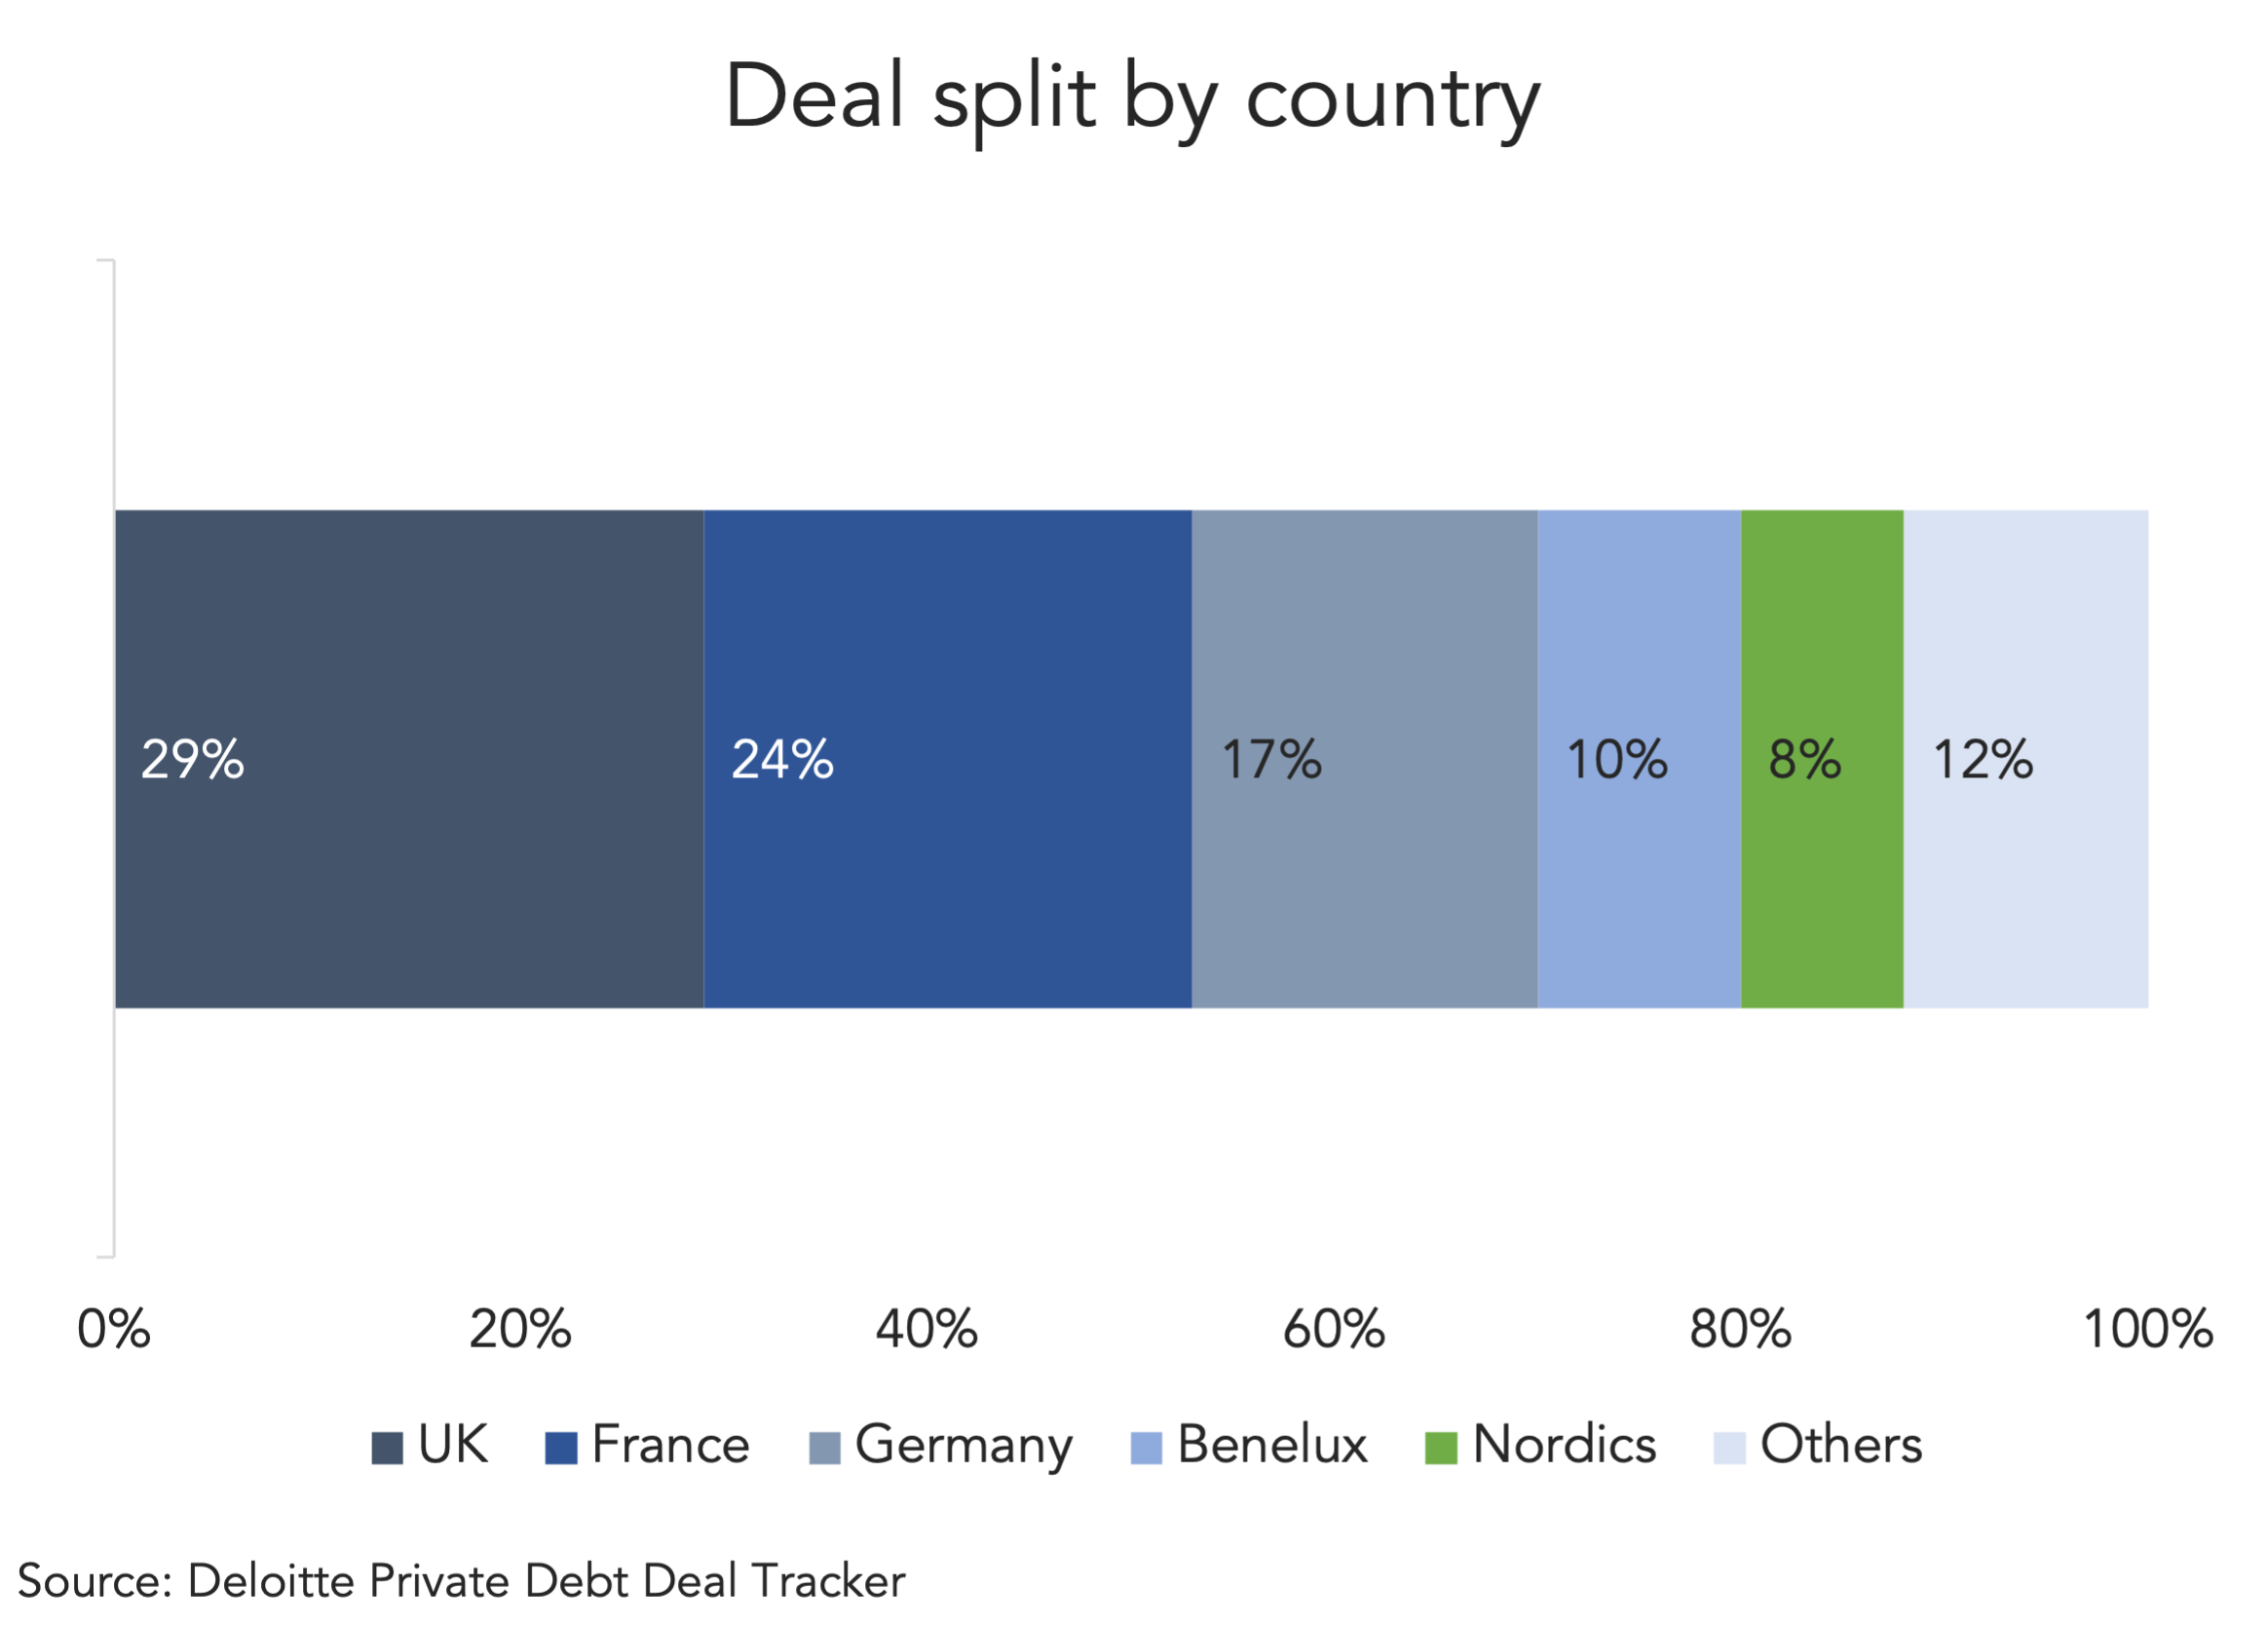
The UK continues to be Europe’s most mature direct lending market and accounted for nearly one in three private debt deals on the continent (see chart). The French appetite for direct lending solutions is growing, recording 52 deals in Q2 versus 30 in the same period a year ago. Germany ranked third by deal volume and Benelux was fourth.
Private lenders have grown market share at pace in H1 and will keep taking share from banks as both borrowers and institutional investors increase their appetite for their offering, market participants say.
Robert Connold, partner in debt advisory at Deloitte, says: “For the whole of the first half of 2022, the number of deals done in [the] European market is up on a like-for-like basis compared to last year. That is incredible bearing in mind the massive uncertainty going on in the public debt markets during the last six months, since the outbreak of the Ukraine war, and shows how the private debt markets have proved incredibly resilient in times of volatility.”
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
