


The coronavirus crisis may have been expected to lead to a fundraising surge for troubled companies. But investors are wary of making bad moves.
Investors may be convinced of the intellectual case for changing their private credit allocations in reaction to the coronavirus crisis and its huge policy response. However, this crisis presents obstacles both old and new to moving from thinking they should do something to actually doing it.
This is partly because of the usual risk aversion that occurs during downturns – but there is a special coronavirus twist. Many investors see distressed opportunities in sectors hit by the pandemic. However, few investors want to allocate money – even to highly skilled distressed managers – if they say upfront: ‘We’re going to be in energy, hotels and airlines.’ Most fear that if something goes wrong, it’s a big career risk. “If my investment fails, people will say, how could I have allocated money to troubled sectors when the coronavirus was not really over?” one source told PDI.
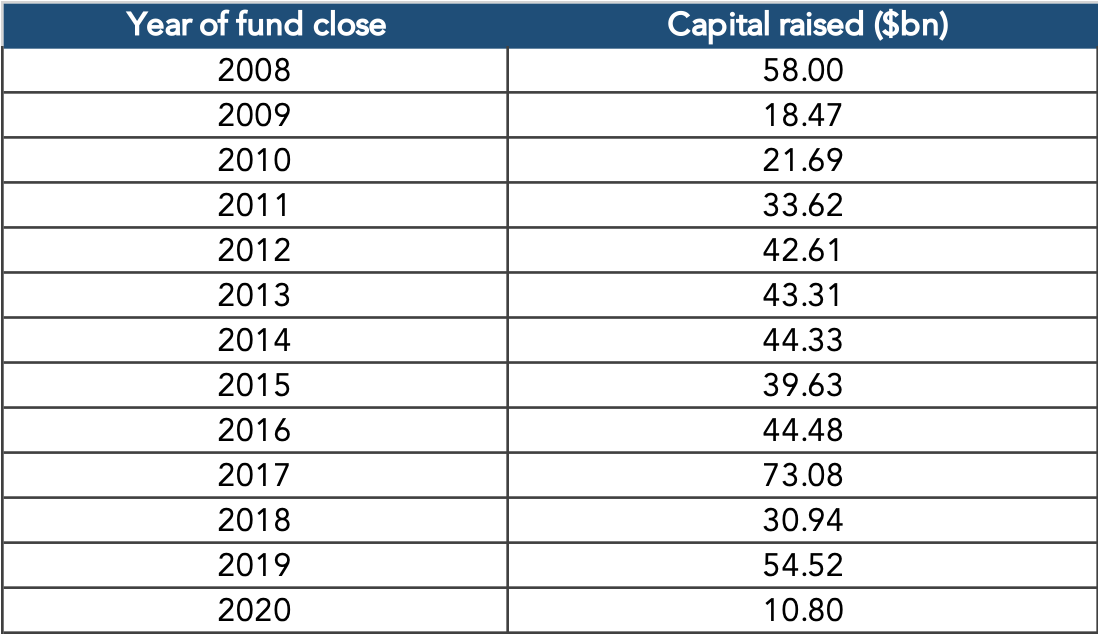
This wariness about seizing the opportunities provided by hard-hit sectors helps explain why distressed fundraising was muted in the first half of 2020 (see chart above). At $10.8 billion globally according to PDI data, it is barely more than a quarter of the corresponding number for H1 2019. If fundraising stays at this level in the second half, 2020 will be the worst year for distressed fundraising since 2009. Its share of total private credit fundraising, at only 17 percent, was also far below normal in H1 2020.
Given this background, the protracted nature of the current distressed opportunity could be just what limited partners need, if they are initially wary of distressed. This time round, “both GPs and LPs have the opportunity to get pre-positioned with thoughtful capital, to help distressed companies. Because the distressed cycle is extended, limited partners can see things playing out, and gradually allocate a bit to distressed, and later on a bit more,” another source remarked.




Latest news
The Recovery Shot
Trouble off the tee doesn’t always translate to trouble on the scorecard.

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Private Credit Defaults 101: Scrambling for Par
Seve Ballesteros won four majors in the 1980s despite being, by his own admission, one of the wildest drivers of the golf ball on tour.