


Preqin Private Debt Intelligence – 5/2/2016

Investor Appetite for Private Debt
For the first time in the history of the private debt asset class, investors surveyed by Preqin in December 2015 are planning to commit more capital to Europe-focused funds than North America-focused funds. While both of these regions have traditionally attracted strong investor interest, only in recent years has regulation, alongside other favourable changes, caused a recognizable growth in investor appetite for exposure to European private debt instruments. In June 2015, 65% of private debt investors were planning to make commitments to both the European and North American markets. However six months later 71% of investors declared they would target the European market compared to just 67% of investors looking to finance deals in North America.
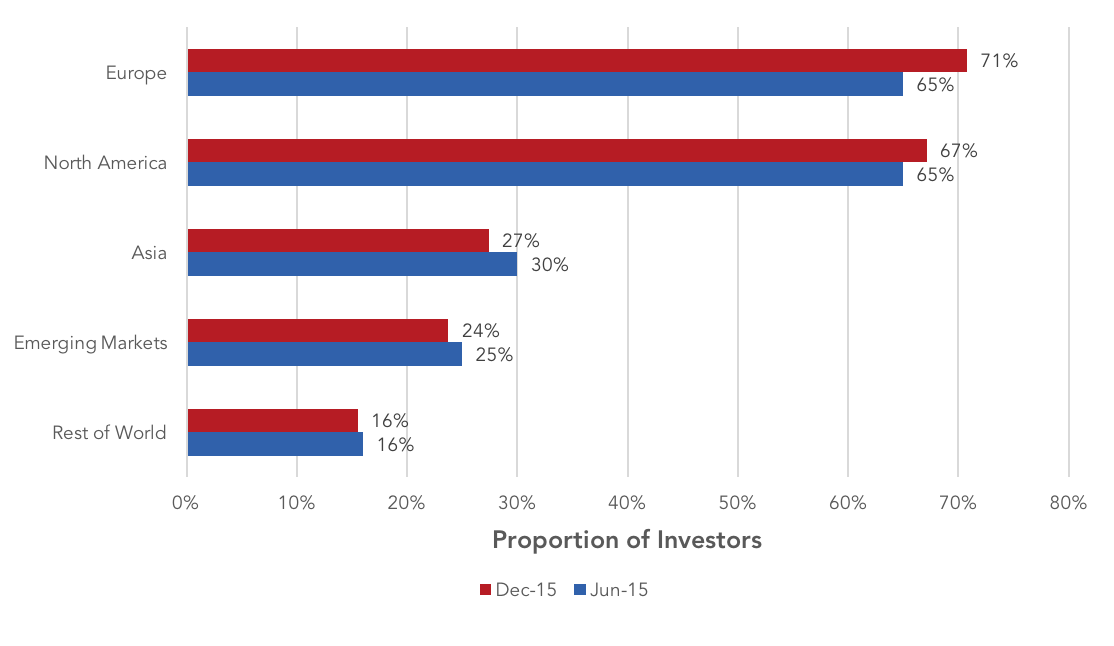
Nonetheless, both regions have seen growth in the proportion of investors intending to commit capital and, globally, the industry is seen in a positive light. Eighteen percent of investors reported that their private debt investments had exceeded their expectations while a further 68% felt their investment objectives had been met. If fund managers can continue to maintain these levels of satisfaction within the more established European and North American markets then they can expect investor interest to grow even further.
Investor appetite for regions outside Europe and North America remains stable albeit low-key, as the proportion of respondents targeting Asia and Emerging Markets has declined slightly since June 2015. Twenty-seven percent of investors were looking to invest in Asia-focused funds in December 2015, down from 30% in June, while 24% were targeting Emerging Markets in December, down from 25% six months earlier. Over the same period interest in Rest of World opportunities has remained constant with 16% planning to invest in these markets before the end of 2016.
Contact: William Clarke
william.clarke@preqin.com



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
