Private Debt Intelligence – 1/14/2019

Overview of Private Debt Fundraising in 2018
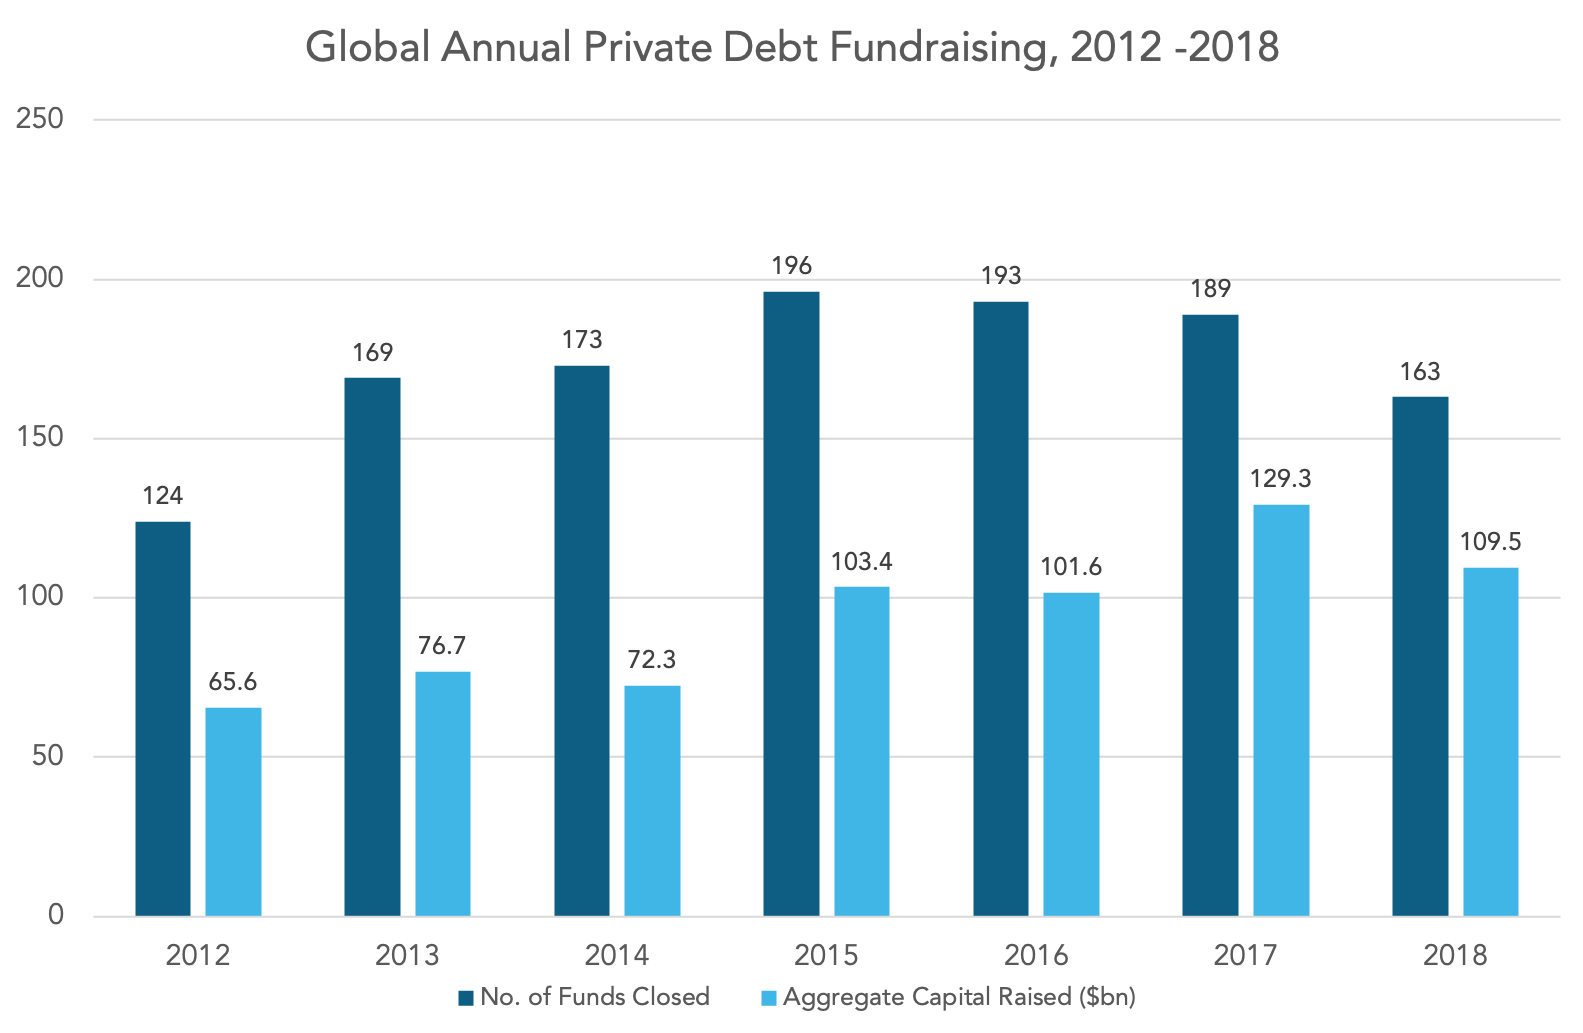
Chart
Download Data
[wpdm_package id=’22452′]
Private debt fundraising remained strong in 2018, making it the fourth consecutive year in which funds raised over $100bn. In 2018, 162 funds were able to secure an aggregate $110bn in capital. While this was slightly lower than the $129bn in capital raised in 2017, 2018 nonetheless represented a strong fundraising year.
Although direct lending and distressed debt traditionally make up two of the largest portions of the private debt market, both strategies recorded declines in aggregate capital raised in 2018. Direct lending fundraising fell from $68bn in 2017 to $45bn in 2018, while distressed debt fundraising fell from $33bn to $21bn in the same period. This curious fall in direct lending may be due to concerns that investors have about the potential for an equity market downturn. The risk of being exposed in the event of a correction may be making investors less inclined to provide the funding component of deals, resulting in a drop in direct lending fundraising.
In contrast to these declines, mezzanine funds saw a marked increase in fundraising from the 2017 level of $12bn raised by 45 funds to $31bn raised by 47 funds in 2018. This figure was helped in part by the closure of the $13bn GS Mezzanine Partners VII, the largest fund of the year.
The persistence of interest in the sector has driven private debt growth in recent years, and this alongside the closure of the largest private debt fund ever serve as signs of strength for the private debt sector. It will be interesting to see if the market builds on these conditions in 2019 and whether the industry shifts further away from direct lending fundraising activity.
Contact: Naomi Feliz
Naomi.Feliz@preqin.com




Latest news
Fitch Ratings’ U.S. Private Credit Default Rate Rose to 6.3% in August 2026
Fitch Ratings recorded a U.S. Private Credit Default Rate (PCDR) of 6.3% for the trailing 12 months (TTM) ended August 2026, up from 6.1% in July 2026 and a record high.