


Private Debt Intelligence – 10/1/2018

Will Europe Direct Lending Activity Outpace North America?
Chart
Download Data
[wpdm_package id=’20445′]
Direct lending is a relatively young strategy, but has gained traction in the past five years or so, quickly becoming one of the more dominant private debt fund types. As with the larger private debt universe, North America and Europe account for the majority of direct lending activity, with North America seeing the largest number of fund closures and the most capital raised of any region. However, 2018 has seen Europe direct lending activity squeaking past North America’s.
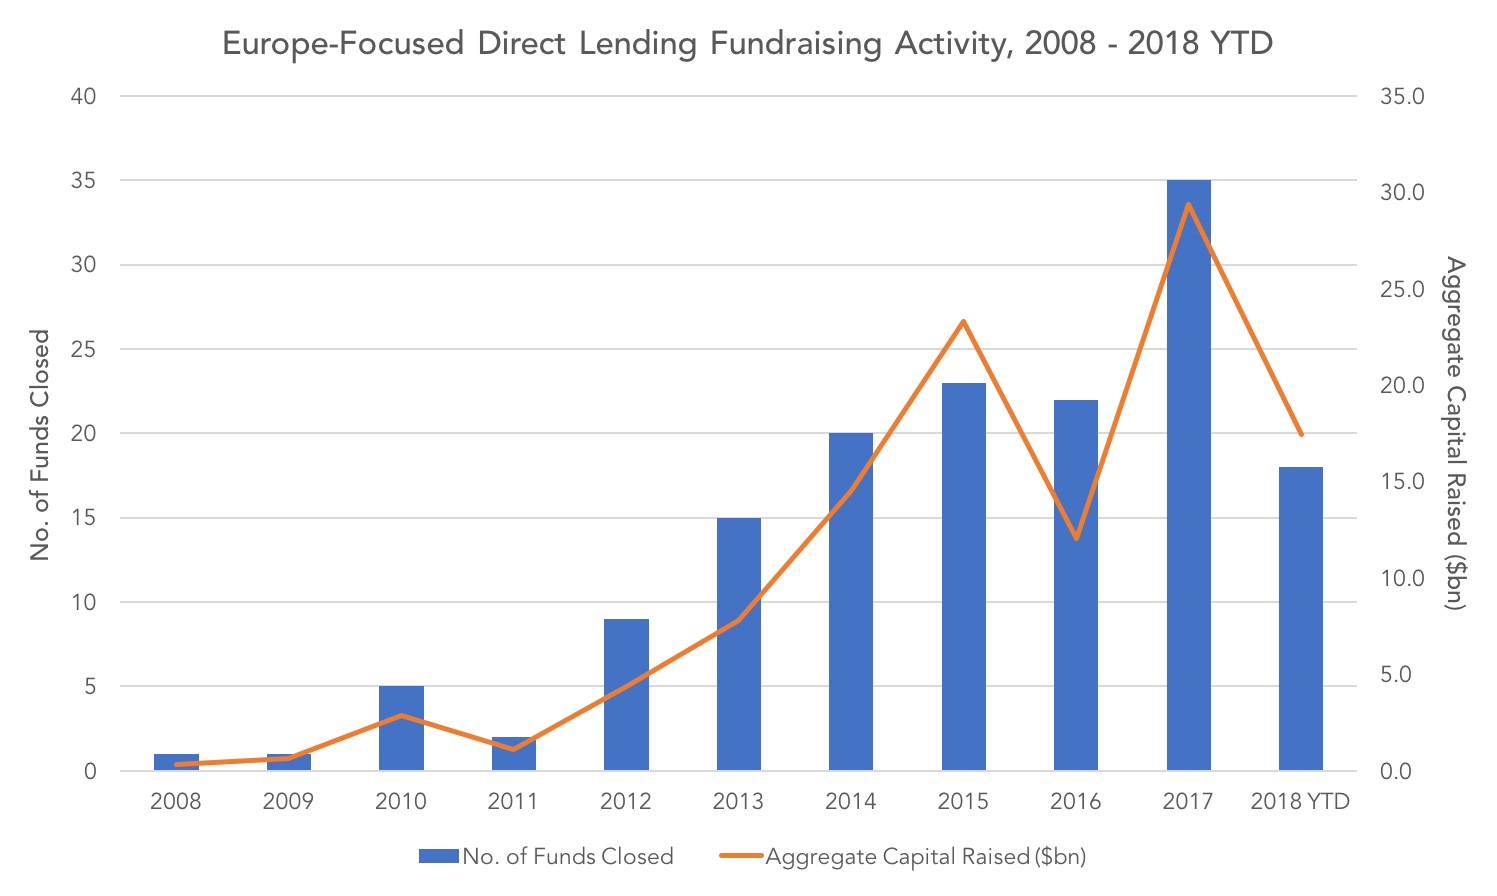
Over the past 10 years, Europe-focused direct lending activity has surpassed North America-focused direct lending levels in just 2015, when 23 Europe-focused funds raised over $23bn in capital. This was the year in which the six largest direct lending funds closed were all Europe-focused, including the largest Europe-focused direct lending vehicle ever closed: European Loan Programme, which closed on $3.3bn. However, every year since then, there have been more North America-focused funds closed than Europe-focused funds, and more capital raised for the North America direct lending industry.
However, Europe-focused direct lending looks like it could surpass North America-focused activity in 2018, as the two regions are seeing neck-in-neck fundraising activity. In the first three quarters of 2018, 18 Europe-focused funds have raised over $17bn, while 17 North America-focused funds have held a final close and raised $16bn in aggregate capital.
Although both regions are seeing strong direct lending fundraising activity, 2018 nonetheless represents a significant slowdown for both regions from the year prior. In 2017, 38 North America-focused direct lending funds held a final close and raised a record $40bn for the region. Europe also had a record year in 2017, as 35 Europe-focused funds raised $29bn. However, both regions could very well see their levels of activity match previous years, and Europe-focused direct lending activity might surpass North America-focused activity for just the second time in a decade.
Contact: Naomi Feliz
Naomi.Feliz@preqin.com



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
