


Private Debt Intelligence – 10/7/2019

Private Debt Continued with a Slow Fundraising in Q3
Chart
Download Data
[wpdm_package id=’28893′]
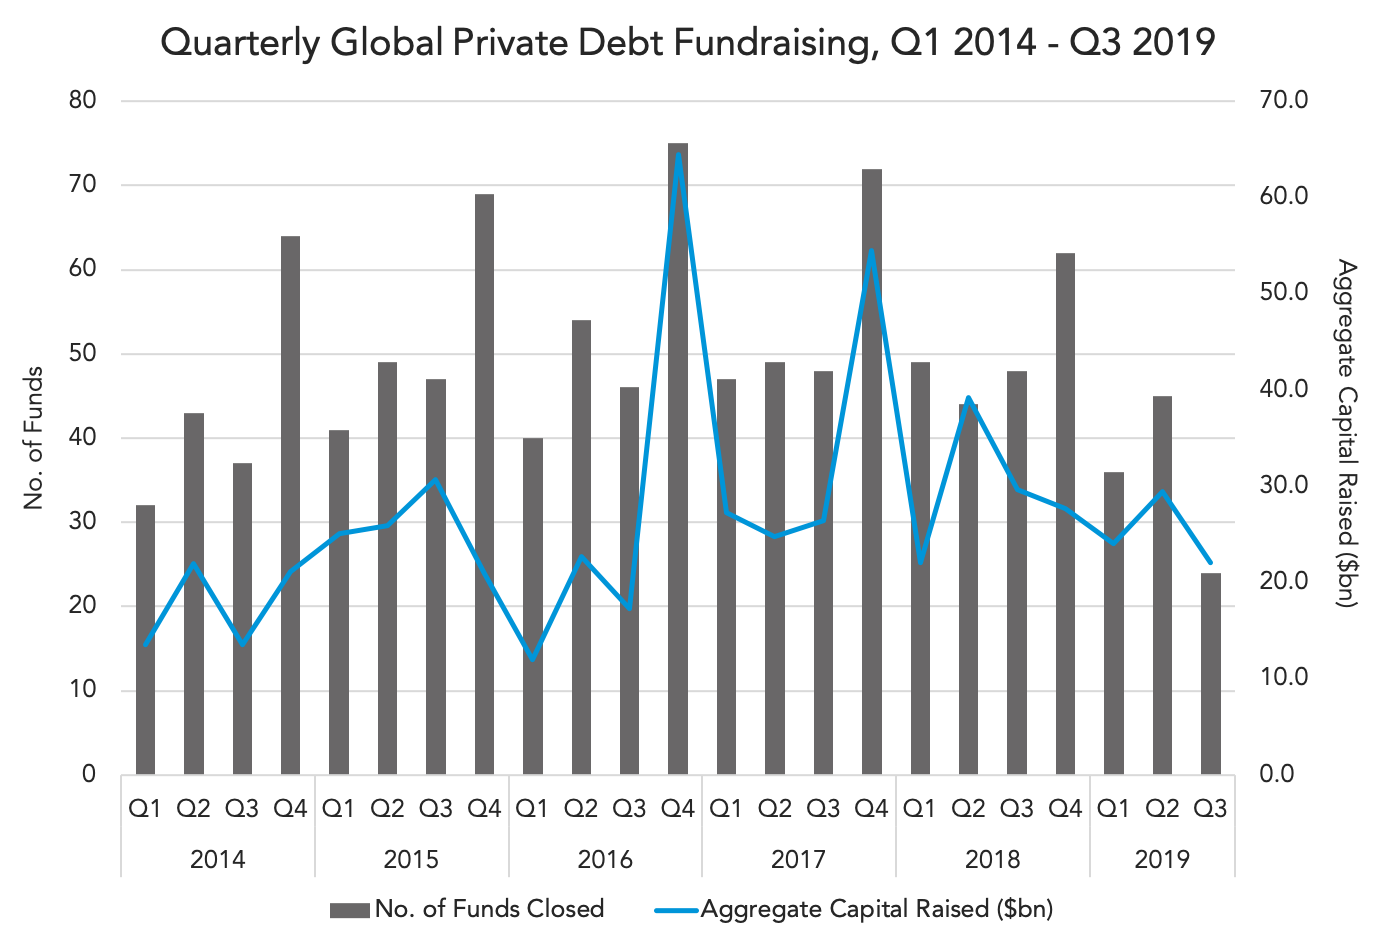
Q3 showed no signs of recovery of, what has so far been, a slow fundraising year for private debt, closing just 24 funds for $22bn in capital, both quarterly lows for the year and the lowest amount of capital raised in any quarter since Q3 2016. Furthermore, during the corresponding quarter in 2018, exactly twice as many funds were closed. That said, the levels of aggregate capital raised remain somewhat consistent in an environment where competition for lending opportunities remains a pressing concern for investors as the market continues to mature.
Punctuating the poor fundraising performance this quarter, only a single fund type raised a meaningful amount of capital. Usually the strongest performer in the asset class, direct lending funds accounted for over 90% ($20bn) of all capital raised in Q3; the $49bn raised so far this year leaves them within reach of surpassing 2017’s peak. In the remainder of the asset class, only the mezzanine fund type has closed more than a single fund, securing $1.1bn. Within the other strategies, only special situations hit the $1bn mark in fundraising, which is a big drop down compared to Q2 were $4.9bn were secured.
Looking regionally, it appears that Europe-focused funds bounced back strong from a disappointing Q2, outpacing all other locations with $14bn raised. In contrast, North America-focused funds secured $6.5bn, almost half of their Q2 total and Asia-focused funds held stable, closing 3 funds with a value of $1.5bn. In the rest of the world, two funds were closed; one Africa-focused, raising $100mn and another Latin America-focused securing $30mn.
However, if we have a look to the private debt fundraising trend over the years, it shows a clear cyclical pattern whereby totals generally peak in Q4 of each year. In this regard, 2019 totals may yet rise significantly.
Contact: Maria Zapata
maria.zapata@preqin.com



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026, reaching an average of 553bps over reference rates, up from 542bps in the first quarter.

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.