Private Debt Intelligence – 2/25/2019

Ample Room Left for Private Debt Growth
Chart
Download Data
[wpdm_package id=’23309′]
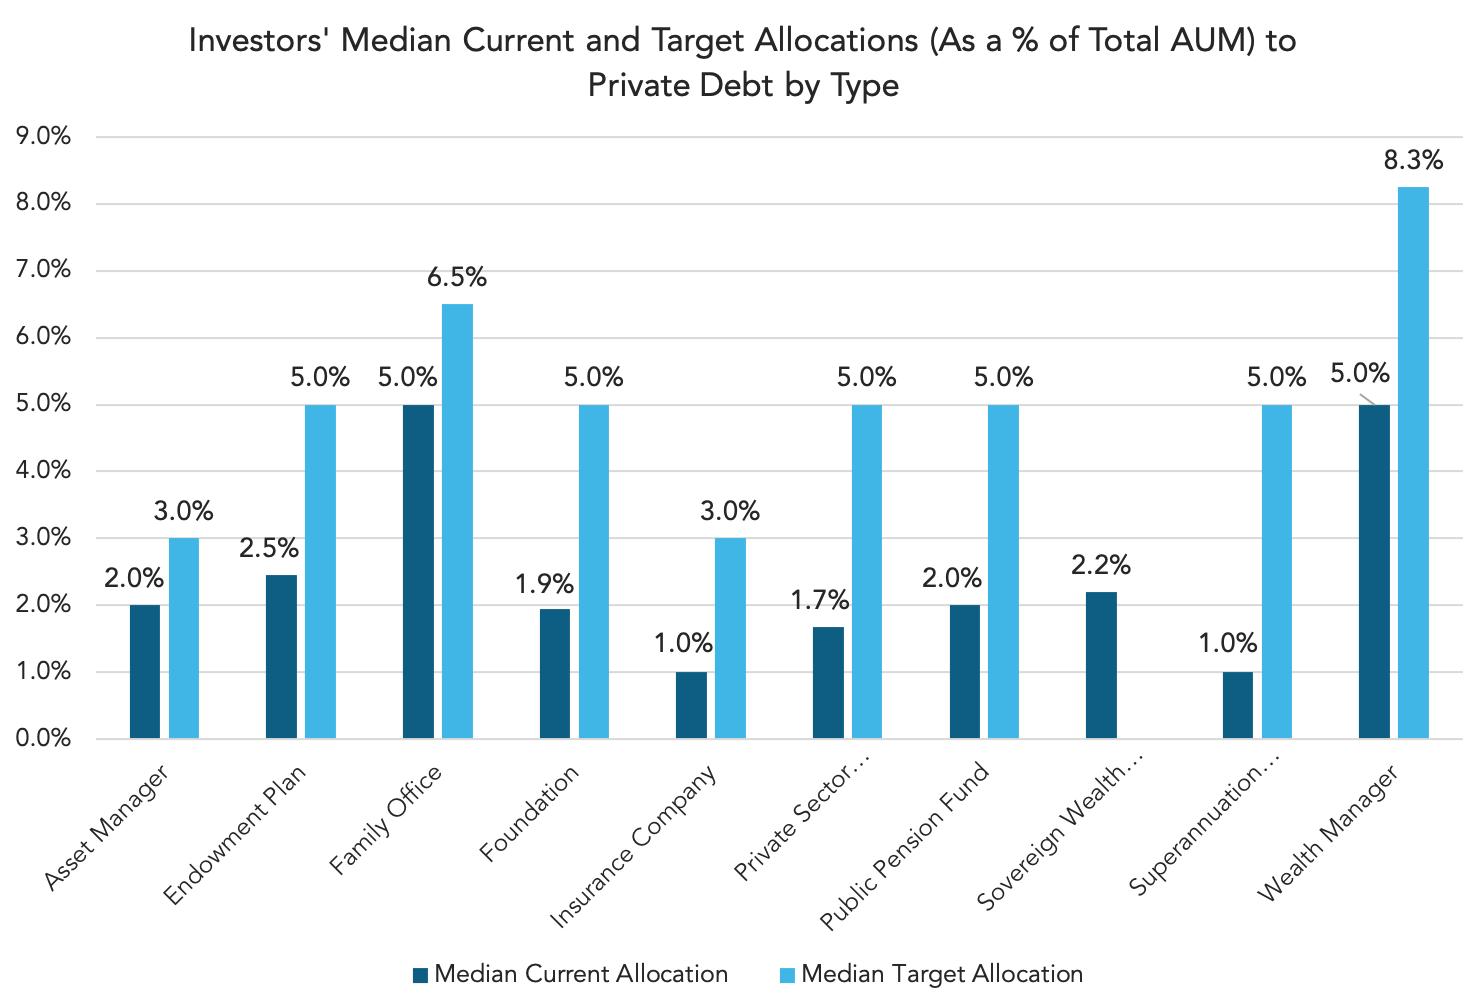
Investors are, on average, well below their target allocations to private debt, and over the next 12 months a third of investors will look to commit more capital than they did in the previous 12 months in an effort to move closer to their targets. Over the longer term, investors are expecting private debt to remain a core, and increasingly prevalent, part of their portfolios: almost half of investors plan to increase their target allocations to the asset class. The potential for even further growth is huge. Although the number of institutions actively investing in private debt has increased significantly from 2,643 in 2016 to 3,645 in 2018, this represents only around 30% of all investors tracked by Preqin.
The private debt asset class is also beginning to benefit from the growing pool of more than 1,600 fund managers, especially in North America and Europe. While firms continue to enter the market all the time, there are signs of capital concentration (so prevalent in other asset classes) beginning to take effect in private debt. First-time fund managers secured just 6% of total capital raised by funds closed in 2018, down from 16% in 2014.
The asset class has delivered for investors in recent years, with superior returns, good liquidity and yield as well as portfolio diversification. However, this rapid growth has also created competition for deals, leading to yield compression and erosion of covenants. As a result, over half (53%) of surveyed fund managers believe competition for assets will be a key challenge for return generation in 2019. In addition, the Federal Reserve has expressed concerns about non-bank credit being a potential risk for financial stability, suggesting it may not be smooth sailing for this thriving asset class in the months ahead.
The general consensus is that private debt will remain a prominent part of investors’ portfolios worldwide, and these portfolios will become more sophisticated and diverse over time. The opportunities exist for fund managers to secure capital from investors, but with new fund managers entering the asset class all the time and competition intensifying, they must be able to differentiate themselves from their peers and show they can deliver even in challenging times.
Contact: Naomi Feliz
Naomi.Feliz@preqin.com



Latest news

US Leveraged Loan Issuance Rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.