


Private Debt Intelligence – 2/5/2018

Investment Consultant Outlook for 2018
Chart
Download Data
[wpdm_package id=’16372′]
There are currently 547 alternative investment consultants globally and of these, 41% provide private debt advisory services to their clients. In November 2017, Preqin conducted a survey of 36 consultants active in private debt to determine their sentiment with respect to the private debt industry.
Sentiment with regards to private debt returns has largely been positive in 2017. Of the investment consultants surveyed, 44% reported that private debt performance had met expectations. An additional 40% reported that private debt performance had exceeded expectations during the year.
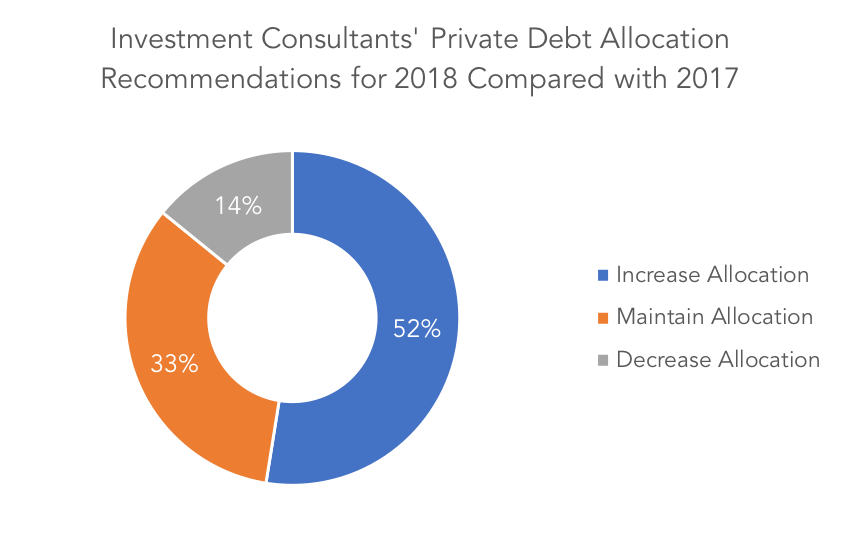
With such positive sentiment on returns, it is unsurprising that the majority (52%) of private debt investment consultants have stated that they will be recommending their clients to increase allocations to the asset class in 2018 in comparison to 2017. A third of private debt investment consultants will recommend their clients to maintain allocations in the upcoming year, while just 14% will recommend that their clients decrease allocations to private debt in 2018.
Consistent with results seen over recent years, direct lending appears to be the preferred private debt fund type among investment consultants. Three-quarters of investment consultants will advise their clients to invest either more or the same amount of capital in the coming year in comparison to 2017, while 19% will advise to invest less. Private debt consultants also reported that they will be advising their clients to direct more capital towards special situations (44%) and distressed debt (40%) strategies. Venture debt, however, is likely to feature less prominently in 2018, with over two-thirds (67%) of respondents advising against the strategy in both 2017 and 2018.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
