


Private Debt Intelligence – 2/20/2017

Credit Strategies Start 2017 with Positive Performance in January
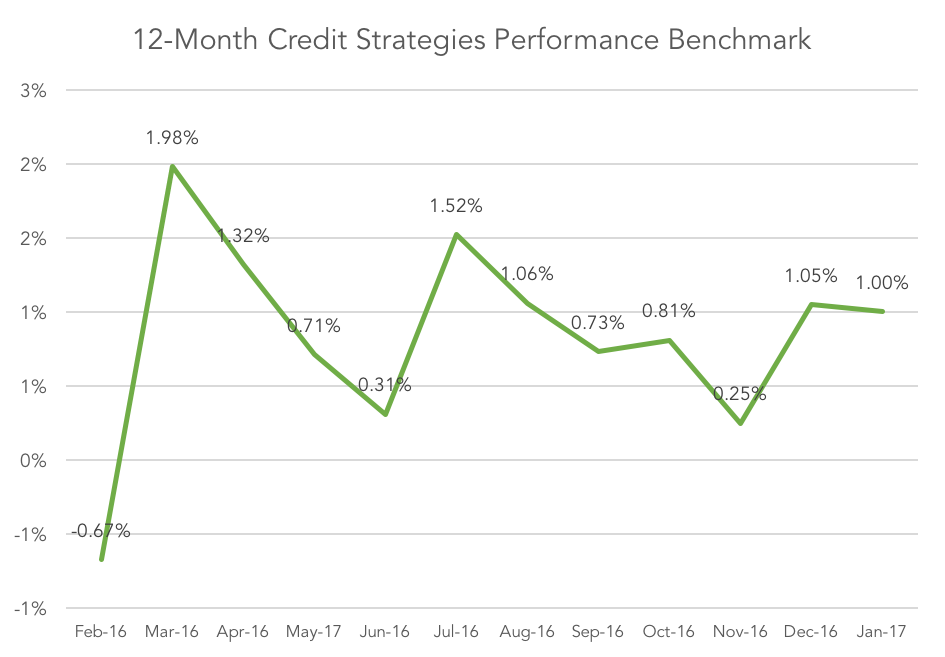
Preqin research finds that credit strategies have maintained their positive performance from 2016, with a strong start to the year through January 2017, as investor and fund manager confidence in the strategy grows.
Credit strategies were the second best performing leading hedge fund strategy last year with annual returns of 8.50%, well outstripping the Preqin All-Strategies Hedge Fund benchmark (7.40%). Following the wider industry trend, credit strategies started poorly in 2016 with two months of losses in January and February as they suffered from global market volatility, however the strategy recovered robustly to post ten consecutive months of gains.
This momentum has continued in to 2017 with January, extending the run of gains to 11 consecutive months, directly building on the gains of 1.05% generated in December. Credit strategies returned 1.00% through the first month of the year to take 12-month performance into double digits (10.51%) for the first time since August 2014.
Poor performance is a key concern for investors participating in the hedge fund industry at present, and the returns generated by credit strategy funds have not gone unnoticed by investors.
More than two-thirds (69%) of investors surveyed by Preqin at the end of 2016 stated that credit strategies had either met or exceeded their expectations, the second highest level of satisfaction seen by any leading strategy. Furthermore, 88% of investors also believe that they will either maintain or increase their allocation to the strategy.
This statement of future intent will leave managers hopeful of reversing the net outflows of $28bn suffered by the strategy over the course of 2016. The clear correlation between past performance and asset flows will also reassure firms involved in the credit strategy space that they may experience a smoother fundraising landscape in 2017.
The year ahead looks set to be dominated by performance and fee concerns by investors. Credit strategies have started strongly and are clearly favoured by investors at the minute; if firms can continue to generate gains at their current rate, there is no reason why the strategy cannot enjoy a successful year.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
